







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
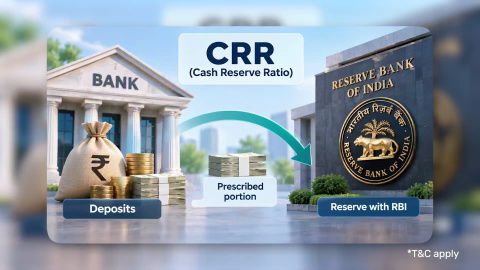
Cash Reserve Ratio (CRR)
In summary
The cash reserve ratio (CRR) is a monetary policy tool used by the Reserve Bank of India (RBI) to influence banking-system liquidity.
- CRR is calculated as a percentage of a bank's net demand and time liabilities (NDTL).
- Banks subject to CRR requirements maintain the prescribed balance with the RBI.
- The current CRR is 3.00% as of 2 November 2026.
- A higher CRR generally reduces funds available for other banking activities.
- A lower CRR generally releases liquidity into the banking system.
- Changes in CRR do not automatically change individual home loan EMIs.
For borrowers, CRR is useful for understanding changes in the lending environment. However, the rate and repayment terms in your actual home loan agreement matter more when calculating monthly costs.
What is Cash Reserve Ratio (CRR)?
The cash reserve ratio is the percentage of specified bank liabilities that a bank must maintain as a cash balance with the RBI. The requirement is established under India's banking and monetary framework. For scheduled commercial banks, Section 42 of the Reserve Bank of India Act, 1934 provides the principal statutory basis. The RBI determines the applicable ratio from time to time.
For example, when CRR is 3%, a bank with Rs. 1,000 crore in relevant NDTL has a basic reserve requirement of Rs. 30 crore. These funds must be maintained according to the RBI's prescribed conditions rather than being freely available for loans or investments.
CRR does not mean a bank must reserve 3% of every individual customer's account balance in a separate account.
Show more
Show less
What is the current CRR rate in India?
The RBI's published current cash reserve ratio is 3.00% as of 2 November 2026.
| RBI indicator | Published rate |
| Cash reserve ratio (CRR) | 3.00% |
| Statutory liquidity ratio (SLR) | 18.00% |
| Policy repo rate | 5.50% |
Last updated: 3rd November 2026
These indicators serve different purposes and should not be treated as interchangeable.
CRR sets a reserve-balance requirement, SLR addresses eligible liquid-asset holdings, and the repo rate is a key policy interest rate. The RBI can revise these rates through separate policy decisions.
For the latest figures, refer to the Reserve Bank of India's current rates.
Show more
Show less
How is the cash reserve ratio calculated?
CRR is calculated by applying the prescribed percentage to the bank's relevant net demand and time liabilities.
Required CRR balance = NDTL × CRR percentage ÷ 100
NDTL includes specified demand and time liabilities, after applying the exclusions and adjustments prescribed by the RBI.
Example: Calculating CRR for a bank
Suppose a bank has relevant NDTL of Rs. 2,000 crore.
At the current 3% CRR:
| Particulars | Amount |
| Relevant NDTL | Rs. 2,000 crore |
| Applicable CRR | 3.00% |
| Required reserve balance | Rs. 60 crore |
Calculation: Rs. 2,000 crore × 3% = Rs. 60 crore
This is an illustrative calculation. Actual CRR compliance uses the RBI's prescribed reference period, average-balance requirements and reporting rules. It should not be interpreted as a simple requirement to place Rs. 60 crore with the RBI on only one selected day.
Show more
Show less
What are net demand and time liabilities?
Net demand and time liabilities, or NDTL, form the base used for calculating the CRR requirement. Broadly, banks have liabilities that are repayable on demand and liabilities that become payable after a specified period.
| Type | What it means | Examples |
| Demand liabilities | Amounts generally payable on demand | Current-account balances and relevant demand deposits |
| Time liabilities | Amounts generally payable after a specified period | Fixed deposits and other qualifying term liabilities |
| Other relevant liabilities | Additional obligations included under RBI rules | Specified accrued or other banking liabilities |
| Prescribed adjustments | Amounts excluded or netted under the rules | Relevant interbank and statutory adjustments |
NDTL is not simply a bank's total retail deposits. The RBI's computation rules determine which liabilities are included, excluded or adjusted.
This distinction matters because applying CRR to total deposits without the prescribed adjustments can produce an incorrect regulatory calculation.
Show more
Show less
Why does the RBI use CRR?
CRR helps the RBI manage banking-system liquidity and influence monetary conditions. When the RBI changes CRR, it changes how much of the relevant banking liabilities must be held in reserve.
The main functions include:
- Managing liquidity: Influences the amount of funds available in the banking system.
- Moderating credit expansion: A higher requirement can constrain banks' ability to deploy funds elsewhere.
- Supporting monetary policy: Works alongside the repo rate and other instruments.
- Maintaining prescribed reserves: Requires banks to hold balances with the central bank.
- Responding to economic conditions: Gives the RBI another tool to address liquidity changes.
CRR is not a standalone solution to inflation or financial instability. Its impact depends on deposit growth, credit demand and the RBI's other monetary policy measures.
For example, a CRR reduction may increase banking-system liquidity without immediately increasing home loan approvals.
Show more
Show less
What happens when the CRR increases?
When the RBI raises CRR, banks must maintain a larger reserve against the same level of relevant liabilities.
Consider a bank with NDTL of Rs. 2,000 crore.
| CRR rate | Required reserve |
| 3.00% | Rs. 60 crore |
| 3.50% | Rs. 70 crore |
| Additional reserves required | Rs. 10 crore |
The bank would need Rs. 10 crore more in reserves under this simplified example. This can reduce the funds available for other uses, all else being equal. However, it does not mean the bank must immediately reduce outstanding loans by Rs. 10 crore.
Banks can respond through their liquidity management, deposit funding and other balance-sheet decisions. The effect on credit availability and lending rates is indirect.
Show more
Show less
What happens when the CRR decreases?
A lower CRR reduces the amount a bank must maintain against the same level of relevant liabilities.
Using the previous example, reducing CRR from 3.50% to 3.00% would release Rs. 10 crore from the calculated reserve requirement.
| Particulars | Amount |
| Required reserve at 3.50% | Rs. 70 crore |
| Required reserve at 3.00% | Rs. 60 crore |
| Reduction in required reserves | Rs. 10 crore |
This can provide the bank with additional liquidity. The funds could support lending or other permitted banking activities, depending on its financial position and market conditions. However, a lower CRR does not require a bank to lend the released amount immediately.
Customer demand, credit assessment, funding conditions and other regulatory requirements continue to influence lending decisions.
Show more
Show less
What is the difference between CRR and SLR?
CRR and the statutory liquidity ratio (SLR) are both regulatory requirements, but they concern different reserve arrangements.
| Feature | CRR | SLR |
| Full form | Cash reserve ratio | Statutory liquidity ratio |
| Main requirement | Prescribed cash balance with RBI | Prescribed holdings of eligible liquid assets |
| Relevant assets | Reserve balances maintained with RBI | Eligible assets such as cash, gold and approved securities |
| Primary framework | RBI Act and applicable directions | Banking Regulation Act and applicable directions |
| Current published ratio | 3.00% | 18.00% |
| Main purpose | Monetary and banking-system liquidity management | Liquid-asset requirement for regulated banks |
The assets used for meeting the requirements are subject to RBI rules. A bank cannot simply count the same asset towards both requirements without meeting the relevant regulatory provisions.
For borrowers, neither CRR nor SLR is an interest rate charged on a home loan.
Show more
Show less
How is CRR different from the repo rate?
CRR determines how much of a bank's relevant liabilities must be maintained as reserves. The repo rate is the policy rate associated with the RBI's liquidity operations with eligible counterparties.
| Factor | CRR | Repo rate |
| Expressed as | Percentage of relevant liabilities | Annual policy interest rate |
| Main mechanism | Reserve requirement | Cost and pricing of central bank liquidity |
| Immediate bank effect | Changes required reserve balances | Influences funding and monetary market rates |
| Directly sets home loan EMI? | No | No |
| Potential influence on lending | Through liquidity conditions | Through funding costs and rate transmission |
For example, an increase in the repo rate may influence benchmark-linked floating loan rates under the applicable reset mechanism.
A CRR change primarily alters reserve requirements and system liquidity. Although the two tools can affect financial conditions, their effects are not identical.
Show more
Show less
Does CRR affect home loan interest rates?
CRR can influence the broader funding environment, but it does not directly set a customer's home loan interest rate. A lower CRR may increase liquidity and reduce funding pressure in some circumstances, while a higher CRR can have the opposite effect.
However, individual home loan pricing depends on several factors, including the lender's pricing framework, the applicable benchmark and the borrower's financial profile. For example, a customer with a repo-linked floating-rate home loan should examine the benchmark, spread and contractual reset provisions.
A CRR reduction alone does not create a contractual right to an interest-rate reduction. Similarly, an existing fixed-rate loan generally follows its agreed terms unless a permitted change applies.
Show more
Show less
Will a CRR cut reduce your existing home loan EMI?
Not automatically, your EMI changes according to the loan's interest rate and repayment provisions, not simply because the RBI announces a lower CRR.
Consider the following possible situations:
| Loan situation | What determines the impact |
| Floating-rate loan | Applicable benchmark, spread and reset conditions |
| Fixed-rate loan | Contractual fixed-rate period and permitted changes |
| New home loan application | Lender's offered rate and eligibility assessment |
| Existing loan balance transfer | New offer, switching costs and remaining tenure |
Example: Understanding the effect of a rate change
Suppose a borrower has a home loan balance of Rs. 40 lakh with 20 years remaining. The following amounts illustrate the effect of two different loan interest rates, not a direct CRR adjustment.
| Interest rate | Approximate EMI |
| 8.00% p.a. | Rs. 33,458 |
| 7.50% p.a. | Rs. 32,224 |
| Illustrative difference | Rs. 1,234 per month |
These figures assume the interest rate remains constant over the entire remaining period. A CRR cut does not automatically cause the assumed reduction from 8% to 7.50%.
The example simply demonstrates why the borrower's actual loan interest rate matters more for EMI calculations.
Show more
Show less
Do CRR requirements apply to every lender?
The CRR framework does not apply identically to every institution offering finance. Scheduled commercial banks have statutory CRR obligations under the relevant RBI framework, while other categories of banks can be subject to specific legal and regulatory provisions. Non-banking financial companies (NBFCs) are not generally required to maintain CRR in the same manner as scheduled commercial banks.
This distinction is important for customers comparing home loan lenders. An NBFC may still face changes in market funding costs and monetary conditions, even without directly maintaining scheduled-bank CRR reserves.
Therefore, changes in CRR can influence the financial environment more broadly, but the regulatory mechanism varies by institution.
Show more
Show less
How can borrowers use CRR information?
CRR is useful for understanding RBI policy decisions, but it should not be the only factor in choosing a home loan. A borrower should focus on the actual terms offered.
Before accepting a home loan, compare:
- Annual interest rate and applicable benchmark.
- Fixed or floating-rate structure.
- EMI and total interest across the proposed tenure.
- Processing and other disclosed charges.
- Rate-reset provisions.
- Permitted part-prepayment and foreclosure conditions.
- Eligibility and property documentation requirements.
For example, two lenders may offer different rates even when they operate under the same broad monetary conditions. The difference may arise from lender policies, borrower risk assessment and other pricing factors.
Comparing the actual loan offer is therefore more useful than predicting an EMI from a CRR announcement.
Show more
Show less
How can Bajaj Finance help you plan a home loan?
If you are buying a residential property, start with your borrowing capacity, available savings and preferred EMI. Bajaj Finance Home Loan offers financing for eligible residential property purchases, subject to borrower eligibility and property assessment.
For example, a buyer considering a Rs. 40 lakh home loan should compare repayments across interest rates and tenures rather than assuming a change in CRR will produce a particular offer.
Use the home loan EMI calculator to evaluate repayment scenarios. You can also review home loan eligibility and documents before applying. Once you have evaluated the full property cost and repayment requirements, check eligibility for Bajaj Finance Home Loan.
Documents required for PMAY-G
Keep the following documents ready before applying. Requirements differ slightly for salaried and self-employed applicants.
| Applicant type | Documents required |
|---|---|
| Salaried | Aadhaar card, PAN card, voter ID, caste certificate, income certificate, permanent address proof, 6-month bank statement, Form 16 or IT assessment order, construction agreement, advance receipt, affidavit of no permanent house anywhere in India, NOC from housing society or competent authority |
| Self-employed / others | Aadhaar card, voter ID, PAN card, driving licence, caste certificate, income certificate, Form 16, business registration documents, 6-month bank statement, construction plan, advance payment details, allotment letter or property agreement, affidavit of no permanent house anywhere in India |
How to apply for PMAY-G
Beneficiaries are primarily identified through SECC data. However, eligible applicants can also register directly. You can apply both online and offline.
Online application
- Visit the official PMAY-G website at https://pmayg.nic.in/.
- Enter your personal details — gender, mobile number, and Aadhaar number.
- Click 'Search' to find your beneficiary name, PMAY ID, and priority status.
- Click 'Select to Register'. Your beneficiary details will be auto-generated.
- Verify the auto-filled details and complete remaining fields — ownership type, Aadhaar, etc.
- Enter your name and bank account details in the beneficiary section.
- If you need a loan, select 'Yes' and enter the desired loan amount.
- Enter your MGNREGA job card number and Swachh Bharat Mission number.
- Submit the form. Your registration number will be displayed on screen.
Offline application
If you prefer in-person assistance or do not have internet access, you can apply at a Common Service Centre (CSC) near you.
- Visit your nearest Common Service Centre (CSC).
- Request the PMAY application form and fill in your personal, income, and housing details.
- Submit the required documents along with the completed form.
- Pay the nominal CSC application fee as guided by the operator.
- Collect your application number to track your status on the official PMAY portal later.
PMAY-G helpline and support
If you need help with any step of the PMAY-G process — from checking your name in the list to resolving payment issues — the following helplines are available:
| Service | Helpline number | Email address |
|---|---|---|
| PMAY-G | Toll-Free: 1800-11-6446 | support-pmayg@gov.in |
| PFMS (Payment tracking) | Toll-Free: 1800-11-8111 | helpdesk-pfms@gov.in |
Frequently Asked Questions
CRR basics
Banking and home loans
What is the full form of CRR in banking?
CRR stands for cash reserve ratio. It is the prescribed percentage of a bank's relevant net demand and time liabilities that must be maintained as cash balances with the Reserve Bank of India. For scheduled commercial banks, Section 42 of the RBI Act provides the main statutory framework. The RBI changes the requirement according to monetary conditions. CRR is a bank-level requirement and is not an amount separately deducted from an individual customer's deposit.
What is the current CRR rate in India?
The RBI's published current CRR is 3.00% as of 2 November 2026. This means that a bank subject to the requirement must maintain the prescribed proportion of its relevant net demand and time liabilities as reserves, following RBI's calculation and maintenance rules. The percentage may change after a policy decision. For the latest figure, check the RBI's official current-rates page rather than relying on an older article.
How does the RBI calculate CRR?
The required amount is calculated by multiplying the applicable CRR percentage by the bank's relevant net demand and time liabilities. For example, NDTL of Rs. 1,000 crore at a 3% CRR produces a basic reserve requirement of Rs. 30 crore. Actual regulatory compliance uses prescribed reference dates, balance-maintenance rules and reporting procedures. NDTL is not always identical to the bank's total deposits because specified adjustments apply.
Does a lower CRR reduce home loan interest rates?
Not necessarily. A lower CRR can increase banking-system liquidity, which may influence funding conditions. However, individual home loan rates are determined by the lender's pricing policies and the applicable loan terms. Existing floating-rate loans follow their benchmark and reset arrangements, while fixed-rate loans follow their contractual conditions. A CRR cut does not guarantee an immediate interest-rate reduction or lower EMI for every borrower.
Does a higher CRR reduce lending?
A higher CRR increases the reserve balance that a bank must maintain against the same level of relevant liabilities. This can reduce the funds available for other banking activities, including potential lending. However, it does not automatically require the bank to cancel existing loans. The actual lending response depends on deposit flows, liquidity management, credit demand and other financial conditions. CRR is one of several tools used by the RBI.
Is CRR applicable to Bajaj Finance?
CRR requirements for scheduled commercial banks do not generally apply to non-banking financial companies in the same way. Bajaj Finance is an NBFC, so customers should not assume that the bank-level CRR calculation directly determines its home loan interest rates. Monetary policy may nevertheless affect broader funding conditions. The relevant borrowing terms are those disclosed in the actual Bajaj Finance Home Loan offer, including the rate, tenure and applicable conditions.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
Home loan for professionals
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on 04 Mar 2025
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on 24 Feb 2025
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on 12 Apr 2025
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on 08 Dec 2024
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles to Read
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.