What is a gold loan?
A gold loan is a secured loan where you pledge eligible gold jewellery, ornaments or accepted gold coins as collateral to borrow funds without selling your gold. The lender assesses the purity, net weight and applicable gold value to determine the eligible loan amount and applies the relevant LTV ratio. You repay the loan through the agreed repayment option along with applicable interest and charges. Once the outstanding dues are cleared, your pledged gold is returned. Gold loans can be used to meet various financial needs, including medical expenses, education, or personal expenses.
Additionally, facilities like attractive gold loan rate per gram, minimal documentation, multiple repayment tenures and hassle-free disbursal, makes gold loans a reliable source of quick finance from Rs. 5,000 to Rs. 2 crore.
Quick tip: Do not let your jewellery sit idle—tap into its value with a gold loan that suits your needs. Check your gold loan eligibility today!
How does a gold loan work?
A loan against gold is a unique credit option because of its working principle. Here is how gold loan works:
Step 1: Online application
To apply for a gold loan, you just need to fill out an online application form. You need to provide all the necessary details in the form and submit. Or if it suits you better, you can also visit the nearest gold loan branch to avail of the loan offline.
Step 2: Evaluation of gold
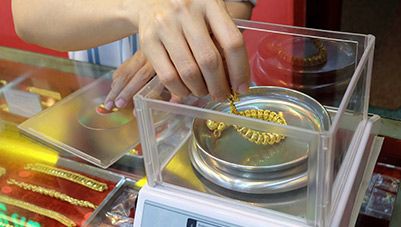
This is where the gold loan process is different from that of other financial products. After applying for credit, the gold pledged as collateral will be evaluated using the state-of-the-art karat metres to assess its purity and weight, considering the applicable gold price. Bajaj Finance considers lower between the previous day's closing price or the 30-day average closing price published by IBJA or a SEBI-regulated commodity exchange. This protects you from a sudden price spike inflating things unrealistically and protects the lender from the opposite. Based on this evaluation, we determine the exact loan amount that an individual is eligible for.
Step 3: RBI cap on LTV for gold loans
Here, you must note that RBI has capped the LTV ratio of a gold loan up to 85%. Lenders extend the loan amount to the applicant based on the evaluation and price of pledged gold. Currently, Bajaj Finance only accepts gold jewellery or ornaments worth 18-22 karat and gold coins up to 24 karat purity as a collateral against the loan. In this regard, you can use a gold loan calculator beforehand to assess repayment liability. This online tool displays accurate results within seconds and allows you to plan and manage your finances efficiently. The maximum LTV eligible for a loan depends on the loan amount and cannot be more than the limits given. To know more, click here.
Step 4: Eligibility and documentation
The next step on how this credit facility works is the eligibility and documentation. Being a secured credit option, gold loans do not impose strict eligibility and documentation. However, you need to be an Indian citizen, aged between 21 to 80 years, to avail of this loan. You would also need to provide your basic KYC documents for gold loan to complete the verification process.
Step 5: Credit approval
After evaluating gold articles, documentation and signing of a loan agreement, the credit disbursal process begins. Finally, borrowers will receive their desired loan amount into their registered account. The entire gold loan process from application to disbursal often takes just one branch visit to complete and ensures a hassle-free loan procedure.
Curious about your loan eligibility? Enter your mobile number to see how much you can get for your gold.
What is the interest rate on which lenders give the gold loan?
The interest rate on a gold loan depends on the lender, the loan amount, and the repayment terms. For Bajaj Finance Gold Loan, the interest rate usually starts from as low as 9.50% to 24.25% per annum, but it can vary based on the gold’s purity, loan-to-value ratio, and repayment schedule chosen by the borrower.
These loans generally have lower gold loan interest rate compared to unsecured loans because your gold acts as security. Since lenders have the gold as collateral, they take less risk, which helps in offering better rates. With Bajaj Finance, you also get multiple repayment options, like paying interest regularly and the principal at the end of the tenure. The gold loan interest rate depends largely on:
- Purity and net weight of your gold
- Market price of gold
- Loan amount and chosen tenure
To know the exact rate applicable to your requirement, you can check your gold loan eligibility online or visit the nearest Bajaj Finance Gold Loan branch.
How is gold loan interest calculated?
When you take a gold loan with Bajaj Finance, the interest is calculated based on the loan amount, applicable interest rate, and chosen repayment tenure. Since gold loans are secured by eligible gold, they generally offer lower interest rates than many unsecured loans. You can also use the gold loan calculator to estimate your interest payable and repayment amount before applying.
For example, if the value of the collateral is Rs. 2 lakh and the applicable LTV is 85% for exposure below Rs. 2.5 lakh, at 24% annual interest on 22 Karat gold and gold rate (as per carat) considered Rs. 13,200 — the total eligible loan amount (including interest) is Rs. 1.70 lakh
- For 12 months tenure, interest is Rs. 32,880
- For 6 months tenure, interest is Rs. 16,440
- For 3 months tenure, interest becomes Rs. 8,220
The actual interest payable may vary depending on your repayment option, loan tenure, and the applicable gold rate. Understanding this calculation helps you plan your repayments and manage your borrowing more effectively.
Repayment options for a gold loan
Bajaj Finance offers multiple repayment options for gold loans, making it easy for you to manage payments:
- Bullet repayment: Pay the principal amount at the end of the loan tenure, on the maturity date.
- Regular repayment: Repay the loan as per the agreed schedule, such as monthly, bi-monthly, quarterly or half-yearly.
- Partial prepayment or foreclosure: Allows early repayment without paying any extra charges.
These options give you freedom to choose a plan that fits your financial situation while keeping repayments manageable.
Benefits of availing a gold loan
A gold loan can help you access funds by pledging eligible gold without selling it. With Bajaj Finance, you can choose features designed to make borrowing and repayment easier.
- Access funds conveniently: Borrow from Rs. 5,000 up to Rs. 2 crore, subject to eligibility and applicable terms.
- Choose repayment options: Pay interest monthly, bi-monthly, quarterly, half-yearly or annually, as applicable.
- Keep your gold: Your pledged gold remains yours and is stored securely with complimentary insurance during the loan tenure.
- Repay early if needed: Bajaj Finance allows full or part prepayment without additional prepayment charges.
- Use part-release: Repay part of the loan and release a portion of your pledged before the tenure ends, subject to eligibility.
Overall, a gold loan is a safe, fast, and convenient way to meet financial needs without selling your jewellery.
What type of gold jewellery can you submit as collateral?
With Bajaj Finance, you can pledge eligible gold jewellery, ornaments and coins as collateral for a gold loan. As of now, gold bars, idols, utensils and gold-plated items are not accepted.
| Gold type | Accepted as collateral? |
|---|
| 18-22 karat gold jewellery | Yes |
| 18-22 karat gold ornaments | Yes |
| Gold coins up to 24 karat purity | Yes |
| Gold bars | No |
| Gold idols | No |
| Gold utensils | No |
| Gold-plated items | No |
It is important to know that only the intrinsic gold value is considered during valuation; stones, gemstones and other non-gold components are excluded.
Pro tip: Check your gold loan eligibility to find out how much you may be able to borrow against your eligible gold jewellery.
Are 'gold loan settlements' paid at maturity or can they be refinanced earlier?
A gold loan settlement is an arrangement between the borrower and lender to close an outstanding Gold Loan by paying an agreed settlement amount, usually when the borrower is unable to repay the loan as originally scheduled. Understanding how gold loan works helps you decide whether to repay your loan at maturity or opt for renewal before it ends.
The available option depends on your lender's policy, your loan status, and applicable regulatory guidelines.
- Repayment at maturity: You can repay the outstanding principal along with any pending interest by the loan maturity date and retrieve your pledged gold.
- Renewal/refinancing: Some lenders allow eligible borrowers to renew or refinance their gold loan before maturity, subject to applicable LTV limits, credit assessment, and lender policy. Fresh charges may apply.
- After maturity: Renewal or refinancing is generally not permitted once the loan has matured.
- Plan ahead: Reviewing your repayment options before the due date can help you avoid delays and additional charges.
How does gold loan work as a financial emergency tool?
When unexpected expenses arise, understanding how does gold loan work can help you access funds quickly without selling your gold. Since a gold loan is secured against eligible gold jewellery, the approval process is usually faster than many unsecured loans and requires only basic KYC documentation.
- Quick disbursal: After your gold is evaluated and documents are verified, the loan is often processed within a single branch visit.
- Minimal paperwork: Basic KYC documents are generally sufficient, making the process simple.
- Immediate financial support: The funds can be used for medical emergencies, education, business needs, or other urgent expenses.
- Retain ownership: Your pledged gold is returned once the loan is repaid in full, allowing you to meet emergency needs without permanently parting with your valuables.