
Is 700 a Good Credit Score, or Bad?

Is 700 a Good Credit Score, or Bad?

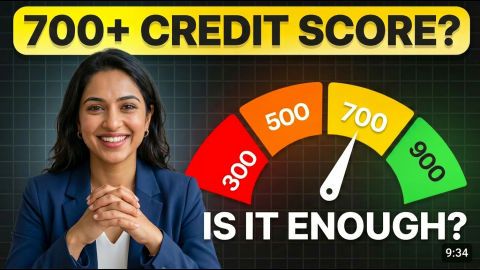
A 700 credit score is generally considered good and signals reliable creditworthiness to lenders. It can improve your chances of loan approval and help you access more competitive interest rates.

Rs. 40,000 - Rs. 55 lakh

You may be eligible for a pre-approved offer

Enter mobile number and OTP | Check free credit score


Key takeaways


Wondering if 700 is a good credit score? Yes, a score of 700 is generally considered good and reflects responsible credit behaviour to most lenders.


  • A 700 credit score typically supports eligibility for personal loans and credit cards, though lender criteria vary.
  • It can help you access reasonable interest rates, though the lowest rates are usually reserved for higher scorers.
  • Credit limits depend on income, existing obligations and each lender's policy, not on score alone.
  • A score of 750 and above may offer stronger terms and wider options than 700.

A 700 score is a positive starting point, but maintaining timely repayments and responsible credit use can help strengthen your credit profile over time.

A 700 credit score is generally considered a good credit score and indicates a relatively healthy credit profile. It can support your eligibility for personal loans, credit cards and other forms of credit, although approval depends on the lender’s criteria.


Your credit score is only one factor lenders consider. They may also assess your income, employment, existing debt, repayment history, credit utilisation and recent credit applications. A higher score may provide access to a wider range of credit options or more favourable terms, depending on the lender.


If your score is 700, maintaining timely repayments and responsible credit usage can help you build a stronger credit profile over time.

Show More Show Less

Is a 700 credit score good or bad?

Whether a 700 credit score is good or bad is a common question, and the answer is that 700 is generally considered a good CIBIL Score. It sits in the range most lenders view favourably, indicating responsible credit management, though approval, interest rates, and product eligibility vary by lender and are not guaranteed.
 

Credit score rangeCategoryGeneral lending implication
300–549PoorLoan applications are likely to be rejected
550–649FairLimited options, usually at higher interest
650–699AverageSome approval chances at moderate rates
700–749GoodMost loans accessible, though rates are not the lowest
750–799Very goodAccess to better rates and terms
800–900ExcellentStrongest rates and premium products
Show More Show Less

How to improve your credit score to more than 700?

Improving your credit score above 700 requires consistent and responsible financial behaviour. Here are some strategies to help boost your score:

  • Timely payments: Always pay your bills on time. Payment history is the most significant factor in your credit score. Even a single late payment can have a substantial negative impact.
  • Reduce credit utilisation: Aim to keep your credit utilisation ratio below 30%. This means if you have a credit limit of Rs. 100,000, you should try to keep your outstanding balance below Rs. 30,000.
  • Avoid opening new accounts frequently: Each time you apply for new credit, it results in a hard inquiry on your credit report, which can temporarily lower your score. Limit new credit applications and only apply when necessary.
  • Keep old accounts open: The length of your credit history contributes to your overall score. Keeping older accounts open can positively impact this aspect of your credit profile.
  • Diversify your credit portfolio: Having a mix of different credit types, such as credit cards, instalment loans, and mortgages, can enhance your credit profile.
  • Check your credit report regularly: Regularly review your credit report for inaccuracies and dispute any errors. Mistakes on your credit report can unfairly lower your score. You can check your credit score to stay updated on your progress.
Show More Show Less

What are the benefits of a good credit score above 700?

Improving your credit score can lead to numerous benefits, such as better loan terms, lower interest rates, and higher credit limits. Here’s how you can enhance your credit score to enjoy these advantages:
 

  • Understand credit score factors: Familiarise yourself with the factors that affect your credit score. These include payment history, credit utilisation, length of credit history, types of credit, and recent credit inquiries. For more details, you can explore the factors affecting credit score.
  • Consistent payments: Make consistent, on-time payments for all your credit accounts. This builds a positive payment history, which is crucial for a good credit score.
  • Limit high balances: Avoid carrying high balances on your credit cards. Keeping your credit card balances low relative to your credit limit helps improve your credit utilisation ratio.
  • Set up payment reminders: Use payment reminders or automatic payments to ensure you never miss a due date. This helps in maintaining a flawless payment history.
  • Pay off debt: Work towards paying off your existing debts. Reducing the overall amount of debt you owe can positively impact your credit score.
  • Avoid closing credit accounts: Keep your credit accounts open, especially the oldest ones. Closing accounts can shorten your credit history and negatively affect your score.

By following these strategies, you can improve your credit score and take advantage of the financial benefits that come with a higher score. Consistently monitoring your credit report and making informed financial decisions will help you achieve and maintain a score above 700.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Overview

Approval

What can a credit score of 700 get you?

A credit score of 700 positions you in the "good" credit range, allowing you to access loans and credit cards with more favourable interest rates. Lenders use your credit score to assess your eligibility for financial products and to determine the interest rates you will be offered. You can check if you have a pre-approved loan offer with just your phone number and OTP – no need to visit the branch.

To reach an 800 credit score, ensure you make all payments on time, keep your credit utilisation low, maintain a long credit history, have a variety of credit types, and occasionally apply for new credit lines.

A 650 credit score is considered "fair". While you can still qualify for financial products like mortgages or car loans, you will likely face higher interest rates compared to those with higher scores. 

Yes, a 700 credit score generally qualifies you for most personal loans and credit cards, though final approval and terms depend on income and the lender's criteria.

Your borrowing amount depends on income, existing obligations, and lender policy rather than credit score alone; a 700 score supports eligibility but does not fix a specific limit.

No, a CIBIL score above 700 improves your chances but cannot guarantee loan approval, as lenders also assess income, repayment capacity, and other eligibility factors.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000