
769 CIBIL score: Is it good or bad?

769 CIBIL score: Is it good or bad?

A 769 CIBIL score falls within the 750–900 range and is generally considered excellent. It can support access to favourable loan terms, and you can check your Bajaj Finance personal loan eligibility online.

Rs. 40,000 - Rs. 55 lakh

You may be eligible for a pre-approved offer

Enter mobile number and OTP | Check free credit score


In summary


A 769 CIBIL Score is considered excellent and reflects a strong credit profile. It improves your chances of qualifying for personal loans, home loans, credit cards, and other financial products with competitive terms. However, lenders also evaluate factors such as your repayment history, credit utilisation, existing loan obligations, and the length of your credit history before making a lending decision.


To maintain your 769 CIBIL Score:

  • Pay all loan EMIs and credit card bills on time.
  • Keep your credit utilisation below 30%–40% of your available limit.
  • Avoid applying for several loans or credit cards within a short period.
  • Review your credit report regularly to identify and correct any errors.


Your CIBIL Score reflects how responsibly you manage credit over time. Maintaining a high score can strengthen your financial profile, helping you access higher loan amounts, competitive interest rates, and flexible repayment options whenever you need credit.

How good is a 769 CIBIL Score?

A 769 CIBIL Score is regarded as excellent by most lenders and indicates that you have managed your credit responsibly over time. Borrowers in this range are generally viewed as low-risk, which can improve their chances of accessing credit on favourable terms.


Some of the advantages of a 769 CIBIL score include:


  • Better approval prospects: A strong score can improve your chances of qualifying for loans and credit cards, subject to the lender's assessment.
  • Competitive borrowing terms: Eligible borrowers may receive more favourable interest rates and repayment options.
  • Higher borrowing potential: Depending on your income and repayment capacity, you may qualify for larger loan amounts or higher credit limits.
  • Access to premium financial products: Many lenders reserve premium credit cards and exclusive loan offers for borrowers with excellent credit profiles.


If you have a 769 CIBIL Score, you are already in a strong position when applying for credit. You can check your personal loan eligibility in just two steps to understand how much you may qualify for without affecting your credit score.

Show More Show Less

What else do lenders check beyond your CIBIL Score?

Although a 769 CIBIL Score strengthens your loan application, lenders evaluate your complete financial profile before approving credit.


They generally consider:


  • Repayment history: Consistently paying EMIs and credit card bills on time demonstrates financial discipline.
  • Credit utilisation ratio: Responsible use of available credit indicates effective credit management.
  • Existing financial obligations: Outstanding loans and monthly repayment commitments influence your repayment capacity.
  • Recent credit enquiries: Multiple loan applications within a short period may indicate increased borrowing needs.
  • Length of credit history: A longer history of responsible credit usage helps lenders assess your financial behaviour more confidently.

A high CIBIL Score is an important advantage, but maintaining healthy financial habits across all these factors can further improve your borrowing prospects.

Show More Show Less

How a 769 CIBIL Score affects your personal loan

Your CIBIL score influences several aspects of a personal loan, including eligibility, interest rates, loan amount, and processing time. With a 769 score, you are generally considered a reliable borrower by many lenders.


You may benefit from:


  • Competitive interest rates: Eligible borrowers with excellent scores are more likely to qualify for a personal loan at the lowest interest rates, as a strong CIBIL Score indicates responsible credit behaviour and lower risk for lenders.
  • Higher loan eligibility: Loan amounts depend on your income, repayment capacity, and lender policies, but a strong score supports your application.
  • Quicker processing: A positive credit profile may reduce the need for additional verification, allowing faster processing.
  • Flexible repayment options: Depending on the lender, you may have access to repayment structures that better suit your financial needs.


If you are planning to apply for your first personal loan, a 769 CIBIL score places you in a favourable position. Check your eligibility to understand the loan amount you may qualify for.

Show More Show Less

How a 769 CIBIL Score impacts interest rates

Your CIBIL score is one of the factors lenders use when determining the interest rate for a personal loan. A score of 769 indicates a lower credit risk, which may improve your chances of receiving competitive loan offers.


For example, if two borrowers apply for the same personal loan amount with similar financial profiles, the borrower with a 769 CIBIL score may receive a more favourable interest rate than someone with a lower score. Over the repayment tenure, even a small reduction in interest can lower the total borrowing cost significantly.


Although interest rates vary across lenders, maintaining an excellent credit profile can help you secure better loan terms.

Show More Show Less

CIBIL Score range: What each band means

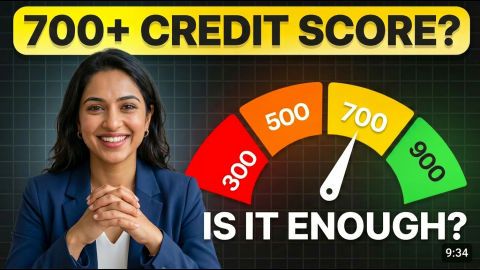
A CIBIL score ranges from 300 to 900, with higher scores indicating stronger creditworthiness. The table below explains how lenders generally interpret different score ranges.
 

CIBIL Score rangeRatingWhat it means
300–549PoorIndicates high credit risk. Loan approval can be difficult, and borrowing options may be limited.
550–649FairShows moderate repayment risk. Loans may be available but often at higher interest rates or with stricter conditions.
650–749GoodReflects responsible credit behaviour and improves the likelihood of loan approval with competitive terms.
750–900ExcellentDemonstrates strong creditworthiness and may improve access to higher loan amounts, competitive interest rates, and faster approvals.

A 769 CIBIL score falls within the 750–900 (Excellent) category. Borrowers in this range are generally considered low-risk and are often well-positioned when applying for credit.

Show More Show Less

How to improve your 769 CIBIL Score

A 769 CIBIL score is already excellent, so the focus of how to improve your CIBIL score from 769 to 800 is on maintaining strong habits rather than fixing problems. Consistent, responsible credit behaviour helps preserve your score and can strengthen it over time.


  • Pay every EMI and credit card bill on time, as payment history has the biggest impact on a 769 credit score
  • Keep credit utilisation on the lower side of your available limit, which reflects controlled borrowing
  • Manage existing debt steadily and avoid letting balances build up
  • Limit frequent loan or credit card applications, since each hard enquiry can temporarily affect your score
  • Check your credit report regularly and report any inaccuracies promptly

A high CIBIL Score is built through consistent financial discipline rather than one-time actions. By following these practices, you can continue to strengthen your credit profile and improve your chances of accessing favourable loan terms whenever you need credit.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Overview

CIBIL score improvement

Is 769 CIBIL score good?

Yes, a 769 CIBIL score is considered excellent on the 300–900 scale. It reflects responsible credit management and can improve your chances of getting loans and credit cards with competitive terms.


No, a 769 credit score is not bad. It falls in the excellent range and indicates strong repayment behaviour, low credit risk, and better chances of accessing favourable borrowing options.

Yes, a 769 CIBIL score can improve your chances of getting a credit card. However, approval depends on factors such as income, existing obligations, and the lender’s eligibility criteria.

A 769 credit score is excellent and not strictly required for loan approval. However, it significantly improves your chances of securing loans with favourable terms, such as lower interest rates and higher limits. You can check your personal loan eligibility using just your mobile number and OTP through a 100% online process.

A 769 CIBIL score can improve your eligibility for higher loan amounts, but the amount you can finance depends on your income, repayment capacity, existing debts, and lender-specific policies.

The lowest CIBIL score usually accepted for a personal loan is around 650. Scores below this may reduce approval chances or lead to higher interest rates.

To improve your score from 769 to 800, keep paying every EMI on time, maintain low credit utilisation, and avoid frequent new credit applications.

Raising a score from 750 to 800 usually takes several months of consistent, responsible credit behaviour, though the exact time varies with your individual credit profile.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000