








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
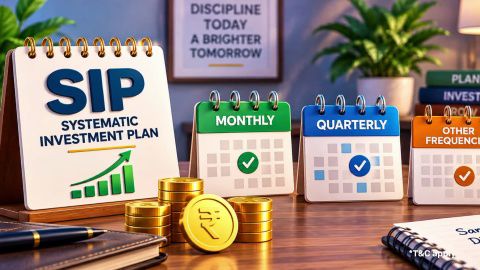
SIP Investing - How to Start, Manage & Optimise Your SIP
In summary
Mutual funds pool money from investors and invest it across assets such as shares and bonds. A fund manager manages the portfolio according to the scheme’s objective, but returns depend on market performance and are not guaranteed.
- You can start an eligible SIP with as little as Rs. 100 per month.
- Mutual funds are not all equally risky; the category and portfolio determine their risk profile.
- A low Net Asset Value (NAV) does not automatically make a fund better value.
- Some schemes have lock-in periods, while many open-ended funds allow redemption subject to applicable conditions.
- Equity Linked Savings Schemes (ELSS) may qualify for tax deductions under Section 80C, subject to eligibility and the chosen tax regime.
Understanding these facts can help you compare schemes more carefully. Check the investment objective, costs, portfolio, tax treatment, and SEBI Riskometer before investing through the Bajaj Broking website.
Myth 1: Mutual funds are only for financial experts
Mutual funds are accessible to investors with different levels of experience. A fund manager makes investment decisions according to the scheme’s objective, so you do not need to select individual shares or bonds yourself.
However, you still need to understand the fund’s strategy, costs, and risks. Start by exploring mutual funds and comparing schemes that match your financial goals.
Myth 2: You need a large amount to start investing
You do not necessarily need a large initial investment. Eligible schemes may allow you to start an SIP with Rs. 100 per month, although minimum amounts vary by scheme and investment option.
An SIP lets you invest a fixed amount regularly. You can use the SIP calculator to estimate how different contributions and investment periods could affect your potential corpus.
Myth 3: All mutual funds carry the same level of risk
Mutual funds have different risk profiles. Equity funds invest mainly in shares, debt funds invest in fixed-income instruments, and hybrid funds combine asset classes. Their risks depend on their holdings, investment strategy, and market conditions.
Check the SEBI Riskometer, which classifies scheme risk from Low to Very High across six levels. It is an indicator, not a guarantee against losses. Diversification can spread exposure, but it cannot eliminate market risk.
Myth 4: Mutual funds are completely tax-free
Mutual fund investments are not automatically tax-free. Tax treatment depends on the type of fund, the date of purchase and sale, the holding period, and the applicable Income Tax rules.
Eligible investments in an Equity-Linked Savings Scheme (ELSS) may qualify for a deduction under Section 80C if you meet the conditions, including those relating to the tax regime. Capital gains may still be taxable. Read about Section 112A of the Income Tax Act and Section 111A of the Income Tax Act for the relevant capital gains rules.
Myth 5: Past returns guarantee future performance
Past performance does not guarantee future returns. A scheme that performed well during one market cycle may perform differently when interest rates, valuations, economic conditions, or investor sentiment change.
Compare performance across multiple periods and against the appropriate benchmark. Also assess the fund’s investment approach, portfolio, expense ratio, and risk level. Avoid choosing a scheme solely because it recently delivered high returns.
Myth 6: SIPs are only suitable for small investors
An SIP can suit investors with different budgets. Regular contributions help you invest systematically, while rupee-cost averaging means your fixed contribution buys more units when prices are lower and fewer when prices are higher.
This does not guarantee a profit or prevent losses. Investors with larger portfolios can also use SIPs to spread investments over time. The contribution amount should reflect your income, financial commitments, and investment horizon.
Myth 7: All mutual funds lock your money away
Many open-ended mutual funds allow you to redeem units on business days, subject to scheme rules and applicable charges. However, some schemes have restrictions. ELSS funds, for example, have a statutory three-year lock-in for each investment instalment.
Check the scheme documents for redemption conditions, settlement timelines, and exit loads. If you may need the money soon, consider whether market-linked investments and their withdrawal conditions suit your needs.
Myth 8: A lower NAV means a cheaper or better fund
A fund’s NAV represents the per-unit value of its net assets. A lower NAV does not mean that the fund is undervalued or offers better returns than a fund with a higher NAV.
For example, investing Rs. 10,000 in a fund with an NAV of Rs. 20 buys more units than investing the same amount at an NAV of Rs. 100. The number of units alone does not determine the value or growth of your investment. Compare the portfolio, costs, strategy, and performance instead.
Myth 9: You must monitor mutual funds every day
Daily monitoring is not necessary for every long-term investor. Frequent price changes can encourage unnecessary decisions, especially when your goals and investment horizon have not changed.
Review your portfolio periodically and when your financial circumstances change. Check whether each scheme still fits your goals, risk tolerance, and overall asset allocation. A fund manager manages the scheme’s portfolio, but you remain responsible for reviewing whether it suits your needs.
Myth 10: You need a demat account to invest in mutual funds
A demat account is not compulsory for every mutual fund investment. You can generally invest in mutual fund schemes through eligible platforms without holding units in a demat account. The process depends on the platform and how you choose to hold your units.
Before investing, complete the required Know Your Customer (KYC) process and review the scheme documents. Understand how the platform records, tracks, and redeems your units.
Myth 11: More funds always mean better diversification
Holding many schemes does not automatically make a portfolio more diversified. Different funds may hold the same companies or invest in similar sectors, increasing overlap without adding much variety.
Review the underlying holdings, categories, and asset allocation of your investments. Choose funds that serve distinct roles in your portfolio rather than adding schemes simply to increase the count. The aim is suitable diversification, not the largest possible number of funds.
How can you compare mutual funds more effectively?
Use the mutual fund calculator to estimate potential investment values. For different contribution approaches, try the lumpsum calculator and step-up SIP calculator.
Conclusion
Mutual fund myths can lead to unsuitable investment decisions, from choosing funds based on NAV alone to assuming that returns are guaranteed. Assess each scheme using its objective, portfolio, costs, tax treatment, and risk level. The Bajaj Broking website can help you explore available schemes, but the final choice should reflect your financial goals and ability to take risk.
Last reviewed: 15 October 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Choosing and managing investments
Costs, records, and regulations
Can I switch from one mutual fund scheme to another without redeeming my investment?
A switch is generally processed as a redemption from one scheme followed by a purchase in another. This may trigger capital gains tax and an exit load, depending on the schemes and applicable rules. Before switching, compare the costs, tax consequences, and reasons for changing your investment rather than focusing only on recent performance.
Should I stop an SIP when the market falls?
A market fall alone does not automatically mean you should stop an SIP. Review whether the scheme still matches your goals, investment horizon, and risk tolerance. Continuing contributions can buy more units at lower prices, but it does not guarantee recovery or profits. Keep enough money for essential expenses before committing to regular investments.
What is the difference between a direct plan and a regular plan?
Both plans invest in the same mutual fund scheme and share its investment objective, but their distribution arrangements differ. A direct plan does not include distributor commission in its expense ratio, while a regular plan does. This can affect net returns over time. Compare the applicable costs and the level of assistance you need before choosing.
Where can I check whether a mutual fund distributor is registered?
You can check the distributor’s registration details and relevant disclosures through the Association of Mutual Funds in India (AMFI). Also review the platform’s role, applicable disclosures, and the scheme’s official documents. Registration does not mean a fund is suitable for every investor, so assess the scheme’s risks and objectives independently.
Does a mutual fund’s rating guarantee that it will perform well?
No. Ratings and rankings summarise selected information using a particular methodology, but they cannot predict future returns. Check the rating provider, date, criteria, and category used for comparison. Combine this information with the scheme’s portfolio, costs, benchmark performance, investment strategy, and SEBI Riskometer rather than treating a rating as a recommendation.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.