








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
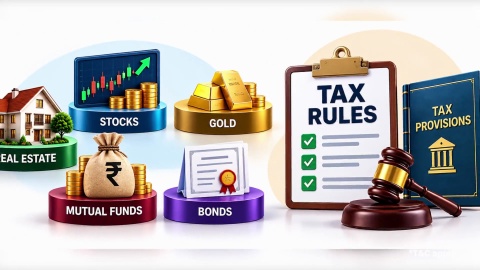
Short term capital gain tax
In summary
Short-term capital gains (STCG) arise when you sell or transfer a capital asset within its applicable short-term holding period at a profit. The tax treatment depends on the asset, transaction, and applicable Income Tax provisions.
- Eligible Section 111A STCG is generally taxed at 20% for transfers covered by current rules.
- Listed equity shares and equity-oriented mutual funds generally have a 12-month short-term holding period.
- Many other capital assets have a 24-month short-term holding period.
- Certain assets are subject to specific rules that can override the usual holding-period test.
- Short-term capital losses can generally be set off against both short-term and long-term capital gains.
- STCG must be reported in the appropriate Income Tax return.
The Bajaj Broking website provides investment-related information, while your actual tax liability depends on the applicable Income Tax provisions and your circumstances.
What is short-term capital gain?
Short-term capital gain is the profit earned when you sell or transfer a capital asset that qualifies as a short-term capital asset under the applicable Income Tax rules.
The holding period used to classify an asset as short-term varies by asset type. Listed equity shares, equity-oriented mutual fund units, and certain business trust units generally have a 12-month threshold. Many other capital assets have a 24-month threshold. Specific provisions can apply to particular assets, so the classification should be checked before calculating tax.
STCG is calculated on the taxable gain rather than simply applying a tax rate to the entire sale value.
What is the STCG tax rate in India?
The applicable tax rate depends on the type of capital asset and the provision under which the gain is taxed.
| Asset | Short-term holding period | General STCG treatment |
|---|---|---|
| Listed equity shares covered by Section 111A | Up to 12 months | 20%, subject to applicable conditions |
| Eligible equity-oriented mutual funds | Up to 12 months | 20%, subject to applicable conditions |
| Certain business trust units | Up to 12 months | 20%, subject to applicable conditions |
| Many other capital assets | Generally up to 24 months | Applicable Income Tax slab rate |
| Assets covered by special provisions | Depends on the provision | Taxed according to the applicable special rule |
The 20% Section 111A rate applies to eligible transfers on or after 23 July 2024, subject to the conditions prescribed under the law. The applicable surcharge and health and education cess may also increase the final tax payable.
Last updated: September 2026
How do you calculate short-term capital gains?
For a straightforward transaction, the taxable capital gain can generally be worked out as:
Capital gain = Sale consideration − Cost of acquisition − Eligible transfer expenses
The applicable rules can require additional adjustments depending on the asset and transaction.
Example of STCG calculation
Suppose Neha buys 500 listed shares at Rs. 400 each and sells them within 12 months at Rs. 460 each. Assume she incurs Rs. 2,000 in eligible transfer-related expenses.
Her calculation would be:
- Purchase cost = 500 × Rs. 400 = Rs. 2,00,000.
- Sale value = 500 × Rs. 460 = Rs. 2,30,000.
- Gain before eligible expenses = Rs. 30,000.
- STCG after eligible expenses = Rs. 28,000.
If the transaction qualifies for Section 111A, the basic tax at 20% would be Rs. 5,600, before applicable surcharge and cess.
This is an illustration only. Your actual tax liability can differ based on your total income, losses, residential status, and other applicable provisions.
How is STCG taxed for different assets?
The tax treatment is not the same across asset classes.
Equity shares and equity-oriented mutual funds
Eligible STCG from listed equity shares and equity-oriented mutual funds covered by Section 111A is generally taxed at 20%, provided the statutory conditions are met. These include conditions relating to Securities Transaction Tax in applicable cases.
Property and other assets
STCG from assets that are not covered by a special rate is generally added to taxable income and taxed at the applicable slab rate.
Therefore, the tax payable can differ substantially between taxpayers even when they earn the same amount of STCG.
Specified mutual funds
Certain mutual funds acquired on or after 1 April 2023 can be subject to Section 50AA. Where that provision applies, the gains are treated as short-term capital gains regardless of the actual holding period and are taxed under the applicable provisions.
This means you should not assume that every mutual fund follows the same 12-month rule.
Can short-term capital losses reduce your tax?
Yes. Subject to the applicable rules, a short-term capital loss can generally be set off against both short-term and long-term capital gains.
If an eligible loss cannot be fully adjusted in the same year, it may generally be carried forward for up to eight assessment years, subject to conditions such as timely filing of the relevant Income Tax return.
Keeping accurate purchase and sale records is therefore important, particularly if you have transactions across multiple asset classes.
Can the basic exemption limit apply to STCG?
For a resident individual or HUF, the unused portion of the basic exemption limit may, subject to applicable conditions, be adjusted against certain capital gains, including eligible gains covered by special-rate provisions.
This should not be confused with the Rs. 1.25 lakh annual threshold applicable to certain long-term capital gains under Section 112A. That threshold does not make eligible Section 111A STCG tax-free.
The treatment also depends on the taxpayer's residential status and the nature of the gain.
Are there exemptions for short-term capital gains?
Most STCG does not qualify for the broad reinvestment exemptions available for certain long-term gains. However, specific provisions can provide relief in limited circumstances.
For example, Sections 54B and 54D can provide relief for qualifying gains from agricultural land and certain industrial land or buildings, respectively, when the prescribed conditions and reinvestment requirements are satisfied.
These provisions are asset-specific. You should therefore check the exact conditions before assuming that a particular exemption applies.
How do you report STCG in your Income Tax return?
Taxable capital gains must be reported in the appropriate Income Tax return and relevant capital-gains schedules.
For AY 2026–27, ITR-1 cannot be used by an individual who has short-term capital gains. ITR-2 is generally applicable to individuals and HUFs who do not have income from business or profession and are not eligible for ITR-1. ITR-3 applies where business or professional income is involved, subject to the applicable conditions.
Capital gains are reported through the relevant capital-gains schedules, with transaction details classified according to the applicable rules.
Keep contract notes, purchase records, sale records, transaction statements, and details of eligible expenses to support your calculation.
Can you reduce short-term capital gains tax legally?
You cannot simply eliminate a tax liability when the law requires tax to be paid. However, legitimate tax planning can help you calculate and manage the liability correctly.
Track your holding periods
The acquisition and transfer dates can determine whether a gain is short-term or long-term. Before selling, check the holding-period rule applicable to that particular asset.
Use eligible capital losses
Where appropriate, eligible capital losses can offset capital gains under the applicable set-off provisions. Tax-loss harvesting should not be treated as a reason to sell an investment that otherwise remains suitable for your objectives.
Check specific exemptions
If your transaction involves an asset covered by a specific exemption, check the qualifying conditions, reinvestment requirement, and prescribed timelines before relying on the relief.
What is the difference between STCG and LTCG?
STCG and long-term capital gains (LTCG) are classifications based on the applicable holding period. The distinction can affect the tax rate, available exemptions, and treatment of losses.
For example, eligible equity-oriented investments generally become long-term after more than 12 months. The applicable LTCG rules are then different from those for Section 111A STCG.
The tax outcome should not be the only consideration when deciding when to sell. Your investment objective, liquidity needs, risk exposure, and financial circumstances also matter.
Conclusion
Short-term capital gains tax depends on the asset, holding period, applicable tax provision, and your overall tax position. Eligible Section 111A gains are generally taxed at 20%, while many other STCGs are taxed at applicable slab rates. Accurate classification, transaction records, loss adjustments, and correct Income Tax return reporting can help you calculate your liability properly.
Last reviewed: September 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Understanding STCG taxation
Managing short-term capital gains tax
Filing STCG in your income-tax return
How much short-term capital gain is taxable?
Taxable STCG generally includes your net short-term capital gains after permitted loss adjustments. The applicable rate depends on the asset and relevant capital-gains provisions.
Is capital gains tax calculated at 12.5% or 20?
It depends on the gain. Qualifying STCG under Section 111A is generally taxed at 20%, while qualifying long-term capital gains are generally taxed at 12.5%.
Is ITR 1 or 2 for short term capital gains
ITR-2 generally applies to individuals or HUFs with capital gains and no business or professional income. ITR-1 does not cover capital gains reporting.
What is the tax rate on Short-Term Capital Gains?
Qualifying STCG on specified listed equity and equity-oriented funds is generally taxed at 20%. Other short-term gains are usually taxed at applicable income-tax rates.
Do I need to pay STCG and income tax both?
No. STCG forms part of your taxable income but may be taxed at a special capital-gains rate. You do not pay tax twice on the same gain.
How can I reduce or minimise short term capital gains tax?
You may reduce taxable STCG by setting off eligible capital losses, planning sale timing, and using permitted exemptions where applicable. Tax treatment depends on the asset.
Can short-term capital losses be adjusted against long-term capital gains?
Yes. Short-term capital losses can generally be set off against both short-term and long-term capital gains under Indian income-tax rules.
How does the holding period determine whether a mutual fund gain is short-term?
The holding period depends on fund type. Equity-oriented funds generally become long-term after 12 months, while other funds can follow different rules, including Section 50AA.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.