








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
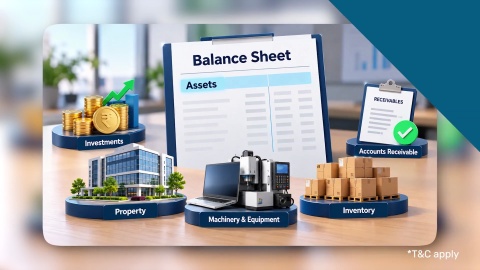
Read a Balance Sheet Like a Pro
In summary
Assets and liabilities are two fundamental elements of financial position. Assets represent resources controlled by a business or individual that can provide future economic benefits. Liabilities represent obligations that require settlement through cash, goods, services, or other resources.
- Assets can include cash, investments, property, inventory, and receivables.
- Liabilities can include loans, payables, taxes, leases, and other obligations.
- Current items are generally expected to be realised or settled within 12 months.
- Non-current assets and liabilities generally extend beyond the short-term period.
- Net worth or equity reflects the difference between assets and liabilities.
- Financial ratios help assess liquidity, leverage, efficiency, and financial stability.
The relationship between these items is captured by the accounting equation: Assets = Liabilities + Equity.
What are assets?
An asset is a resource with economic value that a business or individual owns or controls and expects to provide a future benefit. Assets can support operations, generate revenue, preserve value, or be converted into cash.
Common examples include cash, investments, property, machinery, inventory, accounts receivable, patents, trademarks, and goodwill.
For a business, assets are not limited to physical property. Investments and intellectual property can also be significant resources. Depending on their nature and expected use, assets can be classified in several ways.
What are the main types of assets?
- Current assets: Resources expected to be realised, sold, or consumed within one year or the normal operating cycle. Current assets include cash, inventory, receivables, and short-term investments.
- Non-current assets: Resources held for longer-term use or benefit. Non-current assets include property, machinery, long-term investments, and certain intangible assets.
- Tangible assets: Physical resources such as buildings, equipment, inventory, and vehicles.
- Intangible assets: Non-physical resources such as patents, trademarks, copyrights, goodwill, and brands.
- Operating assets: Resources used directly in day-to-day business activities.
- Non-operating assets: Resources that are not essential to core operations, such as surplus property or certain investments.
What are liabilities?
A liability is a present financial obligation that a business or individual is required to settle. Settlement may involve payment of cash, transfer of another asset, provision of services, or another form of economic outflow.
Common liabilities include loans, accounts payable, accrued expenses, taxes payable, leases, bonds, and deferred tax liabilities.
Liabilities are not necessarily negative in themselves. Borrowing can help a business acquire productive assets or fund expansion. The key consideration is whether the obligation remains manageable relative to the organisation's cash flow, assets, and repayment capacity.
What are the main types of liabilities?
- Current liabilities: Obligations generally due within 12 months, such as accounts payable, short-term borrowings, accrued expenses, and taxes payable.
- Non-current liabilities: Obligations extending beyond 12 months, including long-term loans, bonds, leases, and certain deferred tax liabilities.
- Contingent liabilities: Potential obligations that depend on the outcome of uncertain future events, such as certain legal claims or warranty-related obligations.
Contingent liabilities require careful assessment because their timing and amount may not be known with certainty. Their accounting treatment depends on the applicable reporting framework. Generally accepted accounting principles provide a broader accounting framework for financial reporting.
How do assets and liabilities differ?
The distinction is easiest to understand by considering ownership, economic benefit, and financial obligation.
| Feature | Assets | Liabilities |
|---|---|---|
| Meaning | Resources with economic value | Financial obligations |
| Examples | Cash, property, inventory, investments | Loans, payables, leases, taxes payable |
| Expected effect | Can provide future economic benefits | Requires future settlement |
| Balance sheet | Reported as assets | Reported as liabilities |
| Effect on net worth | Generally increases net assets | Generally reduces net assets |
| Main management focus | Utilisation, valuation, and returns | Repayment, cost, and risk |
Last updated: October 2026
The two categories work together rather than existing independently. For example, borrowing Rs. 20 lakh to purchase machinery increases both assets and liabilities by Rs. 20 lakh at the initial transaction stage.
What is the relationship between assets, liabilities, and equity?
The fundamental accounting equation is:
Assets = Liabilities + Equity
Rearranging it gives:
Equity = Assets − Liabilities
Equity therefore represents the residual interest after liabilities are deducted from assets. For a company, this is generally associated with shareholders' equity. For an individual, the equivalent concept is commonly discussed as net worth.
For example, if a business has assets worth Rs. 80 lakh and liabilities of Rs. 50 lakh:
Equity = Rs. 80 lakh − Rs. 50 lakh = Rs. 30 lakh
A positive residual does not automatically mean the business is financially strong. The composition, liquidity, profitability, and quality of assets also matter.
How do assets and liabilities affect financial health?
The balance between assets and liabilities influences liquidity, solvency, operational flexibility, and financial risk.
A company may have substantial assets but still face cash-flow pressure if most of those assets are difficult to convert into cash. Similarly, a business with manageable total liabilities can face difficulties if a large proportion becomes payable in the short term.
When analysing financial position, consider:
- Liquidity: Whether sufficient liquid assets are available to meet near-term obligations.
- Solvency: Whether the business can meet its longer-term financial commitments.
- Leverage: The extent to which debt is used to finance assets.
- Asset efficiency: How effectively assets are used to generate revenue.
- Cash flow: Whether operations generate enough cash to support payments and investment.
You can explore liquidity as a broader financial concept when assessing how quickly resources can be converted into usable funds.
Which financial ratios help analyse assets and liabilities?
Several ratios connect assets and liabilities to different aspects of financial performance.
Current ratio
Current Ratio = Current Assets ÷ Current Liabilities
It measures the extent to which current assets cover current liabilities. A ratio above 1 indicates that current assets exceed current liabilities, but the appropriate level varies by industry and business model.
Quick ratio
The quick ratio provides a stricter liquidity assessment by excluding inventory from the calculation. It is also known as the acid-test ratio.
Debt-to-equity ratio
This compares debt or liabilities with equity and helps assess financial leverage. A higher ratio can indicate greater reliance on borrowed funds and potentially greater exposure to financial risk. Financial risk should therefore be considered alongside profitability and cash-flow strength.
Asset turnover ratio
Asset Turnover Ratio = Net Sales ÷ Average Total Assets
It indicates how effectively a business uses its asset base to generate sales. A higher ratio may indicate greater asset utilisation, although comparisons should generally be made between similar businesses.
Return on assets
Return on Assets, or ROA, assesses how effectively a business generates profit from its asset base. It is a profitability ratio and should be interpreted alongside margins, leverage, and industry characteristics.
How should assets and liabilities be managed?
Effective management involves balancing the need to invest in productive assets with the need to maintain sufficient liquidity and manageable obligations.
A business can improve its financial position by collecting receivables efficiently, managing inventory, reviewing underutilised assets, controlling borrowing costs, and matching the maturity of liabilities with expected cash flows.
For individuals, the same principle applies at a personal-finance level. Investments, savings, and property may form part of assets, while home loans, personal loans, credit card balances, and other outstanding obligations form liabilities.
For example, investing Rs. 10 lakh while carrying Rs. 8 lakh of high-cost debt does not necessarily represent a stronger financial position than holding fewer investments with substantially lower debt. The quality, liquidity, return potential, and cost of each component matter.
How do investments fit into assets?
Investments such as mutual funds can form part of an individual's or business's financial assets. Their value should be assessed using the relevant current valuation rather than simply the original amount invested.
For investors reviewing potential investment values, the mutual fund calculator and lumpsum calculator can help estimate outcomes based on selected assumptions.
For regular investments, the SIP calculator and step-up SIP calculator from Bajaj Finance can help illustrate how contributions may accumulate over time. These are estimates and do not guarantee investment returns.
What should you check before assessing financial strength?
Looking at the total value of assets alone can give an incomplete picture. A more useful assessment considers the quality and liquidity of assets alongside the size, cost, and maturity of liabilities.
Review:
- Asset composition: Determine how much is held in liquid, operating, fixed, and intangible assets.
- Liability maturity: Identify obligations due within 12 months and those falling due later.
- Debt cost: Consider interest rates and repayment requirements.
- Cash generation: Check whether operations generate sufficient cash to service liabilities.
- Asset utilisation: Assess whether major assets are contributing adequately to revenue or strategic objectives.
- Contingent obligations: Consider potential liabilities that may arise from legal, contractual, or other uncertain events.
Conclusion
Assets represent resources with economic value, while liabilities represent obligations requiring settlement. Understanding their composition and relationship helps businesses and individuals assess liquidity, leverage, solvency, net worth, and financial flexibility.
The accounting equation, Assets = Liabilities + Equity, provides the foundation, but meaningful analysis requires more than comparing two totals. Asset quality, liability maturity, cash flow, profitability, and the effective use of resources all influence financial health.
Last reviewed: October 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Accounting treatment
Financial analysis
Personal finance
Is an expense an asset or a liability?
An expense is generally neither an asset nor a liability once it is recognised in the income statement. It represents a cost incurred to generate revenue during a period. However, an unpaid expense can create a liability, while a prepaid expense can initially be recognised as an asset because the business has a future economic benefit.
Can an asset become a liability?
An asset does not normally become a liability simply because its value changes. However, a transaction involving an asset can create a corresponding liability. For example, purchasing machinery using a loan creates an asset and a borrowing obligation. The asset and liability remain separate elements and are accounted for according to applicable standards.
Does a high asset value always indicate a strong business?
No. A large asset base does not necessarily indicate strong financial performance. Assets may be illiquid, underutilised, overvalued, or financed heavily through debt. Analysts therefore examine asset quality, cash generation, profitability, leverage, liquidity, and return measures together rather than relying on total assets alone.
Why can a profitable business still face financial difficulty?
Profit and cash flow measure different aspects of financial performance. A business can report accounting profits while having substantial amounts locked in receivables or inventory. At the same time, significant liabilities may fall due before cash is collected. This mismatch can create liquidity pressure even when the income statement shows a profit.
Is a home loan an asset or a liability?
For the borrower, the outstanding home loan is a liability because it represents an obligation to repay the lender. The property purchased can be an asset if it is owned by the borrower. Therefore, one transaction can create both an asset and a liability, with the borrower's equity representing the difference between them.
How often should assets and liabilities be reviewed?
The appropriate frequency depends on the purpose and circumstances. Businesses typically monitor financial position regularly through accounting and management reporting, while individuals may review their position at least annually and after major changes such as taking a loan, purchasing property, or making significant investments. Regular reviews can help identify changes in liquidity and debt exposure.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.