Gold prices influence the assessed value of pledged gold. A higher applicable benchmark may support a larger eligible loan amount for the same net weight and purity, while a lower benchmark may reduce the eligible amount. However, the loan is not calculated simply using the live retail gold rate displayed by a jeweller. You can also use the gold loan calculator to estimate the interest repayment schedule based on the loan amount, tenure and interest rate.
How is gold loan eligibility calculated?
Your eligible loan amount depends on:
- Gold weight
- Gold purity
- Applicable gold rate on the day of assessment
- Loan-to-Value (LTV) ratio
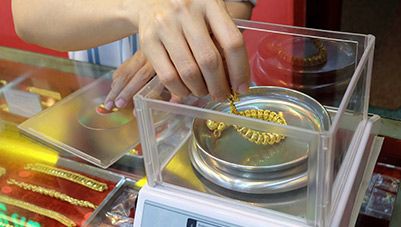
Only the pure gold content is assessed. Stones, enamel, and other decorations on your jewellery are not counted.
The final loan amount depends on the eligible LTV, actual gold purity, and the lower of either the previous day's closing price or the 30-day average closing price published by IBJA or a SEBI-regulated commodity exchange. The LTV ratio must be maintained throughout the loan tenure and may be revised as per RBI guidelines and lender policies.
The loan amount is determined using the applicable LTV ratio, which varies by loan size. To know more, click here.
Gold Loan basics: What you should know before applying
A Bajaj Finance Gold Loan allows you to borrow from Rs. 5,000 to Rs. 2 crore by pledging eligible gold jewellery, ornaments or coins. The applicable gold loan interest rate starts from 9.50% per annum.
Gold jewellery and ornaments with 18-22 purity are accepted as collateral, while gold coins with up to 24 karat purity may also be eligible. The pledged gold is stored in secure vaults and remains insured throughout the loan tenure.
Here are some important points to understand before applying:
- Your eligible loan amount depends on the net weight and actual purity of the pledged gold, not its original purchase price.
- Bajaj Finance uses the lower of the previous day’s closing price or the 30-day average closing price published by IBJA or a SEBI-regulated commodity exchange.
- You need to submit one valid KYC document, such as an Aadhaar card, Voter ID, passport, driving licence, NREGA job card or a letter issued by the National Population Register.
- Under the bullet repayment option, the principal and interest are payable at the end of the loan tenure, while under the regular repayment option, interest can be serviced monthly, every two months, quarterly, half-yearly or annually, with principal repayment as per the agreed schedule.
- Foreclosure charges are nil, allowing you to close the loan before the end of the tenure without an additional foreclosure fee.
- The final loan amount remains subject to the applicable LTV ratio, gold valuation, KYC verification and lender assessment.
Before applying you can also gold loan eligibility online to understand your borrowing capacity based on the eligible gold weight, purity, applicable valuation and LTV ratio.
Ready to unlock the value of your gold? Apply for Bajaj Finance Gold Loan today.