








Know the benefits of a demat account
Free Demat account in minutes | Low brokerage | Online account opening
In summary
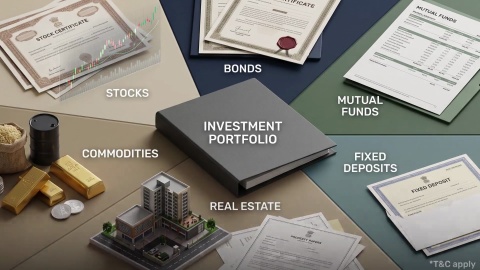
Types Of Investments
Choose an investment based on when you need the money, how much loss you can handle, and how easily you may need to withdraw it.
- Shares give ownership in a company but can move sharply in price.
- Bonds involve lending money to an issuer and carry interest-rate and credit risk.
- Mutual funds pool investors’ money across different assets.
- ETFs trade on stock exchanges and usually follow a defined investment strategy or index.
- Bank and post office deposits generally focus more on capital stability than market-linked growth.
- Gold can diversify a portfolio, but its price still changes.
- Real estate can provide rent or price appreciation but has low liquidity.
- Your goal, time horizon, liquidity need, and risk tolerance should come before expected return.
Which investment type should you look at first?
Start with the time when you will need the money.
Suppose Ramesh is a 38-year-old electrician in Nashik. He has three different money needs:
- ₹50,000 for school fees after 8 months
- ₹3 lakh for a house-related expense after several years
- Money for retirement many years later
These three amounts should not automatically go into the same type of investment.
Money needed soon requires greater attention to capital stability and liquidity.
Money that can remain invested for many years may be able to handle more short-term market movement, depending on the investor’s risk tolerance.
So before asking, “Which investment gives the highest return?”, ask:
“When will I need this money?”
Current IPO
How do different types of investments work?
Each investment solves a different problem.
| Investment type | How your money works | Main risk |
|---|---|---|
| Bank or post office deposit | Money earns interest under the product terms | Inflation, reinvestment, and applicable product risk |
| Bonds | You lend money to an issuer | Credit, interest-rate, and liquidity risk |
| Shares | You own part of a company | Share price and business can fall |
| Mutual funds and ETFs | Money is invested across a portfolio | Depends on underlying investments |
| Gold | Value changes with gold prices | Market-price fluctuations |
| Real estate | Property can earn rent or appreciate | Low liquidity and property-specific risk |
| Crypto-assets | Digital asset price changes in the market | Very high volatility and regulatory risk |
The table does not mean one option is universally better than another.
The useful question is whether the investment matches your goal, time, and ability to handle losses.
How do shares, bonds, and deposits work with your money?
Shares, bonds, and deposits use your money in very different ways.
How do shares work?
Buying a share means buying part ownership in a company.
Suppose you buy 100 shares at ₹200 each.
Amount invested:
₹200 × 100 = ₹20,000
If the share later trades at ₹250:
Value = ₹250 × 100 = ₹25,000
Your unrealised gain is ₹5,000.
But if the price falls to ₹150:
Value = ₹15,000
Your holding is down ₹5,000.
Shares can also pay dividends, but companies are not required to provide a fixed dividend every year.
How do bonds work?
Buying a bond generally means lending money to a government, company, or another eligible issuer.
In return, the bond may provide interest and repay principal according to its terms.
But bond prices can move before maturity.
A company issuing a bond can also face repayment problems.
So “fixed income” does not mean the market value can never fall.
How do deposits work?
A bank or post office deposit generally provides interest according to the product terms.
Deposits may be useful when capital stability and a known maturity period matter more than market-linked growth.
However, check:
- Interest rate
- Lock-in or tenure
- Premature withdrawal conditions
- Tax
- Applicable deposit protection or government backing
Do not compare a deposit and a share only by expected return. Their risks are very different.
Start investing today

Open Demat Account
Open Trading Account

Margin Trading Facility
How do mutual funds and ETFs make investing different?
Mutual funds and ETFs let you invest through a portfolio instead of selecting every security yourself.
A mutual fund collects money from many investors and invests according to the scheme’s stated objective.
It may invest in:
- Shares
- Bonds
- A combination of equity and debt
- Gold
- Other permitted assets
An ETF, or Exchange-Traded Fund, also holds a portfolio but trades on a stock exchange.
The important point is:
The product name does not tell you the risk. The underlying assets do.
For example:
- An equity fund can fall when the stock market falls.
- A debt fund can face interest-rate or credit risk.
- A gold ETF moves with gold prices.
So before investing, check the scheme objective, portfolio, costs, and risk level.
Where do gold and real estate fit?
Gold and property behave differently from shares and bonds, so some investors use them as separate asset classes.
What does gold do?
Gold does not produce business profit like a company share.
Its return mainly comes from changes in the gold price.
You can get exposure through forms such as physical gold or eligible market-linked gold products.
Gold can rise, stay flat, or fall.
Do not treat it as a guaranteed-return investment.
What does real estate do?
Property can produce:
- Rental income
- Capital appreciation
But it also involves:
- Large initial amounts
- Registration and transaction expenses
- Maintenance costs
- Property-specific risk
- Time needed to find a buyer
Upcoming IPO
How should you choose between different investment types?
Use four questions before looking at expected returns.
When will you need the money?
If the money is needed soon, a large market fall just before withdrawal can create a problem.
Longer-term money generally has more time to recover from short-term market fluctuations.
How much loss can you handle?
Do not answer this only emotionally.
Suppose ₹1 lakh falling temporarily to ₹70,000 would make you withdraw immediately.
That tells you something important about your ability to handle market risk.
How quickly might you need cash?
This is liquidity. Shares and many listed securities can usually be sold in the market, though the price may be unfavourable.
Property can take much longer to sell.
Some deposits or bonds may have withdrawal or trading restrictions.
Are you putting everything in one place?
Holding only one company, one property, one sector, or one asset class creates concentration.
Diversification means spreading money across investments that do not all behave in exactly the same way. It reduces concentration risk, but it cannot remove all investment risk.
What should you do before putting money into any investment?
Start with the goal rather than the product.
Use this sequence:
- Write the goal: School fees, home purchase, retirement, or another specific need.
- Fix the time: Decide when the money will be required.
- Keep emergency money separate: Do not depend on a volatile or difficult-to-sell investment for an unexpected expense.
- Check your risk: Understand how much the investment can realistically fall.
- Check liquidity: Find out how quickly you can get your money back.
- Understand the product: Know where your money goes and how the investment earns.
- Check costs and tax: Brokerage, fund expenses, transaction costs, and taxes affect what you keep.
- Use regulated products and intermediaries: Verify registration where applicable.
- Review periodically: Your goal, income, and risk capacity can change.
The practical rule is simple: first decide what the money is for, then choose the type of investment. Do not reverse that order.
Features and Benefits of LAS

Tenure 36 months
Flexible repayment from 7 days to 36 months

1000+ shares
Get 50% value on 1000+ shares

All DP shares available
All companies’ and DPs’ Demat accounts accepted for loans

Customer portal
Handle loans, shares, and statements — all in one place
Conclusion
There is no single investment type that serves every financial goal. Shares offer company ownership but carry market risk. Bonds provide debt exposure but can face credit and interest-rate risk. Mutual funds and ETFs provide portfolio exposure, while deposits, gold, and real estate solve different needs.
The right comparison is not simply “Which gives more return?”
Compare safety, liquidity, risk, time horizon, costs, and your goal before deciding where the money belongs.
Top Investment Options for You
Related Articles
Frequently Asked Questions
Types Of Investments
What are the 3 main investment categories?
How do I choose the right type of investment for me?
Choosing the right type of investment depends on an assessment of your investment goals, time horizon, budget, liquidity needs, and risk tolerance levels.
What are the tax implications of different types of investments?
Tax implications for different investments vary greatly. For instance, investing in stocks and mutual funds attracts a long and short-term capital gains tax depending on the holding period of the asset. Investing in property attracts a property tax, while rental income is taxed as per the individual’s income tax slab.
How do I diversify my investment portfolio effectively?
Effectively diversifying your investment portfolio involves spreading your investment across different asset classes, sectors, and industries. Choosing assets that have a low or negative correlation helps optimally diversify your portfolio and minimise risk exposure.
Disclaimer
Investments in the securities market are subject to market risk, read all related documents carefully before investing.
Broking services offered by Bajaj Financial Securities Limited (Bajaj Broking). Reg Office: Bajaj Auto Limited Complex, Mumbai –Pune Road Akurdi Pune 411035. Corporate Office: Bajaj Financial Securities Limited, 1st Floor, Mantri IT Park, Tower B, Unit No 9 & 10, Viman Nagar, Pune, Maharashtra 411014. SEBI Registration No.: INZ000218931 | BSE Cash/F&O/CDS (Member ID:6706) | NSE Cash/F&O/CDS (Member ID: 90177) | MCX (Member ID: 57680) | DP registration No: IN-DP-418-2019 | CDSL DP No.: 12088600 | NSDL DP No. IN304300 | AMFI Registration No.: ARN –163403.
Details of Compliance Officer: Mr. Harinatha Reddy Muthumula (For Broking/DP/Research) | Email: compliance_sec@bajajbroking.in | Contact No.: 020-4857 4486. For any investor grievances write to compliance_sec@bajajbroking.in/ compliance_dp@bajajbroking.in (DP related)
This content is for educational purpose only. Securities quoted are exemplary and not recommendatory.
Research Services are offered by Bajaj Broking as Research Analyst under SEBI Regn: INH000010043.
For more disclaimer, check here: https://www.bajajbroking.in/disclaimer