Digital Gold vs Physical Gold

Digital Gold vs Physical Gold

Compare digital gold vs physical gold on safety, cost, tax and liquidity. See which fits your goal and which one you can pledge for a gold loan.

To find the nearest gold loan branch,

Enter phone and OTP | Check amount you can get | Apply for quick funds


Key takeaways

Physical gold gives you ownership you can hold and pledge for a gold loan. Digital gold lets you start small but sits outside Securities and Exchange Board of India (SEBI) regulation.

  • Both carry Goods and Services Tax (GST) of 3% on purchase.
  • Gains on both are taxed alike: slab rate up to 24 months, 12.5% after.
  • SEBI cautioned investors on 8 November 2025 that digital gold sits outside its investor protections.
  • Bajaj Finance accepts physical jewellery, ornaments and coins as gold loan collateral, but not digital gold.
  • Gold loans run from Rs. 5,000 to Rs. 2 crore, with interest from 9.50% p.a.

Choose digital gold for small, flexible purchases. Choose physical gold if you want an asset you can hold, gift or pledge for a gold loan.


Last updated: October 2026

Digital gold vs physical gold: which is better?

Neither is better for every investor. Digital gold suits small, flexible purchases, and physical gold suits ownership you can hold, gift or pledge. The table shows the difference between digital gold and physical gold on nine parameters.


ParameterPhysical goldDigital gold
FormJewellery, coins and bars that you holdA balance of gold that the platform's custodian holds for you
RegulationJewellery carries a Bureau of Indian Standards (BIS) hallmark with a Hallmark Unique Identification (HUID) codeOutside SEBI regulation, as per SEBI's caution of 8 November 2025
PurityThe hallmark shows purity, such as 916 for 22 caratThe platform states the purity, so read its terms before you buy
Minimum purchaseSet by the jeweller or dealer, and coins come in fixed weightsSmall amounts, set by the platform
Cost at purchaseGST of 3% on gold value and on making chargesGST of 3% on gold value, so compare the platform's buy rate and sell rate
StorageYou store it at home or in a locker and carry the theft and loss riskThe platform's custodian stores it, so you carry platform and custodian risk
Tax on saleSlab rate up to 24 months, 12.5% after 24 months, no indexationSlab rate up to 24 months, 12.5% after 24 months, no indexation
LiquidityYou sell to a jeweller or dealer on their buyback termsYou sell on the platform, and redemption as coins depends on the platform
Gold loan collateralYes, Bajaj Finance accepts jewellery, ornaments and coinsNo, Bajaj Finance does not accept digital gold

Worked example. Meera, 34, is a salaried professional in Pune. She buys gold worth Rs. 1,00,000. As jewellery with an assumed making charge of 8%, she pays Rs. 1,00,000 + Rs. 8,000 + GST of Rs. 3,240 (3% of Rs. 1,08,000) = Rs. 1,11,240. As digital gold, she pays Rs. 1,00,000 + GST of Rs. 3,000 = Rs. 1,03,000, before any difference in platform buy and sell rates. The 8% making charge is an assumption, because each jeweller sets its own.

Use this guide to choose:

  • Choose digital gold if you want to start with a small amount and accept platform risk.
  • Choose physical gold if you want to hold the asset, gift it or pledge it for a gold loan.
  • Consider SEBI-regulated gold products if you want investor protection. These are Gold Exchange Traded Funds (ETFs), exchange-traded commodity derivative contracts and Electronic Gold Receipts.
Show More Show Less

Is digital gold safe compared with physical gold?

Digital gold carries platform risk because it sits outside SEBI regulation. SEBI said on 8 November 2025 that digital gold is neither a security nor a commodity derivative. Securities-market investor protections therefore do not apply to it.

Physical gold carries theft and loss risk, which you manage through storage and insurance. Ask these four questions before you buy digital gold:

  • Who holds the gold, and in which vault?
  • Does insurance cover your holding? Get the terms in writing.
  • What are the sale and redemption terms, including the buy rate and sell rate?
  • Where do you complain if the platform fails? No SEBI grievance mechanism applies.

For physical gold, buy hallmarked jewellery and check the HUID code with the BIS Care app. Keep the gold in a bank locker or a home safe.


What is digital gold?

Digital gold is gold that you buy online in small amounts, and the platform's custodian holds it for you. Your holding is recorded electronically, and its value follows the market price of gold. Read what is digital gold for the full explanation.

Digital gold offers four practical benefits:

  • You can buy a fraction of a gram.
  • You need no home storage.
  • You can buy and sell online at any time the platform is open.
  • You can track your holding and its value online.

To see how demand has moved, read about gold investment trends.


How is the digital gold rate today set?

Each platform sets its own digital gold rate, and the rate follows the market price of gold. Compare the platform's buy rate and sell rate before you invest. Check the live gold rate on the live gold rate page.

Physical gold prices differ by jeweller because making charges differ. Ask for an itemised bill that separates gold value, making charges and GST.


What is physical gold?

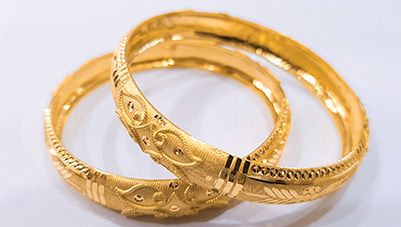
Physical gold is gold that you hold in the form of jewellery, coins or bars. You can store it, gift it or pledge it for a gold loan.

Physical gold offers four practical benefits:

  • You own the asset directly, with no platform in between.
  • You can wear or gift it, and families often pass it on.
  • You can sell it to a jeweller or dealer.
  • You can pledge it for a gold loan instead of selling it.

The costs are making charges on jewellery, GST of 3% and storage. Check the hallmark and the purity mark before you buy, such as 916 for 22 carat gold.


How are digital gold and physical gold taxed?

Both carry GST of 3% on purchase. On sale, both follow the same capital gains rules for transfers on or after 23 July 2024.


Holding periodTreatment of gainRate
24 months or lessShort-term capital gain, added to your incomeYour income tax slab rate
More than 24 monthsLong-term capital gain12.5%, without indexation

Pledging gold for a loan is not a sale, so the pledge itself creates no capital gain. See the tax benefits of gold loan page for how loan interest is treated. Check your own position with a tax professional.


How do I buy digital gold or physical gold?

Follow these steps for each type.

Physical gold:

  1. Buy from a bank, a bullion dealer or a jeweller, and ask for a written invoice.
  2. Check the purity mark, the BIS hallmark and the HUID code.
  3. Store the gold in a bank locker or a home safe.

Digital gold:

  1. Read the platform's terms on purity, custodian, insurance and redemption.
  2. Compare the buy rate and sell rate across platforms.
  3. Confirm how you complain if something goes wrong, since SEBI's grievance mechanism does not apply.

The difference between digital gold and physical gold lies in who holds the gold, who regulates the product and what you can pledge.


Can you use digital gold for a gold loan?

No. Bajaj Finance does not offer a digital gold loan, and it does not accept digital gold as collateral. The Reserve Bank of India (RBI) recognises only gold jewellery, ornaments and coins as eligible collateral for a gold loan.

Bajaj Finance accepts 18-22 karat jewellery and ornaments, and 24 karat gold coins. If your digital gold platform offers redemption as coins, ask for the terms. Eligible coins can then be pledged, subject to valuation.


What gold loan can you get against physical gold?

Bajaj Finance Gold Loan offers amounts from Rs. 5,000 to Rs. 2 crore. Interest starts from 9.50% p.a., and tenure runs from 1 day to 12 months. See the options for a gold loan in India before you compare lenders.

The lender values your gold at the lower of two prices: the previous day's closing price, or the 30-day average closing price. The India Bullion and Jewellers Association (IBJA) or a SEBI-regulated commodity exchange publishes both. Track the gold value trend to time your pledge.

Loan to Value (LTV) is the maximum share of your gold's value that the lender gives as a loan. The RBI caps it by loan amount. To know about LTV in detail, click here. 


Worked example. Rohan, 34, is a salaried professional in Delhi. His physical gold has an eligible value of Rs. 2,00,000 after valuation. At 85% LTV, his maximum loan is Rs. 2,00,000 x 85% = Rs. 1,70,000. Branch valuation and credit assessment decide the final amount, so this example is not an offer.

You are eligible if you meet these conditions:

  • You are a salaried or self-employed individual, or a pensioner.
  • You are an Indian citizen residing in India.
  • Your age is between 21 and 80 years.

RBI limits apply to what you pledge:

  • Ornaments: total pledged weight across all loans cannot exceed 1 kilogram.
  • Gold coins: total pledged weight cannot exceed 50 grams.
  • Total loan exposure across ornaments, jewellery and coins cannot exceed Rs. 2 crore.

Plan your repayment with the gold loan calculator. See fees and charges for the current amounts.


Quick tip: Wondering how much you can borrow on your gold? Just check your gold loan eligibility—it takes seconds and minimal  paperwork!

Show More Show Less

Calculate your gold loan

How to avail of a gold loan against digital gold

To secure a gold loan using digital gold, first confirm with the lender whether they accept digital holdings as collateral, as not all lenders currently do. Once eligibility is verified, the digital gold needs to be stored with a registered, approved provider who can facilitate the loan process. Lenders will then assess the current market value of your digital gold and determine the loan amount based on the accepted loan-to-value ratio. One advantage of using digital gold is the simplified process—no physical handling or transport of gold is required. Additionally, loan approval is often faster, as the lender can confirm the gold’s worth instantly online. With various options for a gold loan in India, it’s worth comparing terms to find a lender offering favourable interest rates and terms specifically for digital gold. Digital gold loans provide a modern alternative, combining the security of gold-backed borrowing with the convenience of digital assets. 


It takes just 2 steps to check your eligibility for a Bajaj Finance Gold Loan. Enter your mobile number now.

Show More Show Less

Frequently asked questions

Digital Gold

Gold Value

What are the disadvantages of digital gold?

One disadvantage of digital gold is the reliance on technology and internet connectivity, which may pose risks such as cyber theft or hacking. Additionally, digital gold platforms may charge fees or commissions, reducing overall returns. Lack of physical possession and potential regulatory uncertainties are also drawbacks to consider.

Deciding between gold bonds and digital gold depends on individual preferences and investment goals. Gold bonds offer fixed interest rates and capital appreciation, while digital gold provides convenience and flexibility for small investments. Consider factors like returns, liquidity, and convenience to determine which option suits your needs best.

A digital gold loan allows you to borrow money by pledging your digital gold as collateral. Unlike traditional gold loans that require physical gold, a digital gold loan leverages your digital gold holdings. The loan amount is based on the value of the digital gold, which is typically calculated using the digital gold rate today. This option provides a convenient way to access funds without the need to physically handle or transport your gold.

Digital gold vs physical gold presents notable differences. While both forms have their advantages, digital gold is generally considered safe if stored through reputable platforms. The difference between digital gold and physical gold lies in storage and security: digital gold is stored electronically, reducing the risk of physical theft, while physical gold requires secure storage. Check the digital gold rate today and ensure the platform follows robust security measures. In terms of is digital gold safe, it is secure as long as it is managed by trusted and well-regulated providers.

The digital gold rate today varies depending on current market trends, which are influenced by global gold demand, currency fluctuations, and economic conditions. Investors can check reliable online platforms for the latest prices, which are updated frequently to reflect real-time values. This immediate price visibility helps investors make informed decisions when buying or selling digital gold, as they can track and monitor the rate conveniently from any location.

Investing in digital gold comes with tax considerations, including capital gains tax if held for over three years, taxed at 20% with indexation benefits. For shorter holding periods, gains are added to annual income and taxed per your income bracket. Additionally, Goods and Services Tax (GST) applies during purchase. To understand more, explore the tax benefits of gold loan to evaluate potential savings when using gold as collateral.

The value of gold for a loan is determined based on the gold loan gram rate, which reflects the current market price per gram. Lenders use this rate to estimate the gold's worth, providing a loan amount up to a specified percentage of the asset’s value, known as the loan-to-value (LTV) ratio. Gold purity, weight, and the latest gram rate are essential factors in this calculation, which affects the final loan amount you can secure.

Gold loan interest rates vary based on the lender, loan tenure, and market conditions. These rates typically range from 7% to 15%, depending on factors like loan amount and borrower profile. Gold loans generally have lower interest rates than unsecured loans due to the collateral involved. You can check the gold loan interest rate to compare current rates and find competitive offers, helping you make a more economical borrowing decision.

Yes, digital gold can be converted to physical gold. The difference between digital gold and physical gold is primarily in their form and storage. You can redeem your digital gold for physical gold, such as coins or bars, through the platform where it was purchased. This process usually involves checking the digital gold rate today and ensuring that the conversion complies with platform policies. The ability to convert ensures that you can access physical gold whenever needed while enjoying the convenience of digital gold management.

Show More Show Less

Disclaimer

Bajaj Finance Limited (BFL) has the sole and absolute discretion, without assigning any reason to accept or reject any application as per BFL policy. *