CIBIL Score of 800: What It Gets You and How to Keep It

CIBIL Score of 800: What It Gets You and How to Keep It

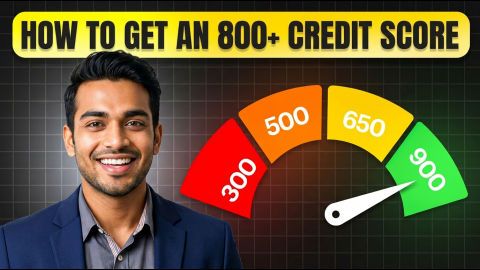
An 800 CIBIL score sits near the top of the 300 to 900 scale. It shows lenders a long, clean record, but your income and existing loans still shape every offer.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


In summary

An 800 CIBIL score is well above the Bajaj Finance criterion of 650. It tells lenders you pay on time and use credit with care. It can support better terms, but it does not guarantee them. Lenders still look at what you earn and your current equated monthly instalments (EMIs). In the example below, a borrower with 803 repays Rs. 15,224 a month on Rs. 4.6 lakh. To keep an 800 CIBIL score, protect every due date and keep card balances low.


  • 800 is near the top of the scale.
  • It supports an offer but does not decide it.
  • Income and EMIs still count.
  • One late payment costs points.

Have a score of 800? Check your loan offer with your phone number and a one-time password (OTP) → apply online → funds may be credited within 24 hours* of approval, subject to verification.

What does an 800 CIBIL score mean?

TransUnion CIBIL scores you from 300 to 900. A higher number shows a lower risk of missed payments. An 800 CIBIL score reflects:


  • Years of on-time payments: No recent late payments on any loan or card.
  • Low card balances: You use a small part of your card limits.
  • A long credit history: Your oldest accounts have run for 10 years or more.
  • Fresh applications are rare: You apply for new credit only when you need it.

It is a strong score. But an 800 CIBIL score sums up your past, not your ability to repay a new loan today.

Show More Show Less

What can an 800 score do for you?

An 800 CIBIL score helps your application in 4 ways:

  • It clears every common score cut-off: Most lenders set their minimum well below 800.
  • It can support a larger amount: If your income allows, a strong record gives the lender more confidence.
  • It can support better terms: Some lenders offer lower rates or fees to strong profiles.
  • It means fewer questions: A clean report needs less explanation.
Show More Show Less

What can an 800 score not do?

An 800 CIBIL score has limits. It does not:

  • Raise your income: The lender still checks whether your salary can carry the EMI.
  • Cancel existing EMIs: If your current loans take a large share of your pay, the offer may be smaller.
  • Guarantee approval: Your job, documents and verification still count.
  • Last on its own: It needs the same habits that built it.

Two people with a score of 800 can get very different offers if one has twice the income or half the EMIs.

Show More Show Less

How do you keep an 800 score when you borrow?

A large loan changes your report. These steps keep an 800 CIBIL score steady:

  • Apply to one lender at a time: Each application adds a hard enquiry.
  • Set up auto-debit: Pick a debit date just after payday.
  • Keep card use low after the loan: A high card balance on top of a new EMI looks like stress.
  • Do not close old cards: They keep your credit history long.

Expect a slight, brief dip once the loan starts. After that, on-time EMIs keep an 800 CIBIL score on track.


Aarti's kitchen and bathroom

Aarti, 41, is a senior architect at a Kochi design firm, drawing Rs. 1,18,000 a month. Her 800 CIBIL score, 803 to be exact, comes from 15 years of clean credit use. A new kitchen and bathroom called for Rs. 4.6 lakh, which she borrowed at an illustrative 11.75% per annum without denting her 800 CIBIL score. She set the equated monthly instalment (EMI) at 3 years against 4.


EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. Here P = Rs. 4,60,000, R = 11.75 ÷ 1,200 and N = months.


TenureMonthly EMI (Rs.)Total interest (Rs.)EMI as share of salary (%)
36 months (3 years)15,22488,05412.9
48 months (4 years)12,0571,18,74510.2

Last updated: 27th October, 2026


Taking 4 years would shave Rs. 3,167 off each instalment and add Rs. 30,691 to the interest bill. The fee for processing may come to Rs. 18,998 at most. Aarti went with 36 months, as the EMI was 12.9% of her salary.


What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.


Holding an 800 CIBIL score? With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online → funds may be credited within 24 hours* of approval, subject to verification.

Show More Show Less

Which slips cost the most points at 800?

At an 800 CIBIL score, small slips show clearly. These cost the most:

  • A late EMI or card payment: Even one 30-day delay can pull the score down sharply.
  • A maxed-out card: A balance near the limit raises your credit use at once.
  • 3 or more applications in a month: A cluster of enquiries suggests a cash shortage.
  • A settled loan: Settling for less than the full amount leaves a lasting negative mark.

You can avoid most of these with auto-debit and a habit of checking your report every 3 months.

Show More Show Less

Can you get a personal loan with an 800 score?

Your score clears the bar with room to spare. The Bajaj Finance Personal Loan sets its CIBIL criterion at 650. It offers Rs. 40,000 to Rs. 75 lakh over 12 months to 108 months, for Indian nationals aged 21 years to 80 years. Your income and existing EMIs then shape the amount you get with an 800 CIBIL score.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

What 800 means

Keeping it

Is 800 a good CIBIL score?

Yes. On the 300 to 900 scale, 800 is near the top. It shows a long record of on-time payments and careful credit use. It is well above the Bajaj Finance criterion of 650. Lenders still check your income, existing EMIs and job before they decide on an offer for an 800 CIBIL score holder.

Not by itself. A strong score can support better terms, but each lender prices a loan on your full profile. Your income, employer, existing EMIs and the loan amount all count. Compare offers on the yearly cost, including fees, shown in each Key Fact Statement. An 800 CIBIL score helps, but it is one input.

Clear every bill in full by its due date, and keep card balances well below their limits. Apply for new credit only when you need it, and keep old accounts open. Check your report every 3 months for errors. These habits keep an 800 CIBIL score steady through a new loan.

A small dip is possible at first: the application leaves a hard enquiry, and the loan opens a new account. From then on, every EMI paid on time strengthens your record. A missed EMI brings the sharpest fall. Set up auto-debit and keep one EMI as spare cash in your account.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.


For customer support, call Personal Loan IVR: 7757 000 000