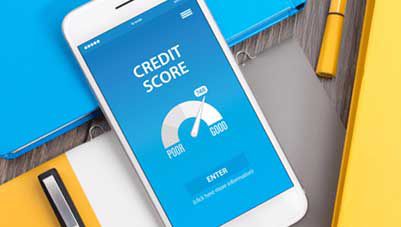
If your credit score is below 650, improve it before you apply: pay every EMI and card bill on time, keep card balances low and fix report errors. Avoid applying while it is low, since a rejection adds an enquiry.
Worked example: Abhishek in Ujjain
Abhishek is 28 and works as a salaried hotel guest relations manager in Ujjain. He earns Rs. 54,000 a month and has a credit score of 702, above the criterion. He borrows Rs. 1.6 lakh for a two-wheeler and a laptop, at an illustrative 16% per annum.
EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. P is the loan amount in rupees, R is the annual rate divided by 12 and by 100, and N is the tenure in months. The formula spreads the principal and interest into equal monthly payments, so early EMIs carry more interest and later ones more principal. All figures are rounded to the nearest rupee.
| Tenure | Monthly EMI (Rs.) | Total interest (Rs.) | EMI as share of salary (%) |
|---|
| 24 months (2 years) | 7,834 | 28,018 | 14.5 |
| 36 months (3 years) | 5,625 | 42,505 | 10.4 |
Last updated: 22nd October, 2026
The 36-month option lowers the EMI by Rs. 2,209 but adds Rs. 14,487 in interest. The processing fee on Rs. 1.6 lakh is up to Rs. 6,608. Abhishek picks 36 months (3 years), so the EMI stays near 10% of his salary and every on-time payment adds to his credit score.
What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.
Checking whether your credit score qualifies? With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.