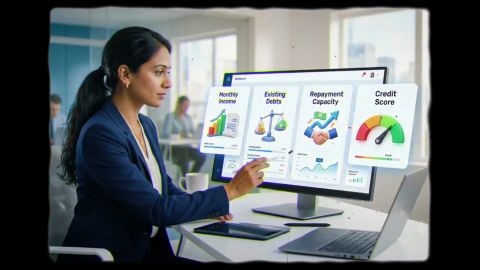
Siddharth's new loan sits on top of a car EMI of Rs. 9,000. The table shows the new EMI and the total, both as a share of his Rs. 70,000 salary.
| Tenure | New EMI (Rs.) | Total interest (Rs.) | New EMI as share of salary (%) | All EMIs as share of salary (%) |
|---|
| 48 months (4 years) | 11,268 | 1,20,842 | 16.1 | 29.0 |
| 60 months (5 years) | 9,556 | 1,53,377 | 13.7 | 26.5 |
Last updated: 24th October, 2026
The 60-month option keeps his total under 27% of pay. The 48-month option costs Rs. 32,535 less in interest but takes 29%.
Worked example: Siddharth in Gwalior
Siddharth is 35, a salaried power distribution company assistant engineer in Gwalior, earning a Rs. 70,000 salary; his CIBIL score is 758. He already pays Rs. 9,000 a month on a car loan. He borrowed Rs. 4.2 lakh to renovate his parents' home, at an illustrative 13% per annum, testing how 2 tenures sat with his car EMI on a Rs. 70,000 salary.
EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. Here P = Rs. 4,20,000, R = 13 ÷ 1,200 and N = months.
The table above shows his options. Processing would cost him no more than Rs. 17,346. Siddharth chose 48 months, since his car loan ends in 18 months and his total burden then falls to 16.1% of pay.
What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.
On a Rs. 70,000 salary? With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.