








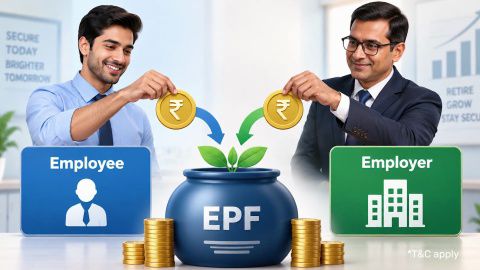
Employee Provident Fund (EPF)
In summary
Here is an overview of the key statutory rules, procedural steps, and financial implications you need to know about the Employees' Provident Fund:
- Mandatory coverage: Applicable to all formal establishments with 20 or more employees, with mandatory enrollment for workers earning up to ₹15,000 basic wage per month.
- Dual contribution model: Employees contribute 12% exclusively to EPF; employers contribute 12% split between EPF (3.67%) and EPS (8.33% capped at ₹1,250/mo), along with EDLI insurance and administrative charges.
- Monthly accrual with annual compounding: Interest accumulates every month on running ledger balances and compounds annually into the principal on March 31.
- Partial advances available: Subscribers can access non-refundable partial advances using Form 31 for specific life events including medical emergencies, home purchase, and children's education.
- 5-year tax threshold: Withdrawing funds before completing 5 years of continuous service triggers 10% TDS under Section 192A and makes past deductions taxable as salary.
- Portfolio diversification: Because EPF locks money until retirement, disciplined investors balance statutory holdings with high-yielding Bajaj Finance Fixed Deposits offering up to 8.15% p.a. with CRISIL AAA safety.
Did you know?
Interest on your EPF account is calculated on your monthly running balance, but it is credited to your passbook only once a year on March 31. If you withdraw your EPF funds in the middle of a financial year, the EPFO calculates interim interest from April 1 up to the exact date of settlement, ensuring zero loss of accrued interest.
What is the Employees' Provident Fund and how does the EPFO ecosystem work?
The EPFO umbrella delivers social security through three complementary statutory schemes:
- Employees' Provident Funds Scheme, 1952 (EPF): Focuses on capital accumulation during active employment, paying out a lump-sum corpus with accumulated interest at retirement.
- Employees' Pension Scheme, 1995 (EPS): Provides guaranteed lifelong monthly pensions to members retiring after age 58 who have completed at least 10 years of eligible service, as well as widow and orphan pensions.
- Employees' Deposit Linked Insurance Scheme, 1976 (EDLI): Provides life insurance coverage of up to ₹7,00,000 to the legal heirs or nominees of an active member if they pass away during service, funded entirely by the employer at zero cost to the worker.
Who is eligible for EPF coverage under statutory rules?

Avoid these mistakes while booking FD
The following table details the statutory coverage thresholds, establishment criteria, and enrollment rules governing EPF membership:
| Parameter | Statutory Requirement | Legal Rule & Applicability |
|---|---|---|
| Establishment Size | Establishments employing 20 or more persons | Mandatory statutory registration under Section 1(3) of the EPF Act. |
| Statutory Wage Threshold | Monthly Basic Pay + DA up to ₹15,000 | Mandatory enrollment for every eligible employee from day one. |
| Voluntary Opt-In (> ₹15,000) | Starting Basic Pay + DA exceeding ₹15,000 | Can opt into EPF voluntarily by submitting a joint declaration (Form 11) with the employer. |
| Voluntary Employer Registration | Establishments with fewer than 20 employees | Can register voluntarily with EPFO if the employer and majority of employees agree. |
| Contractual and Gig Workers | Contract staff, temporary workers on payroll, and expats | Fully eligible under standard EPFO contribution mandates. |
How is your monthly EPF contribution split between retirement, pension, and insurance?
The table below outlines the precise statutory percentage allocation of employee and employer contributions across EPF, EPS, and EDLI schemes:
| Contribution Component | Employee Share | Employer Share | Target Fund / Purpose |
|---|---|---|---|
| EPF Account 1 (Provident Fund) | 12.00% | 3.67% | Core retirement balance compounding at the declared EPF rate. |
| EPS Account 10 (Pension Scheme) | 0.00% | 8.33% | Capped at ₹1,250/mo based on the ₹15,000 wage ceiling to fund pensions. |
| EDLI Account 21 (Life Insurance) | 0.00% | 0.50% | Funds life insurance coverage up to ₹7 lakh (capped at ₹75/mo). |
| EPF Admin Charges (Account 2) | 0.00% | 0.50% | Covers operational and administrative expenses of the EPFO. |
| Total Monthly Contribution | 12.00% | 13.00% | Total statutory deduction and employer contribution. |
Monthly Contribution Breakdown (Basic + DA):
--------------------------------------------
[ Monthly Basic Pay + DA ]
│
┌─────────────────────────┴─────────────────────────┐
▼ ▼
Employee Contribution (12.0%) Employer Contribution (13.0%)
│ │
▼ ┌─────────────────┴─────────────────┐
100% to EPF (12.0%) ▼ ▼
Statutory 12.0% Share Administrative Levies (1.0%)
│ │
┌───────┴───────┐ ┌───────┴───────┐
▼ ▼ ▼ ▼
3.67% to EPF 8.33% to EPS* 0.50% to EDLI 0.50% to EPF
(Max ₹1,250) (Max ₹75) (Admin charges)
*Note: Under statutory rules, the 8.33% employer pension deduction is calculated on a maximum wage ceiling of ₹15,000 (₹15,000 × 8.33% = ₹1,250 per month). Any excess employer share above ₹1,250 automatically flows into the employee's EPF Account 1.
How is EPF interest calculated and compounded on your balance?
The monthly calculation methodology:
- Opening Balance on April 1: The starting balance consists of principal plus accumulated interest from previous years.
- Monthly Additions: Each month, your employee contribution (12%) and employer EPF share (3.67% plus any excess over ₹1,250) are credited to your account.
- Monthly Interest Formula: Interest is calculated at the end of each calendar month on the running closing balance: Monthly Interest = (Closing Balance of Month × Annual Interest Rate) ÷ (12 × 100)
- Annual Compounding Credit: The sum of all 12 monthly interest calculations is added to your account ledger as a lump sum on March 31, becoming part of the new principal to compound in the following financial year.
What digital services does the EPFO provide for employers and employees?
- Online Establishment Registration (Shram Suvidha Portal): New businesses can register for EPF coverage and obtain an establishment code within hours without physical visits.
- Unified Member e-Sewa Portal: Employees can activate their UAN, link KYC records (Aadhaar, PAN, Bank details), download UAN cards, and register family e-nominations.
- Electronic Challan cum Return (ECR): Employers upload monthly wage files and generate electronic challans, transferring statutory deductions via integrated net banking gateways.
- Online Transfer Claims (Form 13): Employees changing jobs can transfer accumulated balances between Member IDs seamlessly through the One Member - One EPF Account facility.
- EPFiGMS Grievance Management (epfigms.gov.in): An automated portal where subscribers can lodge complaints regarding settlement delays, transfer issues, or employer non-compliance, tracking resolution in real time.
When can you withdraw from your EPF and how do partial advances work?
Permitted partial advances under Form 31:
To support life milestones without forcing account closure, the EPFO permits non-refundable partial advances for specific purposes:
- Medical Treatment: For life-threatening illnesses of self or family members (up to 6 months' basic wages or employee share with interest).
- Home Purchase or Construction: Available after completing 5 years of service (up to 36 months' basic wages).
- Home Loan Repayment: Available after 10 years of service (up to 36 months' basic wages).
- Marriage of Self, Siblings, or Children: Available after 7 years of service (up to 50% of employee contribution).
- Post-Matric Education of Children: Available after 7 years of service (up to 50% of employee contribution).
Online vs Offline Withdrawal Methods:
Online Withdrawal (Via Member Portal):
- Log in with UAN and password -> Select Online Services > Claim (Form 31/19/10C).
- Authenticate via Aadhaar OTP -> Funds credited directly via NEFT in 3 to 10 days.
Offline Withdrawal (Physical Submission):
- Fill Composite Claim Form (Aadhaar or Non-Aadhaar).
- Submit physical copy attested by employer/bank to regional EPFO office (takes 20 to 30 days).
Why should you avoid withdrawing your EPF before completing 5 years of service?
1. Mandatory TDS deduction under Section 192A
If your total withdrawal amount exceeds ₹50,000 and your continuous service is less than 5 years, the EPFO must deduct Tax Deducted at Source (TDS) at 10% (if a valid PAN is linked) or at the maximum marginal rate of 20% (if PAN is missing).
2. Retroactive tax on previous employer contributions and deductions
- Employer Contribution & Interest: Taxed in full as Salary Income at your applicable slab rate.
- Section 80C Deductions Reversed: Any deductions claimed on your employee contributions in past financial years are revoked and added back to your taxable income.
- Employee Contribution Interest: Taxed under Income from Other Sources.
Key facts: Protecting your continuous service record
- Transfer instead of withdraw: When moving between companies, always transfer your EPF balance using the online Member Portal. Service across multiple employers is combined, preserving your continuous service record and protecting your tax-free status once you cross 5 cumulative years.
- Form 15G / 15H relief: If your total taxable income is below the basic exemption threshold, submit Form 15G (or Form 15H for senior citizens) to prevent TDS on premature withdrawals.
How is EPF taxed across contribution, interest accrual, and withdrawal stages?
1. Contribution Phase
- Employee Contribution: Eligible for deduction up to ₹1,50,000 under Section 80C of the Income-tax Act (available under the Old Tax Regime).
- Employer Contribution Cap [Section 17(2)(vii)]: Combined annual employer contributions to EPF, NPS, and approved superannuation funds exceeding ₹7,50,000 are taxed as a perquisite in your hands.
2. Interest Accrual Phase (The ₹2.5 Lakh Cap)
Under amendments introduced under Section 10(11) and Section 10(12):
- Interest earned on employee contributions up to ₹2,50,000 per financial year remains 100% tax-free.
- If your annual employee contribution exceeds ₹2,50,000, interest earned on the excess contribution is segregated into a separate non-taxable vs taxable ledger and taxed annually at your progressive slab rate.
3. Withdrawal Phase
- After 5 Years: Completely tax-free under Section 10(12).
- Before 5 Years: Fully taxable as salary and other income, subject to 10% TDS under Section 192A.
How can you check your EPF balance via the UMANG app, SMS, or missed call?
- UMANG Mobile App: Download the government's official UMANG app, select EPFO from the services list, choose "View Passbook", enter your UAN, and authenticate via OTP to view balances across all linked Member IDs.
- SMS Service: Send an SMS formatted as EPFOHO UAN ENG (where ENG denotes English, or HIN for Hindi) to 7738299899 from your registered mobile phone. EPFO responds with your latest contribution, total balance, and KYC status.
- Missed Call Facility: Give a missed call from your registered mobile number to 9966044425. The call disconnects automatically after two rings, and the EPFO sends a detailed SMS summary within seconds.
Weighing the guaranteed retirement compounding of EPF against liquidity constraints
The table below evaluates the primary wealth-building benefits of EPF against the operational and liquidity constraints experienced by members:
| Strengths & Advantages | Operational Limitations & Trade-Offs |
|---|---|
| Sovereign Capital Safety: Fully guaranteed by the Government of India, eliminating credit and market volatility risks. | Rigid Liquidity Lock-In: Funds remain locked until retirement at age 58, with strict conditions required for partial advances. |
| High Guaranteed Compounding: Delivers an attractive declared interest rate (8.25% p.a.) backed by annual compounding. | Tax Friction for Higher Earners: Annual employee contributions above ₹2.5 lakh incur slab-rate tax on accrued interest. |
| Automated Savings Discipline: Monthly payroll deductions enforce consistent wealth building without active effort. | Employer Attestation Bottlenecks: KYC updates and transfer forms often face employer delay or digital signature issues. |
| Integrated Triple Social Benefit: Provides retirement capital (EPF), lifetime pension (EPS), and survivor life insurance (EDLI). | Strict Wage Caps on Pension: Employer EPS contribution is capped at ₹1,250/mo, limiting the pension's real-terms value. |
How can fixed deposits provide liquid emergency buffers alongside long-term retirement savings?
For milestone goals—such as funding a child's higher education, purchasing a vehicle, planning home improvements, or maintaining an accessible emergency reserve—investors require predictable returns with high liquidity. Allocating surplus funds into Bajaj Finance Fixed Deposits provides an ideal strategic balance alongside your statutory EPF corpus:
Strategic advantages of Bajaj Finance Fixed Deposits
- Competitive guaranteed returns: Earn fixed interest rates of up to 7.75% p.a. for regular investors and up to8.15% p.a. for senior citizens, locking in reliable compounding.
- Top-tier credit safety ratings: Accredited with CRISIL AAA/STABLE and [ICRA]AAA(Stable) ratings, representing the highest credit quality and timely interest payments.
- Customizable tenures for real life: Choose flexible tenures from 12 to 60 months to align with planned milestones rather than decades-long lock-ins.
- Regular cash flow choices: Select Non-Cumulative monthly or quarterly interest payouts to generate predictable supplementary income, or Cumulative compounding to maximize growth.
Instant digital loans against FD: Access a paperless loan against your deposit of up to 75% of your deposit value online in minutes without breaking your fixed deposit or losing your locked-in rate.
Check out different FD Rates
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
Can an employee opt out of the EPF scheme?
An employee can opt out of EPF only at the very beginning of their career if their initial Basic Pay plus Dearness Allowance exceeds ₹15,000 per month and they have never previously held an active EPFO account. To opt out, the employee must submit Form 11 at the time of joining. Once enrolled, membership is mandatory and cannot be discontinued while employed in a covered establishment.
Can you contribute more than 12% to your EPF account?
Yes. You can voluntarily contribute more than the statutory 12% through the Voluntary Provident Fund (VPF), up to 100% of your Basic Pay and DA. Your employer is not required to match contributions above the statutory 12%. Note that interest earned on annual employee contributions exceeding ₹2,50,000 is subject to income tax at your applicable slab rate.
When does an EPF account stop earning interest?
If you are under 58 years of age, your account continues to earn interest even after leaving employment. However, under statutory rules, an account becomes inoperative and ceases to earn interest if the subscriber retires from service after attaining 55 years of age (or migrates abroad permanently) and no application for withdrawal is made within 36 months.
Can you withdraw your EPF balance for purchasing a home or medical treatment?
Yes. Active members can apply for non-refundable partial advances using EPFO Form 31 on the Member Portal for specified purposes, including medical treatment for serious illnesses, purchase or construction of a residential house, repayment of an existing home loan, or children's higher education, subject to satisfying minimum service requirements.
How is EPF withdrawal taxed if you have less than 5 years of continuous service?
If you withdraw before completing 5 years of continuous service, the employer's contribution and accrued interest are taxed as salary income, while the interest on your employee contribution is taxed under Income from Other Sources. Additionally, 10% TDS is deducted under Section 192A if the withdrawal exceeds ₹50,000, unless you submit Form 15G or Form 15H.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.