









Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
In summary
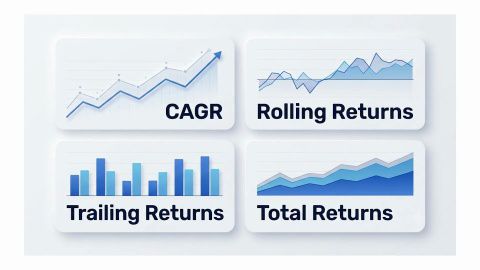
Understanding Mutual Fund Returns
Mutual fund returns show how much your investment has gained or lost over a period. Mutual funds do not offer a fixed return rate. Your return depends on the fund's investments, market conditions, investment period and other factors.
Before evaluating mutual fund returns, remember these points:
- A Rs. 10,000 investment that grows to Rs. 11,200 gives an illustrative return of 12%.
- Returns can be measured over 1 year, 3 years, 5 years or other periods.
- Absolute return shows the total gain or loss, while annualised return and CAGR help compare growth over time.
- Past performance does not guarantee future returns.
- You should consider risk, investment objective, benchmark, consistency and expenses when evaluating returns.
- The Bajaj Broking website offers access to 4,000+ mutual fund schemes across equity, debt, hybrid, ELSS, thematic and NFO categories.
- The minimum SIP amount is Rs. 100 per month.
Mutual fund returns can be positive or negative. Compare performance with the right benchmark and consider your investment horizon and risk tolerance before making an investment decision.
What are mutual fund returns?
Mutual fund returns show how much the value of your investment has increased or decreased over a period. The change is linked to the performance of the securities held by the mutual fund scheme.
For example, suppose you invest Rs. 10,000 in a mutual fund. After one year, the investment value becomes Rs. 11,200. Your gain is Rs. 1,200. The return is 12%.
Mutual funds do not offer a fixed return. The value of your investment can rise or fall based on market movements and the securities held by the scheme.
What is the average return of mutual funds?
There is no single average return that applies to all mutual funds. Different schemes invest in different securities and categories, so their returns can vary.
For example, a small-cap funds scheme and a debt-oriented scheme can have different return patterns because they invest in different types of securities.
When comparing returns, consider the scheme category, investment period, risk level, benchmark and investment objective. A single return figure does not provide enough information to judge a mutual fund.
Mutual fund category returns - Average from last 3 years
The source page provides category-level three-year return figures.
The following figures are retained from the source:
| Category | 3-year return (%) |
|---|---|
| Equity: Thematic-PSU | 33.22 |
| Equity: Sectoral-Infrastructure | 28.73 |
| Equity: Thematic-Transportation | 26.00 |
| Equity: Thematic-Manufacturing | 23.44 |
| Equity: Small Cap | 22.67 |
| Equity: Contra | 22.07 |
| Equity: Mid Cap | 21.47 |
| Equity: Dividend Yield | 20.39 |
| Equity: Value | 19.62 |
| Equity: Thematic-Consumption | 19.55 |
| Equity: Multi Cap | 19.48 |
| Equity: Sectoral-Pharma and Healthcare | 19.45 |
| Equity: Large and Mid Cap | 17.86 |
| Equity: Thematic-Others | 17.76 |
| Equity: Thematic-Quantitative | 16.79 |
| Equity: Thematic-Energy | 16.65 |
| Equity: ELSS | 16.30 |
| Equity: Flexi Cap | 15.84 |
| Equity: Focused | 15.42 |
| Fund of Funds-Domestic-Equity | 15.15 |
| Fund of Funds-Domestic-Gold | 15.14 |
| Equity: Sectoral-FMCG | 14.93 |
| Hybrid: Multi Asset Allocation | 14.55 |
| Index Fund | 13.96 |
| ETFs | 13.94 |
These figures show that returns can differ across categories. They should not be treated as guaranteed future returns.
What are the types of mutual fund returns?
Different return measures answer different questions. Understanding each measure can help you compare investments over the right period.
Absolute returns
Absolute return shows the percentage change in the value of an investment between two points in time. It is useful when you want to see the total gain or loss over a period.
For example, if you invest Rs. 10,000 and the value becomes Rs. 11,500, the gain is Rs. 1,500. The absolute return is 15%.
You can learn more about absolute return to understand how this measure works.
Annualised returns
Annualised return shows the average yearly rate of return over a period longer than one year. It helps you compare investments held for different periods on a yearly basis.
Annualisation does not mean that the investment actually earned the same return every year. It is a way of expressing the overall growth as a yearly rate.
Total returns
Total returns consider the overall change in the investment value over the selected period. Depending on the type of investment and the return measure used, distributions or income may also form part of the total return.
When comparing mutual fund returns, check what the reported return figure includes.
Point-to-point returns
Point-to-point return measures the change in investment value between two specific dates.
For example, you can compare the value of a mutual fund on 1 January with its value on 31 December. The result shows the change between those two points.
This measure depends on the dates selected. Different start and end dates can produce different return figures.
Trailing returns
Trailing return measures a fund's performance over a fixed period ending on a selected date. Examples include one-year, three-year and five-year periods.
Trailing returns can help you understand how a fund performed up to a particular date. However, the result can change as the end date moves.
You can also read about the difference between trailing and rolling returns in mutual funds.
Rolling returns
Rolling returns calculate returns over multiple overlapping periods within a larger time range. This gives you more return observations instead of relying on one start and end date.
For example, a three-year rolling return can be calculated using many different three-year periods within a longer historical period.
This can help you study the consistency of returns across different market periods.
Compound Annual Growth Rate (CAGR)
Compound Annual Growth Rate, or CAGR, shows the annualised growth rate of an investment over a period, assuming the investment grew at a compounded rate.
CAGR is useful when comparing investments held for more than one year. It does not show the actual return earned in each individual year.
You can read more about Compound Annual Growth Rate.
How to calculate mutual fund returns
The method used to calculate returns depends on the type of investment and the return measure you want to use.
For a simple investment made once, you can first find the difference between the current value and the original investment. You can then express the gain or loss as a percentage of the original investment.
For example:
- Original investment = Rs. 10,000
- Current value = Rs. 11,200
- Gain = Rs. 1,200
- Return = 12%
For investments made through multiple instalments, such as an SIP, the timing of each investment matters. Measures such as XIRR can be used to account for different investment dates.
How to calculate your mutual fund returns online?
A mutual fund calculator can help you estimate or understand investment outcomes using the information you enter. The exact result depends on the inputs used.
You can follow these steps:
- Open the mutual fund calculator.
- Select the relevant investment method, such as an SIP or lumpsum.
- Enter the investment amount and investment period.
- Enter the expected return rate where the calculator asks for an estimate.
- Review the calculated investment value and estimated returns.
The Bajaj Broking website also provides access to mutual fund investment tools that can help you review your investment information.
How should you evaluate mutual fund returns?
A return figure should not be viewed on its own. You need to consider the risk taken to generate the return and whether the fund follows its stated objective.
The following factors can help you evaluate a mutual fund's return:
- Risk-adjusted returns: Compare the return with the level of risk involved.
- Consistency: Look at performance across different periods instead of relying on one period.
- Fund objective: Check whether the scheme's investment approach matches your purpose.
- Benchmark: Compare the fund's performance with its relevant benchmark.
- Investment period: Use a return measure that matches the period you are analysing.
- Past performance: Past returns can provide historical information but do not guarantee future performance.
You can also read about picking a mutual fund before comparing schemes.
What factors affect mutual fund returns?
Several factors can affect the returns earned by a mutual fund. The effect can vary across schemes because each scheme can have a different portfolio and investment objective.
These factors include:
- The securities held by the scheme
- Changes in the market
- Changes in the economy
- Changes in a sector or industry
- The fund manager's investment decisions
- The size and cash flows of the fund
- The total expense ratio
- The scheme's investment strategy
A fund manager makes investment decisions according to the scheme's stated objective. These decisions can affect the portfolio and, in turn, its performance.
The TER is another factor to consider because fund expenses can affect the amount of return available to investors.
What risks can affect mutual fund returns?
Mutual fund investments are subject to market-related risks. The value of the investment can increase or decrease depending on the securities held by the scheme and market conditions.
Common risks include:
- Market risk: Changes in market prices can affect the value of securities held by the scheme.
- Credit risk: A security issuer may fail to meet its payment obligations.
- Management risk: Investment decisions may affect scheme performance.
- Liquidity risk: Some securities may be difficult to buy or sell at the expected price.
The level and type of risk can differ across mutual fund categories. You should check the scheme information and its SEBI Riskometer before investing.
The SEBI Riskometer uses the following categories: Low, Low to Moderate, Moderate, Moderately High, High and Very High.
Are mutual fund returns taxable?
Mutual fund returns may be subject to tax depending on factors such as the type of mutual fund, the nature of the gain and the applicable tax rules.
Tax rules can change. The applicable tax treatment should therefore be checked using the current rules before making an investment decision.
Do not assume that mutual fund returns are tax-free simply because the investment is held for a particular period. The tax treatment depends on the applicable rules and the investment.
What should you remember before investing?
Understanding returns is only one part of evaluating a mutual fund. You should also consider the scheme's objective, risk level, investment period, benchmark and expenses.
The following points can help you review a scheme:
- Match the investment period with your financial goal.
- Check the scheme's investment objective.
- Review the relevant benchmark.
- Consider the risk level shown by the SEBI Riskometer.
- Check the expense ratio of the mutual fund.
- Compare returns over suitable periods.
- Do not select a scheme only because it recorded a high past return.
Understand that market-linked returns can be negative.
The different mutual funds available in the market can have different objectives, risks and return patterns.
Conclusion
Mutual fund returns show how the value of an investment changes over time. Different return measures, such as absolute returns, annualised returns, trailing returns, rolling returns and CAGR, help you study performance from different angles.
You should consider returns along with risk, investment period, benchmark, expenses and the scheme's objective. Past performance does not guarantee future returns.
The Bajaj Broking website provides access to 4,000+ mutual fund schemes across equity, debt, hybrid, ELSS/tax-saver, thematic and NFO categories. The platform supports SIP and lumpsum investments for most schemes. The minimum SIP amount is Rs. 100 per month.
KYC is mandatory before investing as a SEBI regulatory requirement. The Bajaj Broking website also provides tools such as Dashboard, Portfolio, Orders and MF Profile to help you track your investments.
Conclusion
Mutual funds offer a compelling way to participate in the stock market and potentially grow your wealth over time. By understanding the various types of mutual funds, their risk-return profiles, and how to invest through an SIP (Systematic Investment Plan), you can harness the power of these investment vehicles to achieve your financial goals. Remember, thorough research, discipline, and a long-term perspective are key to success in mutual fund investing. Consider consulting a financial advisor for personalised guidance tailored to your specific needs and risk tolerance. With careful planning and the right investment strategy, mutual funds can be a valuable tool on your path to financial security.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Overview
How often are mutual fund returns distributed to investors?
Mutual fund returns are not normally paid to you as a fixed interest amount at regular intervals. The value of your investment changes based on the performance of the securities held by the scheme.
The way returns are reflected also depends on the scheme and the option selected. You should check the scheme-related documents for details. The Bajaj Broking website provides access to mutual fund schemes across different categories.
What is the average return on a mutual fund?
There is no single average return for all mutual funds. Returns can vary based on the scheme category, securities held, market conditions, investment period and risk level.
For example, equity and debt-oriented schemes can have different return patterns. You should compare a scheme with its relevant benchmark and consider its investment objective instead of relying on one average figure. The Bajaj Broking website offers access to schemes across several categories.
Is a 10% return on a mutual fund good?
A 10% return cannot be judged as good or bad on its own. You need to consider the period, scheme category, risk level, benchmark and investment objective.
A return should also be viewed against the risks taken to generate it. Past performance does not guarantee future returns. The Bajaj Broking website provides access to mutual fund schemes that can differ in their objectives and risk levels.
What is the average ten-year return on mutual funds in India?
There is no single ten-year average return for all mutual funds in India. Different schemes and categories can produce different results over the same period.
A useful comparison should consider the relevant category, benchmark, investment period and risk. Historical returns can help you understand past performance, but they cannot predict future returns. The Bajaj Broking website provides access to schemes across multiple mutual fund categories.
Can mutual fund returns be negative?
Yes. Mutual fund returns can be negative because mutual funds are market-linked investments.
If the value of the securities held by a scheme falls, the value of the investment can also fall. The extent of the change depends on the scheme and the securities it holds. You should consider the scheme's risk level and investment objective before investing. The Bajaj Broking website provides access to schemes across different categories.
How is CAGR calculated for mutual funds?
The Compound Annual Growth Rate (CAGR) for a mutual fund is calculated using the formula: CAGR = (Final Value / Initial Value)^(1 / Number of Years) - 1. Multiply the result by 100 to convert it into a percentage. You can also compute this quickly using an online.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.