








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
How to Track & Evaluate Mutual Fund Performance
In summary
Evaluating mutual fund performance means looking beyond the return percentage. You need to consider how the fund performed against an appropriate benchmark, how much risk it took, what it costs, and whether its portfolio still fits your objective.
- Compare returns over relevant periods rather than relying on a single period.
- Use the fund's benchmark to understand how it performed against an appropriate market reference.
- Risk-adjusted measures such as Sharpe and Treynor ratios add context to returns.
- Rolling returns can show how a fund performed across different market periods.
- Review costs, portfolio composition, fund management, and consistency alongside performance.
For example, a fund returning 14% is not automatically better than one returning 12%. The risk taken and the relevant benchmark also matter.
Review performance periodically, but avoid making changes based only on short-term market movements.
What does mutual fund performance mean?
Mutual fund performance describes how a scheme’s investment value has changed over a specific period. Returns are an important part of performance, but they do not provide the complete picture.
A proper assessment also considers the risk taken, the relevant benchmark, similar schemes, costs, and consistency. The evaluation method can differ according to the type of fund, your investment period, and your financial goal.
For example, an equity fund and a liquid fund have different objectives and risk levels. Comparing their returns would not help you make a meaningful decision.
How can you check mutual fund performance?
You can check mutual fund performance by reviewing seven connected factors. No single return figure can show whether a scheme has performed consistently or taken excessive risk.
The following checklist provides a practical starting point:
| Evaluation factor | What to check |
|---|---|
| Returns | Absolute return, annualised return, and rolling return |
| Comparison | Stated benchmark and funds in the same category |
| Risk | Volatility, downside risk, alpha, beta, and Sharpe ratio |
| Scheme details | Costs, portfolio, turnover, and fund management |
You can find scheme information and compare a mutual fund scheme with alternatives in the same category. Always use matching plans, options, and periods.
Compare the fund with its benchmark
A benchmark is an index selected to represent the market or investment universe against which a scheme measures its performance. The benchmark should match the scheme’s investment objective and mutual fund’s portfolio.
Compare the fund and benchmark over the same period. Also check whether the figures use the same return method. A Total Return Index includes dividends or interest from index constituents, which makes it more suitable for comparison with scheme returns.
Do not treat one period of outperformance as proof of skill. Check whether the scheme has remained reasonably consistent across rising, falling, and flat markets.
Compare similar funds over matching periods
Peer comparison means comparing a scheme with other funds in the same category. Compare large-cap funds with large-cap funds, index funds tracking the same index, and debt funds with similar duration and credit profiles.
Suppose you make an SIP investment in an index fund. You could compare its tracking difference, costs, and returns with funds following the same index.
You can also compare mutual funds across 1-year, 3-year, and 5-year periods. However, a category rank can change quickly. A top-quartile position during one period does not establish consistent performance.
Review absolute and annualised returns
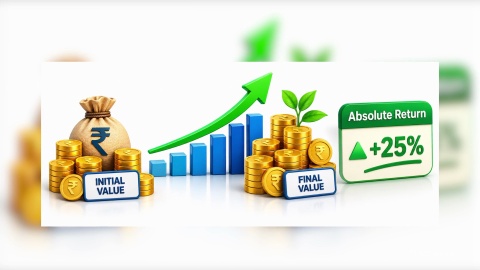
An absolute return shows the total percentage change between the initial value and final value. It does not adjust for the length of the investment period.
Compound Annual Growth Rate (CAGR) converts growth over more than one year into an annualised rate. It assumes steady compounded growth for calculation, even though actual yearly returns fluctuate.
For an illustrative example, Asha invests Rs. 1 lakh and its value becomes Rs. 1.21 lakh after 2 years:
Absolute return = (Rs. 1.21 lakh − Rs. 1 lakh) ÷ Rs. 1 lakh × 100 = 21%
CAGR = (Rs. 1.21 lakh ÷ Rs. 1 lakh)^(1 ÷ 2) − 1 = 10% per annum
The calculation describes past growth. It does not indicate what Asha will earn in future.
Examine rolling returns
Rolling returns measure returns for overlapping periods across a longer timeline. For example, 3-year rolling returns can be calculated daily, monthly, or quarterly for every available 3-year window.
This method reduces the influence of one selected start date and end date. It helps you observe how often a fund delivered positive, negative, or benchmark-beating returns across different market conditions.
Rolling returns are particularly useful for assessing consistency. However, the selected rolling period should match your investment horizon and the fund category.
Check risk-adjusted performance
Risk-adjusted measures examine how much return a fund generated for the risk it took. Compare these measures only among similar funds and over matching periods.
Common measures include:
- Standard deviation: Standard deviation measures how widely returns have moved around their average. A higher figure indicates greater historical fluctuation.
- Beta: The beta of a mutual fund measures how its returns have moved relative to the benchmark. A beta above 1 indicates greater historical sensitivity to benchmark movements.
- Alpha: Alpha estimates the return above or below what the fund’s benchmark-related risk would suggest. A positive alpha indicates estimated risk-adjusted outperformance, but it can change with the period and model used.
- Sharpe ratio: The Sharpe ratio compares excess return with total volatility. A higher positive value indicates more historical excess return per unit of total risk.
- Treynor ratio: The Treynor ratio compares excess return with systematic risk, measured through beta.
These figures are based on historical data. They should support your assessment, not replace an examination of the scheme’s objective, portfolio, and risks.
Review costs and portfolio quality
The Total Expense Ratio (TER) covers expenses charged to a mutual fund scheme. The daily Net Asset Value (NAV) reflects these expenses. A higher TER can reduce the return you receive, but the lowest TER does not automatically identify the right fund.
Review portfolio concentration, asset allocation, credit quality for debt funds, and sector exposure for equity funds. A concentrated portfolio can produce substantial gains, but it can also increase losses when a major holding or sector performs poorly.
Portfolio turnover shows how frequently holdings change. A high or low ratio is not automatically favourable. Interpret it in the context of the scheme’s strategy.
Examine the fund manager and strategy
A change in the fund manager’s role can affect how an actively managed scheme operates. Review the manager’s tenure, the investment process, and whether the scheme’s portfolio style has changed.
Do not judge a manager only by short-term returns. Performance can also result from market conditions, sector exposure, credit decisions, or the investment style being temporarily favourable.
Fund-manager assessment has less relevance for a passive fund. For an index fund, tracking difference, tracking error, costs, and replication method deserve greater attention.
How often should you review performance?
Reviewing your mutual fund portfolio once every 6 to 12 months can help you monitor progress without reacting to every market movement. You should also review it after a change in your financial goal, investment horizon, or risk capacity.
One weak quarter does not always justify redemption. First check whether the underperformance is persistent, whether comparable funds faced similar conditions, and whether the scheme’s mandate or management changed.
Reviewing performance also helps you monitor diversification and asset allocation. Rebalancing may be necessary when market movements cause one asset class to occupy a much larger portfolio share than planned.
What can performance data not tell you?
Past performance cannot tell you what a mutual fund will return in future. It also cannot determine whether a scheme matches your financial goal or whether you can tolerate its possible losses.
Before making a decision, consider factors that performance figures do not settle:
- Your goal and required investment period
- Your ability to handle market falls
- The scheme’s investment objective and Riskometer
- Exit load, taxation, and liquidity requirements
- Portfolio overlap with your existing investments
A scheme that performed well may still be unsuitable if its risk level, strategy, or investment horizon does not match your needs.
Conclusion
Checking mutual fund performance requires more than reviewing recent returns. Compare the scheme with its benchmark and similar funds over matching periods. Also assess rolling returns, risk-adjusted measures, costs, portfolio quality, and management consistency. These checks help you decide whether an investment still suits your goal, time horizon, and risk tolerance. You can explore mutual fund schemes through the Bajaj Broking website after this review. Remember, past performance does not predict future returns.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Performance and risk evaluation
Returns and comparison
How does tracking error affect the evaluation of an index fund?
Lower tracking error indicates more consistent benchmark replication. Compare index funds tracking the same index using both tracking error and tracking difference.
Why can a fund with higher returns still have higher investment risk?
A fund can generate higher returns by taking greater exposure to volatile assets, concentrated sectors, or other higher-risk investments. Higher past returns do not necessarily indicate lower risk or future performance. Investors should evaluate returns alongside volatility, portfolio concentration, downside risk, and the fund's investment strategy.
Can a mutual fund with lower returns be a better choice?
Yes. A fund with lower returns can be more appropriate if it took less risk, showed smaller losses during market falls, or matched your investment horizon more closely. Compare its benchmark, volatility, portfolio, costs, and investment objective. Return alone does not show whether the scheme suits your goal. You should also check the scheme’s Riskometer before investing.
Should I redeem a fund that underperforms for one year?
One year of underperformance does not automatically justify redemption. Compare the scheme with its benchmark and similar funds over longer, matching periods. Check whether the manager, mandate, costs, or portfolio style changed. You should consider redemption only after examining persistent underperformance, your goal, tax implications, exit load, and available alternatives.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.