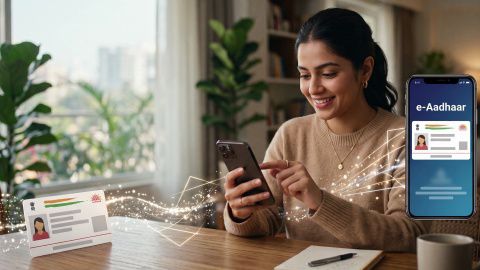
A digital Aadhaar helps with a loan because you can upload or share it for KYC without scanning a paper copy. Matching details across Aadhaar, Permanent Account Number (PAN) and your bank account make verification smoother.
Worked example: Kavitha in Vijayawada
Kavitha is 33 and works as a salaried pharmacist in Vijayawada. She earns Rs. 72,000 a month and has a CIBIL score of 760. She uses her digital Aadhaar for KYC and borrows Rs. 2.2 lakh for a home renovation, at an illustrative 15% per annum. She compares the equated monthly instalment (EMI) over 2 tenures.
EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. P is the loan amount in rupees, R is the annual rate divided by 12 and by 100, and N is the tenure in months. The formula spreads the principal and interest into equal monthly payments, so early EMIs carry more interest and later ones more principal. All figures are rounded to the nearest rupee.
| Tenure | Monthly EMI (Rs.) | Total interest (Rs.) | EMI as share of salary (%) |
|---|
| 24 months (2 years) | 10,667 | 36,010 | 14.8 |
| 36 months (3 years) | 7,626 | 54,549 | 10.6 |
Last updated: 19th October, 2026
The 36-month option lowers the EMI by Rs. 3,041 but adds Rs. 18,539 in interest. The processing fee on Rs. 2.2 lakh is up to Rs. 9,086. Kavitha picks 24 months (2 years), and her digital Aadhaar details already match her bank records.
What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.
Using your digital Aadhaar for KYC? With a Bajaj Finance Personal Loan, you can borrow Rs. Rs. 40,000 to Rs. Rs. 55 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online in about 5 minutes → receive funds within 24 hours* of approval.