








Real Estate Investment Trusts (REITs)
-
In summary
REITs provide a market-linked way to invest in income-generating real estate through units traded on a stock exchange.
- REITs pool funds from multiple investors.
- They primarily invest in income-generating properties.
- Investors can buy units through a Demat and trading account.
- Returns may include distributions and unit-price appreciation.
- At least 90% of net distributable cash flows must be distributed.
- At least 80% of assets must generally be completed and revenue-generating.
- REIT unit prices can rise or fall.
- The tax treatment depends on the distribution component.
- Returns are not fixed or guaranteed.
Investors can generally buy one listed REIT unit.
Investors should examine the property portfolio, occupancy, tenants, debt, distributions, and management quality before investing.
-
What are REITs?
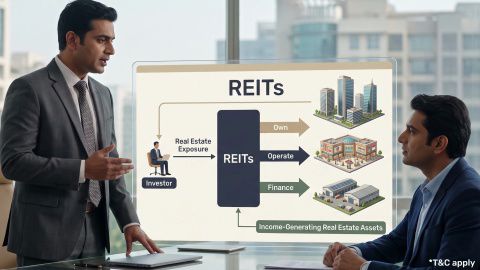
A Real Estate Investment Trust is a trust registered with the Securities and Exchange Board of India. It raises money from investors and invests primarily in income-generating real estate assets.
These properties may include:
- Office buildings
- Business parks
- Shopping centres
- Warehouses
- Logistics facilities
- Hotels
- Data centres
Investors receive units representing their interest in the REIT.
These units can be bought and sold on a recognised stock exchange, subject to market availability and applicable trading rules. A REIT may earn money through rent, property-related income, interest, and other permitted sources. It can distribute part of these cash flows to its unitholders. Investors may also earn a capital gain if they sell their units at a price above the purchase price.
However, neither distributions nor capital gains are guaranteed.
If you want property income but prefer predictability, combine REIT exposure for market-linked income and a Bajaj Finance FD for guaranteed returns up to 8.15% p.a. — a balanced approach. Open FD.
Also Read: FD Vs Real Estate
Why would somebody invest in REITs?
Avoid these mistakes while booking FD
-
REITs may appeal to investors who want exposure to real estate without purchasing and managing an entire property.
Some common reasons include:
- Lower investment requirement: Investors can access commercial real estate by buying listed units.
- Periodic distributions: Income-generating properties may support distributions to unitholders.
- Exchange liquidity: Listed units can generally be bought or sold during market hours.
- Professional management: The REIT manager handles leasing, maintenance, financing, and property operations.
- Portfolio diversification: REITs can provide exposure to real estate alongside other investments.
- Regulatory disclosures: Listed REITs must publish financial, operational, valuation, and portfolio information.
Possible capital appreciation: Unit prices may rise when property income, asset values, or market demand improve.
These features do not remove investment risk. Distributions can change, and market prices can fall below the investor’s purchase price.
Advantages of investing in REITs
-
REITs can provide the following advantages:
- Real estate access: Investors can gain exposure without purchasing a complete property.
- Income opportunity: Rental and other property-related cash flows may support periodic distributions.
- Diversification: One REIT may own multiple properties across different locations.
- Liquidity: Listed units are generally easier to sell than a physical property.
- Professional management: Experienced managers oversee tenants, leases, maintenance, financing, and acquisitions.
- Published valuations: REITs must disclose prescribed valuations and financial information.
- Smaller entry amount: Investors can buy units according to the applicable market price.
- No direct property management: Investors do not have to find tenants or maintain the underlying buildings.
However, distributions and market prices depend on the REIT’s performance and wider market conditions.
-
How does a company qualify as a REIT?
A REIT must be established as a trust and registered with SEBI. It must comply with the SEBI (Real Estate Investment Trusts) Regulations, 2014, as amended.
Important requirements generally include:
- The REIT must have a sponsor, manager, and trustee.
- At least 80% of the value of its assets must generally be invested in completed and revenue-generating properties.
- The remaining portion can be invested only in permitted assets.
- At least 90% of net distributable cash flows must be distributed to unitholders.
- Listed REITs must meet public unitholding requirements.
- Properties must undergo prescribed valuations.
- The REIT must provide financial and operational disclosures.
- Borrowing and deferred-payment limits apply.
- Certain transactions and borrowing levels require unitholder approval.
These requirements distinguish an Indian REIT from an ordinary property company.
What are the different types of REITs?
REITs may be classified according to their investment structure and availability.
Equity REITs
Equity REITs own or control income-producing properties. They primarily earn income through rent and related property operations. Indian public REITs mainly follow an income-producing real estate model.
Mortgage REITs
Mortgage REITs primarily invest in property loans or mortgage-backed securities. Their income generally comes from interest rather than direct property rent. This category is more common in some overseas markets.
Hybrid REITs
Hybrid REITs combine direct property ownership with investments in real estate debt.
Publicly listed REITs
Listed REITs trade on recognised stock exchanges. Retail investors can buy and sell their units through a Demat and trading account.
Private REITs
Private vehicles are not traded on public stock exchanges. Their eligibility, liquidity, disclosures, and investment requirements may differ significantly from listed REITs. Investors should not assume that every international REIT structure is available under the same conditions in India.
The regulatory framework for REITs in India
SEBI notified the REIT regulatory framework in 2014. The regulations cover registration, property investments, borrowing, valuation, disclosures, distributions, governance, and unitholder rights.
A typical Indian REIT has the following structure:
| Participant | Main responsibility |
|---|---|
| Sponsor | Establishes the REIT and supports the initial asset portfolio |
| Manager | Manages investments, properties, financing, and operations |
| Trustee | Monitors compliance and protects unitholder interests |
| Valuer | Conducts prescribed valuations of REIT assets |
| Unitholders | Invest money and hold units in the REIT |
Listed REITs must provide regular disclosures about occupancy, rental income, debt, property valuations, financial performance, and distributions. Regulation improves transparency but does not eliminate investment losses. Book FD.
Pros and Cons of investing in REITs
REITs provide access to income-generating real estate without requiring investors to buy and manage a complete property. However, their returns remain linked to property and market performance.
Pros
- Real estate access: Investors can access commercial properties without buying them directly.
- Distribution income: Rental and other cash flows may support periodic distributions.
- Professional management: The REIT manager handles leasing, maintenance, financing, and property operations.
- Liquidity: Listed REIT units can generally be bought and sold through a stock exchange.
- Diversification: A REIT may hold several properties across different locations and sectors.
Cons
- Market risk: Unit prices can rise or fall with market conditions.
- Occupancy risk: Vacancies or tenant defaults can reduce rental income.
- Variable distributions: The amount distributed to investors can change between periods.
- Debt risk: High borrowing and rising interest rates can affect cash flows and returns.
Management costs: Operating expenses and management fees can reduce distributable income.
Investors should assess both the property portfolio and financial position before investing.
Taxation regulations for Real Estate Investment Trusts (REITs)
REIT distributions can contain different components. Each component may receive different tax treatment.
- Interest income: Interest distributed by a REIT is generally taxable at the investor’s applicable income-tax rate.
- Dividend income: Tax treatment depends on the tax regime selected by the underlying special purpose vehicle. The REIT’s distribution statement shows the applicable component.
- Rental income: Rental income distributed directly by a REIT is generally taxable at the investor’s applicable rate.
- Debt repayment: A debt-repayment component may be taxable under specific rules and can affect the cost of the REIT units.
- Short-term capital gains: Gains from listed REIT units held for up to 12 months are generally taxed at 20% when the applicable securities transaction tax conditions are met.
- Long-term capital gains: Gains from listed units held for more than 12 months are generally taxed at 12.5% above the applicable aggregate exemption of Rs. 1.25 lakh.
Surcharge and cess may also apply. Investors should check the REIT’s distribution statement and consult a tax adviser for their individual tax position.
Also Read: What is a Vacation Account
Tips to assess Real Estate Investment Trusts
Review the following factors before investing in a REIT:
- Analyse the portfolio: Check the property type, location, age, quality, and sector.
- Review occupancy: Higher occupancy can support rental income, but compare it across several periods.
- Check the tenant mix: Heavy dependence on one tenant can increase risk.
- Study lease terms: Review lease duration, expiry dates, and rental escalation clauses.
- Review distributions: Compare the amount and components of past distributions.
- Evaluate debt: High borrowing or expensive debt can reduce distributable cash flow.
- Assess management: Examine the manager’s record, governance, acquisitions, and related-party transactions.
No single measure can confirm whether a REIT is suitable. Review its income, debt, properties, and market price together.
If a REIT’s yield profile looks attractive but you're unsure about market volatility, allocate a portion to FDs (steady interest, simple planning) while keeping REIT exposure for yield upside. Explore FDs.
Who should invest in REITs?
REITs may suit investors who want exposure to income-generating real estate without managing physical property. They may also suit those seeking possible periodic distributions and who can accept changes in unit prices and income. REITs may not suit investors who require assured returns or complete capital certainty. Such investors may consider Fixed Deposits separately. Before investing, assess your financial goals, investment period, income needs, and ability to accept market risk.
How do REITs generate returns for investors?
REIT investors may receive returns from two main sources.
Distributions
A REIT can pass cash flows from its assets to unitholders.
A distribution may include:
- Interest
- Dividend
- Rental income
- Repayment of debt
- Other permitted components
The total distribution should not automatically be described as a dividend.
Each REIT provides a distribution statement showing the amount and its components.
Capital gains
An investor may earn a capital gain by selling REIT units above their purchase price. For example, suppose an investor buys a unit for Rs. 350 and later sells it for Rs. 390. The gain before brokerage, taxes, and other charges is Rs. 40 per unit. The investor can also suffer a loss if the selling price falls below Rs. 350. The final return combines distributions, price movement, expenses, and applicable taxes.
How to Invest in Real Estate Investment Trusts?
Listed REIT units can be purchased through a Demat and trading account.
Follow these steps to invest:
- Open a Demat and trading account with a registered broker.
- Complete the required KYC process.
- Add money to your trading account.
- Search for the listed REIT using its exchange symbol.
- Review the unit price, portfolio, distributions, and risks.
- Place an order for the required number of units.
- Hold the purchased units in your Demat account.
You can also apply during a REIT public issue when a new REIT launches. Before investing, read the offer document, SEBI filings, valuation reports, financial statements, and property portfolio details.
Investors who also want assured returns not linked to market movements may separately consider a Bajaj Finance Fixed Deposit. Open a Fixed Deposit account.
Limitations of REITs
REITs provide access to income-generating real estate, but their returns and unit prices are not guaranteed. Consider the following limitations:
- Market-price fluctuations: REIT unit prices can rise or fall because of market movements, interest rates, and economic conditions.
- Dependence on occupancy: Vacant properties or tenant defaults can reduce rental income and distributions.
- Interest-rate sensitivity: Rising interest rates can increase borrowing costs and make other income-producing investments more attractive.
- Concentration risk: A REIT that depends heavily on one city, property type, or tenant may face greater risk.
- Variable distributions: The amount distributed to investors can change based on rental income, expenses, debt, and cash-flow requirements.
- Tax considerations: Interest, dividend, rental, and debt-repayment components may receive different tax treatment.
- Debt exposure: High borrowing can increase financial pressure and reduce the cash available for distribution.
- Management and operating costs: Property expenses, administrative costs, and management fees can reduce distributable income.
REITs distribute a large part of their net distributable cash flows. However, this does not automatically mean that their unit prices have limited growth. Capital appreciation depends on factors such as rental growth, property values, acquisitions, debt, and market demand.
Conclusion
REITs allow investors to access income-generating real estate without buying or managing physical property. They may provide periodic distributions, diversification, and exchange liquidity. However, unit prices and distributions can change with occupancy, rental income, interest rates, debt, and market conditions. Review the REIT’s portfolio, tenants, finances, and tax treatment before investing. Choose investments that match your goals, investment period, and ability to accept risk.
Calculate your expected investment returns with the help of our investment calculators
Check out different FD Rates
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
What parameters are used to calculate interest on FD?
Parameters for FD interest calculation include the principal amount, tenure, the applicable interest rate, and the payout frequency.
How to calculate FD interest rate using an online calculator?
To calculate FD interest rate with an online calculator, input the type of customer (senior citizen or customer below the age of 60), principal amount, tenure, interest rate, and choose the compounding frequency (monthly, quarterly, annually) if applicable.
Why is it important to understand how fixed deposit interest is calculated?
Understanding FD interest calculation is crucial for estimating returns, comparing investments, and making informed financial decisions.
What is the difference between the calculation of simple interest and compound interest?
The main difference is that simple interest is calculated only on the principal amount, while compound interest includes interest on interest.
Is FD interest credited monthly?
FD interest can be credited monthly, quarterly, or annually, depending on the terms of the FD.
How does the FD interest rate work?
FD interest rate is the annual percentage return offered by the bank, and it determines the interest earned on the principal amount over the investment tenure.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.