Get life insurance with retirement plans at affordable premiums
Life cover + pension option | Guaranteed returns | Tax benefits
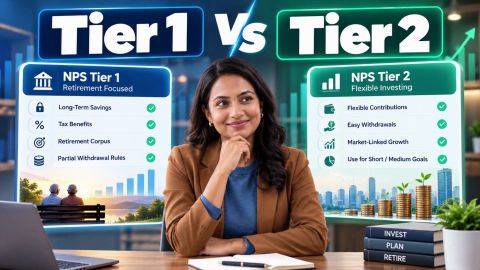
NPS Tier 1 vs Tier 2
In summary
NPS Tier 1 is the primary pension account for retirement savings. Tier 2 is an optional investment account that you can access more freely, but it generally does not provide tax benefits.
- You need an active Tier 1 account to open Tier 2.
- Under the All Citizen Model, eligible subscribers can generally join NPS between 18 and 85 years.
- Tier 2 withdrawals are allowed at any time; Tier 1 withdrawals follow PFRDA rules.
- At normal exit under current All Citizen rules, up to 80% can be withdrawn as a lump sum and at least 20% must be used to buy an annuity, subject to small-corpus exceptions.
- Tier 1 has specified tax benefits, depending on the tax regime and conditions. Ordinary Tier 2 does not offer general tax benefits.
- NPS returns are market-linked, not guaranteed.
NPS can form part of a broader retirement plan. A life-insurance annuity or pension policy may provide a separate income stream or complement the annuity purchased through NPS.
You can explore affordable retirement-linked life insurance options based on your needs.
What are NPS Tier 1 and Tier 2 accounts?
Think of them this way:
- Tier 1 is your main retirement account. It is designed to help you build a pension corpus over time. Withdrawals are allowed only under specified PFRDA rules.
- Tier 2 is an optional investment account. You can use it for additional savings and withdraw your money whenever you need it. You must have an active Tier 1 account to open Tier 2.
Tier 1 is a pension account, while Tier 2 is an investment account rather than a separate pension account. You can select different Pension Fund Managers and investment options for the two accounts.
How are Tier 1 and Tier 2 different?
Here is a comparison of the two accounts under the NPS All Citizen Model.
| Feature | NPS Tier 1 | NPS Tier 2 |
|---|---|---|
| Purpose | Primary retirement savings account | Optional investment and savings account |
| Account requirement | Main NPS pension account | Requires an active Tier 1 account |
| Withdrawals | Subject to PFRDA withdrawal and exit rules | Can withdraw at any time |
| Lock-in | Retirement-focused withdrawal rules apply; normal exit has a vesting period | No general withdrawal lock-in |
| Tax benefits | Eligible contributions can qualify for tax benefits, subject to conditions | No general tax benefits |
| Minimum initial contribution | Rs. 500 | Rs. 1,000 |
| Minimum contribution thereafter | Rs. 500 per contribution and Rs. 1,000 per financial year | Rs. 250 per contribution; no minimum balance |
| Investment options | Available NPS pension funds and investment choices | Available NPS pension funds and investment choices |
| Purpose at retirement | Builds your retirement corpus and pension income | Provides additional savings that can be withdrawn when needed |
The contribution figures above reflect the standard account requirements published by Protean, an NPS Central Recordkeeping Agency. Other NPS routes or sector-specific rules may have different requirements.
Note: Tier 2 does not replace Tier 1. You cannot open a regular Tier 2 account independently or use it as your main NPS pension account.
What do the two NPS accounts have in common?
Their main similarities include:
- Choice of Pension Fund Manager: You can select a PFRDA-registered Pension Fund Manager. You can also select different pension funds for Tier 1 and Tier 2.
- Investment choices: Both accounts offer investment exposure to equity, corporate bonds and government securities under applicable schemes.
- Active and auto choices: You can select your asset allocation yourself through Active Choice or use Auto Choice, where the allocation changes based on your age.
- Market-linked returns: The value of both accounts depends on the performance of the selected investments.
- Account portability and investment changes: You can exercise the fund and investment choices allowed under NPS rules.
You can change your Pension Fund Manager once a year and your asset allocation or investment choice up to four times a year under the applicable common-scheme rules.
How do withdrawals work in Tier 1 and Tier 2?
How can you withdraw money from Tier 1?
The withdrawal rules depend on when you leave NPS and the type of withdrawal you request.
For individual subscribers under the All Citizen Model, the current rules provide for the following:
| Withdrawal situation | Applicable rules |
|---|---|
| Normal exit | Generally after 15 years of subscription or reaching 60 years of age, whichever is earlier, subject to any higher scheme-specific vesting period |
| Lump sum at normal exit | Up to 80% of the accumulated corpus |
| Annuity at normal exit | At least 20% of the corpus must generally be used to purchase an annuity |
| Premature exit | Up to 20% can be withdrawn as a lump sum; at least 80% must generally be used to purchase an annuity |
| Partial withdrawal | Up to 25% of your own contributions for permitted purposes, subject to PFRDA conditions |
There are exceptions for smaller accumulated pension amounts. For example, a corpus of up to Rs. 8 lakh at normal exit can qualify for full withdrawal, while a corpus of up to Rs. 5 lakh at premature exit can qualify for full withdrawal under the applicable options.
Has the five-year lock-in rule changed?
Yes. PFRDA removed the five-year minimum subscription period for premature exit under the All Citizen Model. However, this does not mean that you can withdraw your entire Tier 1 corpus freely at any time. Normal and premature exits continue to have different conditions.
The withdrawal rules for Government and Corporate NPS subscribers may differ. Check the rules applicable to your NPS sector before making an exit decision.
Can you withdraw money from Tier 2?
Yes. Tier 2 allows you to withdraw your accumulated amount, either fully or partially, whenever you need it. There is no general retirement-age requirement for accessing this account.
You can also transfer money from Tier 2 to Tier 1 under the permitted one-way transfer facility.
One important condition applies: when you close your Tier 1 account, your Tier 2 account is also closed and its balance is paid to you or the relevant nominee or legal heir, as applicable.
Popular plans for you
What tax benefits apply to Tier 1 and Tier 2?
What tax deductions can you claim on Tier 1 contributions?
Under the Income Tax Act, 2025, eligible NPS contributions can qualify for deductions under the following provisions:
- Section 123: Eligible personal contributions to NPS can form part of the aggregate deduction of up to Rs. 1.5 lakh under Schedule XV. This deduction is available under the old tax regime, subject to the prescribed conditions.
- Section 124(3): You can claim an additional deduction of up to Rs. 50,000 for eligible personal NPS contributions, subject to conditions and without claiming the same contribution under Section 123.
- Employer contributions under Section 124(1) and (2): Eligible employer contributions can qualify for deductions up to 14% of salary for Central and State Government employers and 10% for other employers. For taxpayers under the new tax regime, the limit for other employers is also increased to 14%.
The Section 123 deduction and the additional personal-contribution deduction under Section 124(3) are not available under the new tax regime. The employer-contribution deductions under Section 124(1) and (2) are permitted under the new regime, subject to the applicable limits.
Does Tier 2 offer any tax benefits?
An ordinary Tier 2 account does not offer general tax deductions on contributions or special tax benefits on its investment gains.
There is a specific exception: eligible Central Government employees can open a Tier II Tax Saver account if they have an active Tier 1 account. This account has a three-year lock-in and may qualify for tax benefits under the applicable conditions. It is different from the regular Tier 2 account.
Tax laws are subject to change. BFL does NOT provide Tax/Investment advisory services. Please consult your advisors.
What are the NPS contribution requirements and charges?
For standard All Citizen accounts, the contribution requirements are:
| Contribution requirement | Tier 1 | Tier 2 |
|---|---|---|
| Initial contribution | Rs. 500 | Rs. 1,000 |
| Minimum amount per contribution | Rs. 500 | Rs. 250 |
| Minimum contribution per financial year | Rs. 1,000 | No minimum balance requirement |
| Minimum number of contributions per financial year | One | No minimum balance requirement |
The charges you pay depend on the services and intermediaries involved, such as the Point of Presence, Central Recordkeeping Agency, Pension Fund Manager and custodian.
Tier 2 transaction charges are the same as Tier 1. Avoid relying on older fixed percentages without checking the latest PFRDA charge schedule.
Are NPS returns guaranteed?
NPS contributions are invested across asset classes such as:
- Equity: Invests in shares and carries market risk.
- Corporate bonds: Invests in debt securities issued by companies.
- Government securities: Invests in securities issued by the Central or State Government.
You can choose your asset allocation through Active Choice or use Auto Choice, where the allocation changes according to your age.
The value of your NPS account can rise or fall with market conditions. Therefore, review your risk tolerance and retirement timeline before selecting an investment option.
How can life insurance retirement plans complement NPS?
NPS and life insurance retirement plans can support different parts of your retirement planning. NPS is a pension scheme regulated by PFRDA, while life insurance pension and annuity products are separate insurance contracts regulated by the Insurance Regulatory and Development Authority of India (IRDAI).
You do not need to choose one instead of the other. Depending on your retirement income needs, you can consider how they may work together.
How do life insurers support NPS subscribers?
At the time of an eligible NPS exit, the required portion of your Tier 1 corpus is used to purchase an annuity. This annuity provides regular pension payments according to the option you select.
The annuity is purchased from an Annuity Service Provider (ASP) empanelled with PFRDA. These providers are life insurers regulated by IRDAI.
Depending on the available options, an annuity may provide:
- Pension payments for the subscriber's lifetime.
- Pension payments that continue to the spouse after the subscriber's death.
- Return of the annuity purchase price to the nominee after the annuitant's death.
The pension amount depends on the annuity option, purchase amount, age and insurer selected.
Can you buy a separate life insurance retirement or annuity plan?
Life insurance retirement products may broadly include:
- Deferred annuity plans: You pay premiums or make contributions during an accumulation period. The annuity payments begin at a later date specified under the policy.
- Immediate annuity plans: You pay a lump sum premium, and the annuity payments begin according to the selected option and policy terms.
Some policies offer options such as a lifetime annuity, joint-life income or return of purchase price. These benefits are not identical across policies, so review the policy document and benefit illustration.
A separate life insurance retirement policy does not become part of your NPS account. It is an additional contract that you can evaluate for your retirement income requirements.
What should you compare before choosing one?
Check the annuity payout, whether it is guaranteed, the payment frequency, nominee benefits, surrender conditions and any applicable charges.
NPS itself does not provide a separate life insurance sum assured like a term insurance policy. If your family depends on your income, assess your life cover separately from your retirement savings.
You can explore life insurance retirement and annuity options to understand whether a separate income stream would complement your NPS benefits.
Which NPS account should you choose?
- Choose Tier 1 if you want to build a retirement corpus, can commit to the applicable withdrawal rules and want to use eligible tax benefits.
- Consider Tier 2 if you already have an active Tier 1 account and want an additional NPS investment account that allows withdrawals at any time.
- Consider both if you want to keep your core retirement savings in Tier 1 while maintaining a separate, more accessible investment balance in Tier 2.
If your retirement income needs extend beyond NPS, you can also evaluate a separate life insurance annuity or pension policy. Compare the benefits and conditions rather than treating it as a replacement for NPS.
Conclusion
Before choosing, consider your retirement timeline, income, withdrawal requirements and comfort with market-linked investments. Also remember that NPS does not guarantee returns or provide a separate life insurance sum assured.
A retirement plan can include NPS along with suitable life insurance protection or annuity options. Reviewing these needs together can help you plan for retirement income while keeping your family's financial protection in view.
Government and investment schemes
Explore more and stay informed
Frequently asked questions
NPS tier 1 vs tier 2
Which is better, NPS Tier 1 or Tier 2?
Neither account serves exactly the same purpose. Tier 1 is designed for retirement savings and has regulated withdrawal rules. Tier 2 is an optional investment account that provides greater access to your money. Your choice depends on whether retirement-focused savings or withdrawal flexibility is more important for your financial goals.
What is the tax benefit of NPS Tier 1?
NPS Tier 1 offers tax benefits under applicable provisions of the Income Tax Act. Depending on your eligibility and tax regime, deductions may be available for your own contributions and certain employer contributions. The exact benefit depends on your circumstances and applicable rules.
Can I withdraw money from NPS Tier 1 before age 60?
Yes. NPS Tier 1 allows partial withdrawals before age 60, subject to conditions. These include a minimum subscription period and specified purposes such as education, marriage, medical treatment, house purchase or construction, and other permitted needs.
What happens to NPS Tier 1 if the subscriber dies before age 60?
If an NPS Tier 1 subscriber dies, the accumulated pension wealth is generally paid to the nominee or legal heir, subject to the applicable NPS exit rules. The nominee can receive the amount as permitted under the rules, including applicable annuity provisions where relevant.
Can I open NPS Tier 2 without Tier 1?
No. You need an active NPS Tier 1 account to open a Tier 2 account. Tier 2 is an optional account that provides greater withdrawal flexibility. You can maintain both accounts and select investment options for each, subject to applicable NPS rules.
Are NPS returns guaranteed?
No. NPS returns are market linked, so they are not guaranteed. Your returns depend on factors such as the asset classes selected, investment allocation and market performance. The value of your NPS corpus can therefore rise or fall with market conditions.
Is NPS Tier 1 available under the new tax regime?
Yes, but tax benefits depend on the specific contribution and applicable provisions. The new tax regime generally allows fewer deductions than the old regime. Certain employer contributions to NPS can qualify for a deduction under the applicable provisions even when you use the new tax regime.
What is the minimum contribution for NPS Tier 1 and Tier 2?
The minimum contribution can depend on the type of NPS transaction and applicable account rules. Current PFRDA provisions should be checked before publishing a fixed minimum figure because contribution requirements and operational rules can change.