What Is a Personal Line of Credit? How It Works in India

What Is a Personal Line of Credit? How It Works in India

A personal line of credit is a sanctioned limit you can dip into whenever you need money, paying interest only on what you take. Repay, and the limit is available to draw again.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


In summary

A line of credit sits between a term loan and a credit card. Like a card, it has a limit you can use, repay and use again. Like a loan, it is meant for planned costs and repaid in instalments. Interest on the line of credit runs only on what you draw, for the days you hold it, which makes it suited to costs that arrive in stages. In India, it appears as Flexi personal loans, overdrafts and pre-sanctioned credit lines usable through UPI.


  • A limit you draw from as needed.
  • Interest only on the amount used.
  • Repay and redraw within the limit.
  • Suits costs that arrive in stages.

Expecting costs spread over months? Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.

How does a line of credit work?

The lender assesses you once and sanctions a limit. After that, a line of credit runs on your terms:

  • Drawdowns: You move money from the limit to your bank account when a bill falls due, in one go or in parts.
  • Interest on usage: On a line of credit, interest is charged only on the amount drawn, for the days it is outstanding. An unused limit costs no interest.
  • Repayment: You pay instalments that cover interest and principal, depending on the product. You can also pay back surplus funds early.
  • Redraw: Money you repay becomes available to draw again, within the limit and the product's terms.
  • Review: The lender can review the limit over the tenure, and some products reduce it on a set schedule.
Show More Show Less

How much interest does it save?

The savings from a line of credit come from not paying interest on money you do not need yet. Suppose the limit is Rs. 2.4 lakh and the illustrative rate is 14.25% per annum. Interest on the full amount would be about Rs. 2,850 a month. If you draw only Rs. 1.2 lakh for 3 months, the interest for that period is about Rs. 4,275 in total. A term loan for the full Rs. 2.4 lakh would charge interest on all of it from day 1, used or not.

Show More Show Less

What forms does it take in India?

A line of credit appears in 4 products, each with its own rules:

  • Flexi personal loans: A personal loan with a sanctioned limit, where you withdraw and part-prepay as needed, with interest charged on usage.
  • Overdrafts: A limit attached to a bank account, in most cases secured against a fixed deposit, salary or property.
  • Credit lines on UPI: The Reserve Bank of India (RBI) allowed banks to offer pre-sanctioned credit lines that you can spend through UPI apps, like a small revolving loan.
  • Credit cards: A revolving limit too, but meant for spending, with a short interest-free period and high interest on any balance carried.
Show More Show Less

How does it compare with a loan or card?

The right product depends on how the cost arrives and how you plan to repay. The table compares the 3.


PointLine of creditTerm loanCredit card
How you get the moneyDraw as needed, up to a limitFull amount on day 1Spend up to a limit
InterestOnly on the amount drawnOn the full amount from day 1None if paid in full by the due date; high if a balance is carried
RepaymentInstalments, with the option to repay and redrawFixed instalments over a set tenureMinimum due each month
SuitsCosts that arrive in stagesA single, known costDay-to-day spending cleared each month

Last updated: 27th October, 2026


A line of credit is not automatically cheaper. Its rate may differ from a term loan's, and some products carry a maintenance charge, so compare the full cost in the Key Fact Statement against how you expect to use the limit.


Vivek's staged fees

Vivek, 37, leads automotive design at a Pune firm, with Rs. 83,000 in monthly salary and a CIBIL score of 772. His wife's executive MBA fees of Rs. 2.4 lakh were due in 4 instalments over a year, which suited a line of credit. Before choosing, he priced a term loan for the full amount at an illustrative 14.25% per annum, with the equated monthly instalment (EMI) worked out for 24 and 36 months.


EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. Here P = Rs. 2,40,000, R = 14.25 ÷ 1,200 and N = months.


TenureMonthly EMI (Rs.)Total interest (Rs.)EMI as share of salary (%)
24 months (2 years)11,55137,23513.9
36 months (3 years)8,23256,3459.9

Last updated: 27th October, 2026


A term loan would have charged interest on the whole Rs. 2.4 lakh from day 1. By drawing each fee instalment only when it fell due, Vivek paid interest on a much smaller balance in the first year. Processing on either route would cost up to Rs. 9,912, so the line of credit saved on interest alone.


What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.


Costs arriving in stages? With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.

Show More Show Less

What are the risks?

The flexibility that makes a line of credit useful also makes it simple to misuse:

  • Always-available money: A limit that is always there can tempt spending you would never borrow for otherwise.
  • Debt that never ends: On a line of credit, repaying and redrawing can keep you in debt for years without a clear end date.
  • Rate and limit changes: Some products have variable rates or a limit that falls on a schedule. Read the terms.
  • Charges: Annual or maintenance charges can apply even in months you draw nothing.
Show More Show Less

How do you use a line of credit well?

  • Draw on the day a bill is due: Interest starts the moment money leaves the limit.
  • Repay surplus at once: If you drew more than you needed, put it back the same week.
  • Set an end date: Decide when the planned costs end, and clear the balance by then.
  • Track it monthly: Check the drawn balance and available limit on your line of credit each month.
Show More Show Less

Is there a personal loan that works this way?

Yes. A Bajaj Finance Personal Loan is available in Flexi variants, which let you withdraw from a limit and part-prepay as needed, with interest on the amount used. Limits range from Rs. 40,000 to Rs. 75 lakh over 12 months to 108 months, for Indian nationals aged 21 years to 80 years with a CIBIL score of 650 or higher.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

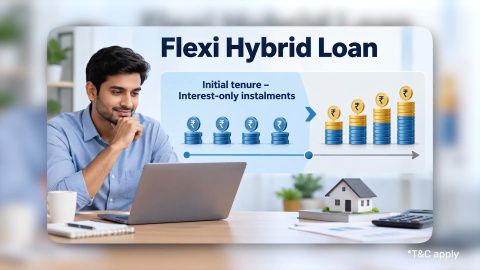
  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Understanding the product

Choosing

What is a personal line of credit?

It is a sanctioned limit you can draw from as needed, repay and draw again, with interest charged only on the amount used. It fits expenses spread over time, like fees due in instalments or a renovation. In India, a line of credit is offered as Flexi personal loans, overdrafts and pre-sanctioned credit lines on UPI.

No. Both are revolving, but a credit card is meant for everyday spending, with an interest-free period if you pay in full and high interest on any balance carried. A line of credit is meant for higher planned costs, with interest only on what you draw and repayment in instalments.

It can be, if your costs arrive in stages, because you pay interest only on what you draw. For a single cost paid on day 1, a term loan is the simpler choice. Compare the rate, charges and total cost in the Key Fact Statement for the way you will use the money.

Anyone who finds an available limit hard to leave alone. If a standing limit tempts you to draw for everyday spending, a fixed-term loan with a clear end date is safer. A line of credit works when there is a plan for each drawdown and a date by which the balance will be cleared.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000