







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
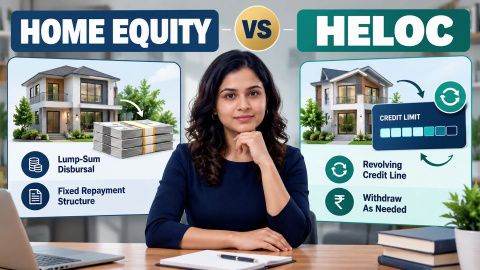
Home Equity Loan vs HELOC
In summary
A HELOC and a home equity loan allow eligible homeowners to access financing secured against property, but their structures differ. A HELOC operates through a credit limit, while a home equity term loan provides a sanctioned loan amount.
- HELOC stands for Home Equity Line of Credit.
- A HELOC permits withdrawals within an approved limit during the agreed availability period.
- A home equity term loan follows a defined disbursal and repayment schedule.
- Interest calculation depends on the actual product terms, including the amount drawn and outstanding.
- A house valued at Rs. 80 lakh with Rs. 30 lakh in secured borrowing has Rs. 50 lakh in estimated equity.
- Bajaj Finance offers eligible home loan balance-transfer customers a top-up facility of up to Rs. 1 crore* or higher.
Neither home equity nor a credit limit guarantees loan approval. Compare the financing structure, repayment cost and property-related risks before borrowing.
What is a HELOC?
A Home Equity Line of Credit is a credit facility secured against a residential property that lets the borrower draw funds up to an approved limit.
Under a revolving arrangement, repaid amounts can be withdrawn again during the permitted draw period, subject to the credit agreement. For example, a homeowner with a sanctioned limit of Rs. 15 lakh can draw Rs. 5 lakh for an approved expense instead of withdrawing the full limit immediately.
The interest calculation depends on the facility's actual outstanding amount and pricing terms. This is different from assuming that the entire Rs. 15 lakh has been disbursed as a loan.
HELOC is an internationally recognised product term. In India, homeowners should examine the actual overdraft, flexible secured-credit or other property-backed facility offered by their lender. A product described as flexible credit should not be assumed to provide every feature of a HELOC.
Show more
Show less
What is a home equity loan?
A home equity loan is a term-loan arrangement in which eligible property equity forms part of the security and lending assessment.
The borrower receives the sanctioned funding according to the disbursal conditions and repays it over an agreed period. For example, a homeowner may obtain a property-backed loan for Rs. 12 lakh, with repayments calculated using the sanctioned principal, interest rate and tenure.
The arrangement differs from a revolving line because it does not automatically allow the borrower to redraw principal already repaid. A home equity loan does not automatically carry a fixed interest rate. The interest-rate structure depends on the lender's approved product.
In India, a homeowner must identify whether the proposed facility is a loan against property, an eligible home loan top-up or another secured product. These facilities have different purposes and approval conditions.
Show more
Show less
How does a HELOC differ from a home equity loan?
The central difference concerns access to borrowed funds and repayment structure.
| Feature | HELOC | Home equity term loan |
| Credit structure | Approved revolving credit limit | Sanctioned term-loan amount |
| Access to funds | Draws within the permitted limit | Disbursal under the loan agreement |
| Reborrowing | Permitted during the agreed draw period | Not automatic |
| Interest | Based on contractual pricing and outstanding utilisation | Based on the agreed loan balance and pricing |
| Repayment | Draw and repayment conditions apply | Scheduled term-loan repayments |
| Main consideration | Flexibility and credit discipline | Predictable funding requirement |
These descriptions identify the structures rather than guarantee particular interest rates or draw periods. For example, a facility with a variable interest rate can become more expensive if the applicable benchmark changes. A term loan with a floating rate can also experience an EMI or tenure adjustment. The sanction letter determines the actual repayment obligations.
Show more
Show less
How do you calculate equity in your property?
Home equity is the difference between the property's estimated value and the debt secured against it.
Home equity = Estimated property value − Outstanding secured borrowing
Consider Raj, a 38-year-old salaried professional in Pune. His residential property has an estimated market value of Rs. 80 lakh. He has Rs. 30 lakh outstanding on the home loan secured against it.
His estimated equity is:
Rs. 80 lakh − Rs. 30 lakh = Rs. 50 lakh.
This calculation describes the homeowner's estimated net interest in the property. It does not mean Raj can borrow Rs. 50 lakh.
A lender must assess the property's accepted value, existing charges, permitted lending limits, Raj's income and repayment capacity. If the property has another secured loan, its outstanding amount must be considered in the relevant equity assessment.
Show more
Show less
Home loan for professionals
How much of your home equity can you borrow?
The sanctioned amount depends on the lender's product, property valuation, existing secured debt and borrower eligibility.
A lender uses the relevant loan-to-value (LTV) assessment to establish the proportion of accepted property value represented by secured borrowing.
LTV = Relevant secured borrowing ÷ Accepted property value × 100
For Raj's existing Rs. 30 lakh home loan against an Rs. 80 lakh property, the ratio is 37.5%. That is a description of his current debt position, not an approved additional borrowing limit.
If Raj requests more financing, the lender must assess the revised total secured exposure. Income, existing EMIs, credit profile, loan purpose and property documents also influence the decision. Therefore, the most useful first step is to establish the exact amount required rather than request the entire estimated equity.
Show more
Show less
When does a revolving facility make financial sense?
A revolving facility suits a borrowing requirement involving separate withdrawals over an extended period, provided the borrower can control usage and repayments.
Consider a homeowner planning property repairs in three stages. The contractor expects payments of Rs. 3 lakh, Rs. 2 lakh and Rs. 1 lakh at different milestones. A credit line permits the homeowner to draw funds according to the agreed availability terms.
However, the actual cost depends on the facility's interest rate, utilisation, charges and repayment conditions. A revolving limit is not an additional source of income. Every withdrawal increases the amount to be repaid.
Borrowers should also check whether unused-limit charges, renewal requirements or other contractual costs apply. The draw facility is beneficial only when its flexibility is worth the total borrowing cost.
Show more
Show less
When is a term loan more suitable?
A term loan provides a defined funding arrangement for an identified expense.
For example, a homeowner may need Rs. 12 lakh for a contractor-approved renovation project. If the full amount is required under the agreed disbursal schedule, a term loan allows the borrower to assess repayments against a specified principal and tenure.
The borrower should review whether the offered interest rate is fixed or floating. A fixed-rate loan provides rate certainty for its defined fixed-rate period, subject to the contract. A floating-rate loan remains exposed to its applicable reset provisions.
A term loan does not provide automatic redraw access after scheduled principal repayments. That distinction is important when the borrower anticipates additional expenses after the project begins.
Show more
Show less
How do interest and repayment costs compare?
The cost of either facility depends on interest rates, utilisation, tenure, disbursal, fees and repayment terms.
For a term-loan illustration, assume Rs. 12 lakh at 9.00% p.a. over 10 years. Using the standard monthly reducing-balance formula:
EMI = [P × R × (1 + R)^N] ÷ [(1 + R)^N − 1]
P represents the principal, R the monthly rate and N the number of monthly instalments.
The approximate EMI is Rs. 15,201, assuming a constant interest rate.
For a revolving facility, the monthly interest on an illustrative Rs. 5 lakh outstanding at 9.00% p.a. would be Rs. 3,750 using a simple one-month calculation. This is not necessarily the required monthly payment. A lender can prescribe principal repayments, daily-balance interest and other conditions.
The two illustrations cannot establish which product is cheaper without matching the actual draw schedule and repayment requirements.
Show More
Show Less
What risks should homeowners consider?
Both arrangements expose the homeowner to contractual repayment obligations.
The principal risks include:
- Property security: Default can lead to enforcement action against the secured property under the applicable law.
- Higher borrowing exposure: Additional funding increases the household's total debt.
- Interest-rate changes: Floating-rate products can become more expensive.
- Credit utilisation: Repeated withdrawals can extend the time needed to clear revolving debt.
- Long-term interest: Lower monthly repayments over a longer period can increase total interest.
- Additional charges: Processing, maintenance, renewal or other fees affect the total cost where applicable.
For Raj, the key question is whether his income can support the existing home loan plus the new repayment. He should calculate both commitments before accepting additional secured borrowing.
Show More
Show Less
What financing options are available in India?
Indian homeowners can compare actual secured-lending products rather than assume that a product named HELOC is available from every lender.
The relevant options include an eligible home loan top-up, a balance-transfer-linked top-up and a separately sanctioned loan against property. Each has its own eligibility, security and permitted-use conditions.
Bajaj Finance offers home loan balance-transfer facilities and top-up financing for qualifying borrowers. The maximum top-up amount is Rs. 1 crore* or higher and for eligible salaried balance-transfer applicants, interest rates start from 7.60% p.a.*.
These figures describe Bajaj Finance products and should not be presented as terms for a separate Bajaj Finance HELOC.
Show More
Show Less
How can you compare a balance transfer and top-up?
A balance transfer moves an eligible existing home loan to another lender under a new agreement. A top-up provides additional sanctioned borrowing where the applicant meets the relevant product requirements.
Before combining the two, calculate the future repayment cost of the current loan and the proposed replacement. Compare the new interest rate, remaining tenure, processing costs and required additional funding.
For example, Raj should first establish whether his existing home loan would become cheaper after transferring it. He should then evaluate the separate EMI and total interest arising from any top-up amount.
A lower advertised starting rate does not automatically establish savings. The decision must consider the full financing arrangement rather than the top-up amount alone.
Show More
Show Less
What documents do lenders assess?
The lender needs documents that establish the borrower's financial position and the property's suitability as security.
For Bajaj Finance home loan balance-transfer applications, the required records include Know Your Customer (KYC) documents, income evidence, relevant business information and property documents. Existing home loan statements and banking records support the assessment of outstanding liabilities.
For example, Raj should keep his current loan statement, title documents, recent bank statements and salaried income records ready. The lender then assesses repayment history, creditworthiness and property eligibility. Approval remains subject to the terms of the selected product.
Show More
Show Less
How should you decide before applying?
Begin with the amount you need, the date the funds will be required and the repayment schedule you can manage. Choose between a credit line and a term loan based on actual product availability, not terminology alone.
Then calculate the cost of existing debt, proposed additional borrowing and applicable fees. Raj should also preserve funds for emergencies and avoid using all available equity as borrowing capacity.
If he has an eligible existing housing loan, he can assess the Bajaj Finance home loan balance transfer and top-up facility.
If he is instead buying another residential property, he can check his Bajaj Finance Home Loan eligibility for that separate purchase.
A residential purchase home loan and a facility for withdrawing existing property equity serve different purposes.
Frequently Asked Questions
Credit structure and eligibility
Costs and practical borrowing
What is the main difference between HELOC and a home equity loan?
A HELOC provides access to funds within an approved revolving credit limit. A home equity term loan provides sanctioned funding under a defined loan agreement. A revolving facility can permit further withdrawals of repaid amounts during the allowed draw period. A term loan does not provide that automatic redraw feature. In both arrangements, the actual interest rate, security, fees and repayment conditions depend on the lender's approved product.
Can I borrow my entire home equity amount?
No automatic right to borrow the full estimated equity exists. A lender must assess the accepted property value, outstanding secured debt, applicable financing limits and repayment capacity. For example, a property worth Rs. 80 lakh with Rs. 30 lakh in secured borrowing has Rs. 50 lakh in estimated equity. That calculation does not establish that the lender will sanction an additional Rs. 50 lakh. The available amount can be lower.
Does a HELOC always have a floating interest rate?
No universal interest-rate structure applies to every facility described as a HELOC. The actual agreement determines the pricing mechanism, reset terms and payment obligations. Some revolving facilities use floating rates, while other arrangements have separate contractual conditions. Borrowers should review the sanction letter rather than assume that the product label determines the interest rate. The same principle applies to term loans, which must not be described as automatically fixed-rate products.
Do you pay interest on the full HELOC limit?
Interest calculation depends on the facility agreement. Under a drawn-balance arrangement, interest is charged on the amount utilised rather than simply the full sanctioned limit. For example, an illustrative Rs. 5 lakh outstanding at 9.00% p.a. produces Rs. 3,750 in one month's simple interest calculation. The actual charge can differ because of daily-balance methods, rates and applicable fees. The lender's statement determines the payable amount.
Is a home loan top-up the same as a HELOC?
No. A home loan top-up is additional borrowing sanctioned under an eligible housing-loan arrangement. A HELOC is a revolving credit facility secured against property equity. Their disbursal, repayment and redraw features differ according to the relevant agreements. Bajaj Finance offers eligible balance-transfer customers a top-up facility, but that does not establish a separate Bajaj Finance HELOC product. Compare the approved terms instead of treating the names as interchangeable.
Can additional property-backed borrowing put my home at risk?
Yes. Where the home secures a borrowing arrangement, failure to repay can result in contractual and legal enforcement against the security. The consequences depend on the facility, security documents and applicable law. Before taking additional financing, calculate the existing home loan EMI, new repayment commitment and household expenses together. A large estimated equity amount does not eliminate the need for sufficient income to meet scheduled payments.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.