








Types of Fixed Deposit: Features, Options & Comparison
-
In summary
Deposits allow individuals to keep money with financial institutions for daily transactions or savings. The main types include demand deposits and time deposits, each offering different levels of access to funds and interest earnings.
- Demand deposits allow money to be withdrawn when required, subject to account terms.
- Savings deposits help individuals keep money accessible while earning interest.
- Current deposits are generally used by businesses for frequent transactions.
- Time deposits hold money for a specified period and may offer a predetermined interest rate.
- Fixed deposits (FDs) and recurring deposits (RDs) are common types of time deposits.
The choice depends on how frequently the money may be needed, the intended savings period, and the terms offered by the financial institution.
What is a deposit?
Avoid these mistakes while booking FD
-
A deposit is money placed with a bank or another financial institution for safekeeping, savings, or financial transactions. Depending on the type of deposit, the money may remain accessible for everyday use or be held for a predetermined period to earn interest.
Deposits are broadly classified into demand deposits and time deposits. Demand deposits allow withdrawals when required, subject to account terms, while time deposits involve keeping money invested for a specified tenure. The interest rate, withdrawal conditions, and returns depend on the deposit type and the institution offering it.
What are the different types of deposits in India?
-
The main types of deposit accounts in India include savings accounts, current accounts, fixed deposits, and recurring deposits. Each option serves a different purpose, depending on whether the priority is convenient access to money, frequent transactions, or saving over time.
1. What is a savings deposit?
A savings deposit is money kept in a savings account, which generally earns interest while allowing account holders to access their funds when needed. These accounts are commonly used to manage everyday savings, maintain emergency funds, and receive salaries or other payments.
Key features:
- Interest is generally earned on the eligible account balance.
- Money can be accessed through permitted banking channels, such as ATMs, digital banking, and withdrawals.
- Banks may specify minimum balance requirements, transaction limits, or service charges.
- Interest rates and account conditions vary between banks.
A savings account may suit individuals who want to keep their money accessible while earning some interest.
2. What is a current deposit?
A current deposit is money held in a current account, which is primarily designed for businesses, traders, and other entities that need to make frequent financial transactions. Unlike savings accounts, current accounts generally do not pay interest, although the terms depend on the financial institution.
Key features:
- Supports frequent deposits, withdrawals, transfers, and payments.
- May offer cheque facilities and business banking services.
- May provide an overdraft facility, subject to eligibility and approval.
- Minimum balance requirements and transaction charges may apply.
Current accounts are generally suitable for businesses that need to manage regular collections, supplier payments, and operating expenses.
3. What is a fixed deposit (FD)?
A fixed deposit is a type of time deposit in which a lump sum is placed with a bank or non-banking financial company (NBFC) for a selected tenure. The deposit earns interest according to the agreed terms, and the principal and applicable interest are paid at maturity or through a chosen payout arrangement.
Key features:
- Offers a predetermined interest rate for the selected tenure, subject to the deposit terms.
- Allows depositors to choose from the tenures offered by the institution.
- May offer cumulative interest, paid at maturity, or non-cumulative interest, paid at regular intervals.
- Premature withdrawal may be permitted, subject to applicable conditions and penalties.
- Interest earned may be taxable under the applicable income tax rules.
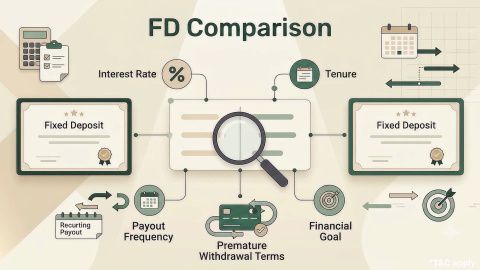
Fixed deposits may suit individuals who want to plan their savings over a defined period and know the applicable interest rate in advance. However, depositors should compare interest rates, tenure, withdrawal rules, and the institution's creditworthiness before investing.
4. What is a recurring deposit (RD)?
A recurring deposit allows individuals to save a fixed amount at regular intervals, usually monthly, for a predetermined period. The deposits earn interest according to the scheme's terms, and the accumulated amount is generally paid at maturity.
Key features:
- Encourages regular saving through periodic contributions.
- Allows individuals to start with instalment amounts specified by the institution.
- Offers a predetermined interest rate for the selected tenure, subject to scheme conditions.
- May have penalties or other conditions for missed instalments or premature closure.
Recurring deposits may be suitable for salaried individuals and others who want to save gradually rather than invest a large lump sum at once.
What is the difference between demand deposits and time deposits?
Demand deposits and time deposits differ mainly in how easily the money can be accessed and how interest is earned.
| Basis of comparison | Demand deposits | Time deposits |
|---|---|---|
| Meaning | Money kept in an account that allows withdrawals when required | Money deposited for a predetermined period |
| Examples | Savings accounts and current accounts | Fixed deposits and recurring deposits |
| Access to funds | Generally readily accessible, subject to account conditions | Access depends on the tenure and premature withdrawal rules |
| Interest | Usually lower than time deposits; current accounts generally do not earn interest | Depends on the deposit scheme, amount, and tenure |
| Primary purpose | Everyday banking and liquidity | Planned savings and interest earnings |
The choice between the two depends on when the money may be needed and whether easy access or a defined savings period is the priority.
What are the benefits of deposits?
Deposits can help individuals manage their money and plan their savings. Their benefits depend on the account type and the institution's terms.
- Convenient access to funds: Savings and current accounts support everyday transactions.
- Structured savings: Fixed and recurring deposits provide a defined savings period.
- Predictable interest: Deposits with predetermined interest rates make it easier to estimate returns, subject to the scheme's terms.
- Choice of deposit tenure: Some products offer different periods to match short-term and longer-term financial needs.
- Flexible interest payouts: Certain fixed deposits allow interest to be received periodically or at maturity.
- Potential borrowing facility: Some institutions allow eligible depositors to borrow against a fixed deposit, subject to applicable conditions.
Deposits should be evaluated according to liquidity needs, interest rates, fees, withdrawal conditions, and the financial strength of the institution.
Check out different FD Rates
How can you choose the right type of deposit?
Selecting a deposit depends on your financial goals, the amount available, and when you may need access to the money.
- Identify the purpose: Choose an account for everyday transactions or a deposit for planned savings.
- Assess liquidity needs: Keep money that may be needed immediately in an accessible account. Consider a time deposit for funds that can remain invested for the selected period.
- Compare interest rates: Check the rates offered for the relevant amount and tenure, along with the interest payout method.
- Review withdrawal conditions: Understand any restrictions, penalties, or charges that may apply to withdrawals or early closure.
- Check the institution's credibility: Review the institution's financial strength and applicable regulatory protections. Deposit insurance coverage differs by institution and product.
- Understand taxation: Interest earned on deposits may be taxable, depending on the applicable income tax rules and the depositor's circumstances.
Comparing these factors can help identify a deposit that aligns with your savings objectives and access requirements.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
What is the maximum deposit amount?
Limits depend on the account and issuer. Bajaj Finance Fixed Deposit accepts online investments from Rs. 15,000 to Rs. 3 crore.
What is the difference between mutual funds and bank deposits?
Bank deposits provide predetermined interest, while mutual fund returns depend on market performance. Mutual funds can experience gains or capital losses.
Why do your savings bank deposits actually result in a loss?
The balance earns interest, but purchasing power may decline when after-tax interest remains below inflation over the same period.
How do bank deposits help the nation’s economy?
Banks use deposits to support eligible lending, payments, and economic activity while maintaining regulatory liquidity and reserve requirements.
Which type of deposits earns higher interest rate?
Term deposits commonly offer higher rates than standard savings accounts. Actual rates depend on the issuer, tenure, amount, and customer category.
How many major types of deposit account are there?
There are two broad categories: demand deposits and time deposits. Savings, current, fixed, and recurring accounts fall within these categories.
Is TDS deducted on Bajaj Finance FD interest?
Yes, TDS is deducted on Bajaj Finance FD interest when total interest credited or paid during a tax year exceeds Rs. 10,000. TDS on FD interest is generally deducted at 10% when PAN is available. Eligible residents with nil estimated tax liability may submit Form 121 under the 2026 rules. This form replaces the earlier Form 15G and Form 15H declarations.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.