








In summary
Fixed Deposit Sweep In
-
In Summary
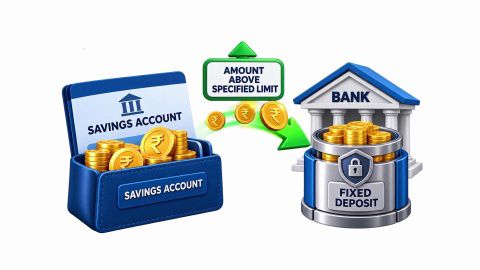
A fixed deposit (FD) sweep-in facility links a savings or current account to a fixed deposit, allowing surplus funds to earn FD interest while remaining accessible for eligible withdrawals. When the account balance exceeds a predefined threshold, the bank transfers the surplus to the linked FD. If the account balance later falls short of the amount needed for a payment, the required funds can be transferred back from the FD, subject to the bank’s rules.
Key points to know about an FD sweep-in facility:
- Automatic transfers: Surplus funds are moved into a linked FD when the specified balance threshold is crossed.
- Access to funds: Money can be transferred back to the linked account when required, subject to the applicable withdrawal rules.
- Interest earnings: The amount held in the FD earns interest at the applicable deposit rate.
- Flexible savings management: The facility can help balance short-term liquidity requirements with fixed deposit savings.
- Tax implications: Interest earned on the FD portion is generally taxable according to the applicable income tax provisions.
What is a fixed deposit sweep-in facility?
Avoid these mistakes while booking FD
-
A fixed deposit sweep-in facility is a banking feature that connects a savings or current account to a fixed deposit. It automatically transfers surplus money from the linked account into an FD when the balance exceeds a predetermined threshold.
Unlike a conventional FD, where the deposited amount is generally invested for a chosen tenure, a sweep-in arrangement allows eligible portions of the deposit to be withdrawn when the linked account needs funds. The remaining deposit continues to earn interest according to the applicable terms.
For example, a salaried individual may want to maintain Rs. 30,000 in a savings account for regular expenses while earning interest on any additional balance. A sweep-in facility can transfer eligible surplus funds into a linked FD without requiring the individual to initiate each transfer manually.
The facility is subject to the bank’s eligibility criteria, minimum balance requirements, transfer increments and withdrawal conditions.
How does an FD sweep-in facility work?
-
An FD sweep-in facility works through two automatic processes: sweep-in and sweep-out.
- Sweep-in: When the linked savings account balance exceeds the specified threshold, the eligible surplus is transferred into the fixed deposit.
- Sweep-out: When the savings account does not have enough funds to cover a payment, the required amount is transferred back from the linked FD, subject to the bank’s rules.
Example of an FD sweep-in facility
Suppose a savings account has a balance of Rs. 50,000, and the account holder has set a minimum balance threshold of Rs. 30,000.
The following example illustrates how the facility may work:
Particulars Amount Initial savings account balance Rs. 50,000 Salary credited Rs. 30,000 Balance after salary credit Rs. 80,000 Minimum balance threshold Rs. 30,000 Surplus potentially transferred to the FD Rs. 50,000 Balance retained in the savings account Rs. 30,000 The surplus amount of Rs. 50,000 is transferred to the linked FD, provided it meets the bank’s sweep-in conditions.
If the account holder subsequently needs Rs. 10,000 to pay a bill, the bank may transfer the required amount from the FD back to the savings account. The remaining deposit continues to earn interest under the applicable terms.
The actual transfer amount, sequence of withdrawals and interest calculation depend on the bank’s operating rules.
Also read: Right time to invest in a Fixed Deposit
What are the main components of an FD sweep-in facility?
The terms of a sweep-in FD differ across banks. The following table explains the main features to review before activating the facility.
| Parameter | Details |
|---|---|
| Linked account | Usually a savings or current account held with the same bank as the FD. |
| Threshold balance | The minimum balance to be retained in the linked account before surplus funds are transferred. |
| Transfer amount | Determined by the bank's rules, including eligible multiples or minimum transfer amounts. |
| Interest rate | Based on the applicable FD rate and the deposit's terms. |
| Tenure | Depends on the FD linked to the account and the bank's available tenure options. |
| Withdrawals | Eligible amounts can be transferred back to the linked account, subject to withdrawal conditions. |
| Eligibility | Depends on the bank's account types, deposit requirements and other applicable criteria. |
Before opting for the facility, account holders should confirm the minimum deposit amount, threshold requirements, tenure, interest calculation method and premature withdrawal rules with their bank.
What are the benefits of an FD sweep-in facility?
A sweep-in facility can help account holders manage surplus money without giving up access to funds entirely. Its main benefits include the following.
1. Potential to earn higher interest
Savings account balances generally earn interest at the applicable savings account rate. Money transferred into a sweep-in FD earns interest at the rate applicable to that deposit.
When the FD rate is higher than the savings account rate, the facility may improve the interest earned on surplus funds. The actual benefit depends on the interest rates, deposit tenure, frequency of withdrawals and applicable conditions.
2. Convenient access to money
A conventional FD may need to be closed or partially withdrawn to meet an unexpected expense. A sweep-in facility can allow eligible amounts to be transferred back to the linked account when funds are needed.
This can reduce the need to manually arrange a withdrawal, although the speed and availability of funds depend on the bank's procedures.
3. Automatic management of surplus funds
Once the facility is activated, eligible surplus funds can be transferred automatically. This reduces the need to monitor the savings account and create a separate FD every time the balance increases.
4. Flexibility for short-term financial needs
A sweep-in facility may be useful for individuals who maintain a buffer for household expenses, bill payments or other short-term requirements. It allows them to retain a specified balance in the savings account while placing eligible surplus funds in an FD.
5. Potential to retain interest on the remaining deposit
When only part of a sweep-in FD is withdrawn, the remaining balance may continue to earn interest. However, the interest on the withdrawn portion can be recalculated under the bank's premature withdrawal rules.
Account holders should check how partial withdrawals affect interest before relying on the facility for frequent transactions.
Check out different FD Rates
How can you apply for an FD sweep-in facility?
The application process varies by bank. Where the facility is available through internet banking, the general steps may be as follows:
- Log in to internet banking: Access the bank's official online banking service using the registered credentials.
- Find the FD section: Look for the fixed deposit, auto-sweep or sweep-in facility option.
- Select the accounts: Choose the eligible savings or current account and the FD to be linked.
- Set the threshold: Specify the balance to be retained in the linked account, if the bank permits a choice.
- Review the terms: Check the minimum transfer amount, FD tenure, interest rate, withdrawal conditions and any applicable charges.
- Confirm the request: Submit the request using the bank's prescribed authentication process.
Some banks may require activation through a branch or a separate service request. The facility may also be available only for specific account and deposit combinations.
What should you consider before choosing an FD sweep-in facility?
Although a sweep-in FD can help balance liquidity and interest earnings, its suitability depends on the account holder's financial needs and the bank's terms.
1. Minimum balance requirements
Check the minimum balance that must remain in the savings account and whether the bank requires a particular account type or deposit amount. A threshold that is too low may leave insufficient funds for regular expenses.
2. Interest rates and deposit tenure
Compare the applicable sweep-in FD rate with the savings account rate and other available deposit options. Check whether the deposit has a fixed tenure and how the bank calculates interest on funds withdrawn before maturity.
3. Premature withdrawal conditions
Do not assume that all sweep-in withdrawals are free of penalties. Some banks may apply a reduced interest rate or premature withdrawal penalty to the amount withdrawn. Review the applicable terms before activating the facility.
4. Sweep-in threshold
The threshold determines how much money remains available in the linked account before surplus funds are transferred to the FD. Consider regular expenses, standing instructions and upcoming payments when selecting this amount.
5. Sweep-out process and timing
Banks may differ in the minimum withdrawal amount, transfer increments, order in which deposits are used and time taken to make funds available. Understanding these rules can help avoid payment difficulties.
6. Auto-renewal and maturity rules
Check whether the linked FD renews automatically at maturity, whether the renewal terms can be changed and what happens to the deposit if the sweep-in mandate is discontinued.
7. Tax implications
Interest earned on the fixed deposit portion is generally taxable under the applicable income tax provisions. The tax treatment depends on the individual's circumstances and the rules in force. Any eligible deduction or exemption should be assessed separately.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
What is the difference between a sweep-in FD and a flexi deposit?
A sweep-in FD and a flexi deposit can both provide access to funds while allowing eligible money to earn interest. However, their structure and operation may differ.
| Basis | Sweep-in FD | Flexi deposit |
|---|---|---|
| Structure | Links an eligible savings or current account to an FD. | Generally combines a deposit with a facility for flexible deposits or withdrawals, depending on the product. |
| Transfer of surplus money | Eligible surplus is transferred automatically when the threshold is crossed. | Additional deposits may need to be made manually or according to the product's specific rules. |
| Access to funds | Eligible amounts may be transferred back to the linked account when needed. | Withdrawal flexibility depends on the product's terms. |
| Threshold | Usually operates according to a specified account balance threshold. | May follow a different deposit or withdrawal structure. |
| Account setup | Requires an eligible linked account and FD. | May be offered as a separate deposit product or under a specific bank arrangement. |
The names and features of these facilities are not standardised across all financial institutions. Reviewing the product terms is important before comparing them.
Conclusion
An FD sweep-in facility can be useful for individuals who want surplus savings to earn fixed deposit interest while keeping funds accessible for eligible transactions. By automatically moving money between a linked account and an FD, it can reduce manual effort and help manage short-term liquidity needs.
However, the benefit depends on the applicable interest rate, withdrawal rules, minimum balance requirements and frequency of withdrawals. Account holders should review these conditions before activating the facility.
A sweep-in facility is different from a standalone fixed deposit. Those looking for a separate fixed-return investment may also compare corporate fixed deposits, including the Bajaj Finance Fixed Deposit, by reviewing the applicable interest rates, tenure options, payout frequency, eligibility and premature withdrawal conditions. The appropriate choice depends on individual liquidity needs and financial objectives.
Locate to your nearest FD branch

Related Articles
Frequently Asked Questions
Overview
What is FD sweep-in?
An FD sweep-in links an eligible bank account with a Fixed Deposit. Surplus money moves into the deposit, while required funds can return automatically.
Is it possible to get a sweep-in with repeated deposits?
Yes, some banks create multiple deposit units whenever the account balance crosses the specified threshold. Transfer frequency and minimum amounts depend on bank rules.
Can anyone with an existing Fixed Deposit avail of the sweep-in facility?
Understanding FD interest calculation is crucial for estimating returns, comparing investments, and making informed financial decisions.
What is a sweep-in facility for FD?
It is an automated facility that transfers surplus bank-account funds into an FD. It can also return eligible funds when the account balance becomes insufficient.
Is there any penalty in a sweep-in FD?
A bank may reduce interest or apply premature withdrawal conditions to the withdrawn deposit portion. Customers should check the applicable policy before activation.
Can I withdraw money from sweep FD?
Yes. The bank can transfer the required amount from the sweep FD to the linked account. Withdrawal units and interest adjustments depend on the bank’s terms.
Is sweep-in FD taxable?
Yes. Interest earned on a sweep-in FD is taxable according to your applicable income tax slab. TDS may apply when interest crosses the prescribed threshold.
What is the disadvantage of a sweep-in FD?
Frequent withdrawals can reduce your interest earnings. Banks may also apply premature withdrawal conditions or transfer funds only in specified units.
What is the Fixed Deposit sweep-in meaning?
A Fixed Deposit sweep-in facility links an FD with a savings or current account. It automatically transfers funds from the FD when the linked account has insufficient balance.
How is a sweep-in FD account different from a regular FD?
A sweep-in FD provides automated access through a linked bank account. A regular FD remains separate and usually requires a withdrawal request before maturity.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.