







Health insurance goes beyond hospitalization—it covers OPD visits, medicines, ambulance charges, preventive checkups, and even alternative treatments, giving you all-around financial security.

- Compare plans from leading insurers in one place
- Premiums starting from Rs. 9.3/day*
- Pay premiums conveniently with Easy EMI options
- High sum insured options at affordable premiums
- Cashless treatment across a wide network of hospitals
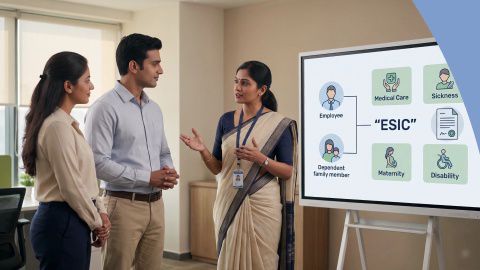
ESIC - Employees' State Insurance Scheme Explained
In Summary
The ESI scheme functions as a foundational social safety net for India's workforce, combining health security with cash compensation during medical emergencies.
- Wage eligibility ceiling: Applies mandatorily to employees earning gross monthly wages up to Rs. 21,000 (Rs. 25,000 for persons with disabilities).
- Contribution rates: Governed by statutory ratios where the employee contributes 0.75% of wages and the employer contributes 3.25%, totaling 4.0% deposited with ESIC.
- Comprehensive medical coverage: Provides full, uncapped medical care for the insured employee and their dependents from Day 1 of entering insurable employment.
- Cash compensation benefits: Delivers wage-replacement benefits for temporary disablement (90% of wage), maternity leave (100% of wage for 26 weeks), and sickness leave (70% of wage).
Bridge your healthcare coverage gaps: view plans on Bajaj Finance to compare affordable retail health insurance policies with wide cashless private hospital networks.
What is the Employee's State Insurance Act of 1948?
The Employee’s State Insurance Act of 1948 is landmark Indian labour legislation designed to provide social security and financial protection to employees in organized factories, commercial establishments, and services. Administered by the Employees’ State Insurance Corporation (ESIC)—a statutory body under the Ministry of Labour and Employment—the scheme operates on a self-financing, contributory insurance model. Both employers and employees contribute monthly toward a centralized social security fund, which finances medical treatments, hospitals, dispensaries, and cash cash-benefit disbursements. Comprehensive health insurance and retail insurance products complement this framework.
Did You Know? (Wage ceiling limit)
The statutory wage limit for ESI coverage is Rs. 21,000 per month (and Rs. 25,000 per month for employees with certified disabilities). If an employee’s monthly wage crosses Rs. 21,000 during an active contribution period, they continue to remain covered under ESI until the end of that specific contribution period (either March or September).
Quick Fact: Statutory contribution breakdown
Under current ESIC regulations, the employee contribution is set at 0.75% of gross wages, while the employer pays 3.25%, totaling 4.0%. Employees earning an average daily wage of up to Rs. 176 are completely exempt from paying their 0.75% share, though employers must still contribute.
Employees’ State Insurance Scheme (ESIS): Overview
The ESI scheme provides an integrated safety net shielding workers against physical and financial distress caused by sickness, maternity, employment injury, temporary or permanent disablement, occupational disease, and death:
- Dual structure: Combines direct clinical healthcare delivery through dedicated ESI hospitals and dispensaries with statutory cash benefit disbursements directly into workers' bank accounts.
- Family inclusion: Medical care covers the insured worker, spouse, dependent parents (whose combined monthly income does not exceed statutory limits), and dependent children up to age 21 (or 25 if studying; unmarried daughters until marriage).
- Nationwide mobility: Insured persons hold a unique Pehchan identity card with an ESIC Insurance Number, allowing them to access ESI dispensaries and hospitals across any state in India.
Where is ESIC applicable?
The ESI Act applies across designated geographical areas notified by the Central Government:
- Non-seasonal factories: Employing 10 or more persons, regardless of whether power is used in manufacturing processes.
- Commercial establishments: Shops, hotels, restaurants, road transport organizations, cinemas, newspaper establishments, and educational or medical institutions employing 10 or more persons (20 or more in select states).
Features and benefits of Employees’ State Insurance Scheme
The ESI scheme provides an expansive portfolio of clinical and cash compensations:
- Medical benefit: Comprehensive, uncapped outpatient and inpatient clinical care provided through ESI dispensaries, diagnostic centers, and tertiary tie-up hospitals.
- Sickness benefit: Cash payment equivalent to 70% of average daily wages for up to 91 days in any continuous 365-day period, payable during certified illness.
- Extended sickness benefit: Up to 124 to 309 additional days of cash compensation at 80% of daily wages for 34 specified chronic long-term diseases like tuberculosis, cancer, and heart ailments.
- Maternity benefit: 100% of average daily wages payable for 26 weeks for confinement/pregnancy, extendable by 1 month on medical advice, subject to statutory contribution conditions.
- Disablement benefit: Temporary disablement benefit paid at 90% of daily wage until recovery; permanent disablement benefit paid as lifelong monthly pension based on certified loss of earning capacity.
- Dependants benefit: Monthly pension paid at 90% of wages to surviving dependents (widow, children, and parents) in case of an insured worker's death due to employment injury or occupational disease.
Did You Know? (Uncapped medical benefit)
Unlike private retail health insurance policies which enforce a fixed sum insured (such as Rs. 5 lakh or Rs. 10 lakh), medical treatment under ESIC is entirely uncapped. From the very first day of insurable employment, an insured worker and their family are entitled to full medical care without any monetary ceiling on treatment costs at ESI facilities.
Quick Fact: Confinement and funeral cash grants
ESIC provides a lump-sum funeral expense grant of Rs. 15,000 paid to the dependents of a deceased insured person, and a confinement allowance of Rs. 7,500 per delivery to an insured woman or an insured person's wife if delivery occurs where ESI medical facilities are not available.
Pro tip
Eligibility for Employee’s State Insurance (ESI)
To be eligible for ESI benefits, an employee must satisfy these criteria:
- Employed in an establishment covered under the ESI Act.
- Drawing monthly gross salary/wages (excluding overtime pay) not exceeding Rs. 21,000 (or Rs. 25,000 for persons with disabilities).
- Registered on the ESIC portal and issued an official 17-digit insurance number.
What is covered under Employees’ State Insurance Scheme?
- Outpatient clinical consultations, prescription medicines, diagnostic laboratory investigations, and immunizations.
- Inpatient hospitalisation, specialized surgeries, and intensive care in ESIC hospitals and empaneled private tie-up facilities.
- Artificial limbs, wheelchairs, dentures, and orthopedic aids under physical and vocational rehabilitation schemes.
- Unemployment allowance under the Atal Beemit Vyakti Kalyan Yojana (ABVKY) for workers who lose employment involuntarily.
Popular plans for you
What is not covered under Employees’ State Insurance Scheme?
- Employees earning gross wages above Rs. 21,000 per month (except disabled employees up to Rs. 25,000).
- Members of the Indian Armed Forces, state police forces, and government employees covered by separate statutory medical schemes like CGHS.
- Direct admission to non-tie-up private hospitals without formal ESI referral or emergency intimation.
- Self-employed professionals, freelancers, and business owners not working as salaried employees in registered establishments.
Infrastructure of Employees State Insurance Scheme (ESIS)
The ESIC infrastructure comprises over 160 operational hospitals, 1,500+ dispensaries, 40+ dispensaries-cum-diagnostic centers, and contractual tie-ups with leading private superspeciality hospitals across India. Despite this extensive physical presence, urban healthcare demand often outpaces public infrastructure capacity, leading to long queues and referral delays.
When does ESI registration become necessary?
Within 15 days of becoming applicable, every covered factory or establishment must register online through the Ministry of Corporate Affairs or the Shram Suvidha portal, obtaining a 17-digit Employer Code. Employers must register every new employee within 10 days of their appointment.
ESIC contribution rates
Contribution rates were revised by the Ministry of Labour and Employment to reduce compliance burdens while expanding coverage:
| Contributor Category | Statutory Contribution Rate (% of Gross Wage) | Example (Gross Wage: Rs. 20,000/month) |
| Employee contribution | 0.75% of monthly gross wages | Rs. 150/month deducted from salary |
| Employer contribution | 3.25% of monthly gross wages | Rs. 650/month contributed by employer |
| Total monthly contribution deposited | 4.00% of wage bill | Rs. 800/month deposited in ESIC account |
When does ESI registration become necessary?
ESI registration is mandatory for any company, organisation, or business establishment employing 10 or more workers—or more than 20 employees in Maharashtra and Chandigarh. The Employees’ State Insurance Corporation (ESIC) scheme covers workers earning up to Rs.21,000 per month (Rs.25,000 for persons with disabilities). Employees contribute 1.75% of their wages, while employers contribute 4.75 %. These rates are subject to change as per government notifications. Workers earning an average daily wage of up to Rs. 50 are exempt from employee contribution, though employers must still make their share of the contribution.
Why you need supplementary private health insurance alongside ESI?
While ESI provides an essential social safety net, salaried professionals increasingly supplement it with private retail health insurance:
- Wage-increase cliff: ESI coverage ceases once promotions push your salary beyond Rs. 21,000. Transitioning to a private health plan at that stage can be difficult if pre-existing ailments have developed, as fresh waiting periods will apply.
- Direct access to premier private hospitals: Retail health plans allow immediate cashless admission to private tertiary hospitals without requiring bureaucratic dispensary referrals.
- Room category comfort: Private plans offer single private rooms without sub-limits, whereas ESI hospitalisation is typically in general wards.
- Long-term continuity: An individual health insurance or family health insurance policy stays with you throughout your life, regardless of job changes, career promotions, or retirement.
Explore budget-friendly retail health plans: check plans on Bajaj Finance to bridge your family's coverage gaps and secure lifetime continuity.
Brief example scenario: ESI benefits vs private health insurance floater
Consider Sunil Shinde (age 34), earning Rs. 20,500 per month as a logistics supervisor. Sunil contributes Rs. 154 monthly to ESI (Rs. 1,848/year). Knowing he will soon cross the Rs. 21,000 wage ceiling, Sunil also purchases an affordable private family floater policy on Bajaj Finance (Rs. 10 lakh sum insured; premium: Rs. 9,800/year):
| Healthcare Parameter | Standalone Statutory ESI Coverage | Combined Strategy: ESI + Private Retail Plan |
| Annual employee outlay | Rs. 1,848 (Deducted from salary) | Rs. 11,648 (ESI + Private floater premium) |
| Access to private healthcare | Restricted to ESI dispensaries and tie-up referrals | Direct cashless admission across 10,000+ private hospitals |
| Room category eligibility | Shared general ward in ESI hospital | Single private room without sub-limit |
| Wage ceiling protection | Coverage terminates when salary exceeds Rs. 21,000 | Unbroken lifetime continuity regardless of salary growth |
| Waiting period continuity | Resets if ESI is lost without private backup | Builds cumulative waiting period credits from age 34 |
| Income tax deduction | No direct deduction for mandatory ESI contribution | Full Rs. 9,800 deductible under Section 126 / Section 80D |
Key financial insight: By adding a private floater plan while still covered under ESI, Sunil secured immediate access to premier private healthcare, protected his family against the upcoming wage-ceiling cliff, and claimed tax deductions under Section 126.
Show more
Show less
Do’s and don’ts for Employees’ State Insurance Scheme
| Do | Why it matters | Don’t | Risk to avoid |
| Register on the ESIC portal and obtain your 17-digit Pehchan card. | Serves as official identity proof for medical and cash benefits. | Do not delay reporting new dependents (newborn child, spouse) to ESIC. | Unregistered dependents cannot access free medical care. |
| Follow formal referral channels when seeking treatment at private tie-up hospitals. | Mandated by ESIC regulations to ensure cashless treatment authorization. | Do not visit non-empanelled private hospitals for non-emergencies. | Unauthorized private hospitalisation bills will not be reimbursed by ESIC. |
| Consider a supplementary private health plan before your salary crosses Rs. 21,000. | Ensures seamless waiting period continuity when ESI coverage ceases. | Do not assume ESI coverage will continue after promotions past Rs. 21,000. | Crossing the wage cap abruptly leaves your family completely uninsured. |
| Claim statutory tax deductions on supplementary private health insurance premiums. | Lowers your net tax outgo under Section 126 under the Old Tax Regime. | Do not ignore cash maternity and sickness benefit deadlines. | Late claims for sickness or maternity allowances may lapse. |
| Keep your bank account details updated on the ESIC portal. | Ensures direct electronic credit of sickness, maternity, and disablement benefits. | Do not conceal pre-existing ailments when buying private supplementary plans. | Non-disclosure invalidates private insurance claims under Section 45. |
Step-by-step roadmap to utilize ESI and secure private coverage
- Step 1: Verify your ESI registration status. Check your Pehchan card, confirm that monthly wage deductions match the 0.75% rate, and map your designated local ESI dispensary.
- Step 2: Evaluate supplementary private coverage. If your monthly wage is near the Rs. 21,000 threshold or if your family prefers private hospital access, benchmark retail plans on Bajaj Finance.
- Step 3: Complete digital application on Bajaj Finance. Select a floater plan with zero room rent sub-limits, pay via net banking, and activate immediate private healthcare protection alongside your ESI cover. You can get quote online to review options.
Health Insurance in different cities

Health Insurance in Bangalore

Health Insurance in Jaipur

Health Insurance in Pune

Health Insurance in Mumbai

Health Insurance in Kerala
Glossary of social security and insurance terms
| Term | Definition |
| Employees’ State Insurance (ESI) | A statutory social insurance scheme under the ESI Act, 1948 providing healthcare and cash benefits to wage earners. |
| Employees’ State Insurance Corporation (ESIC) | The statutory authority administering ESI funds, hospitals, and benefit disbursements under the Ministry of Labour. |
| Wage ceiling (Rs. 21,000) | The statutory gross monthly salary threshold up to which an employee is mandatorily covered under the ESI scheme. |
| Contribution period | A 6-month statutory block (April to September, October to March) during which employer and employee contributions are deposited. |
| Benefit period | The corresponding 6-month period following a contribution period during which cash sickness and maternity benefits are disbursed. |
| Pehchan card | The official identity card issued by ESIC carrying a 17-digit insurance number enabling nationwide healthcare access. |
| Sickness benefit | A cash allowance equal to 70% of average daily wages paid for up to 91 days per year during certified illness. |
| Extended sickness benefit | Cash compensation paid at 80% of wages for up to 124 to 309 days for 34 specified chronic long-term diseases. |
| Customer Information Sheet (CIS) | An IRDAI-mandated summary sheet detailing coverage terms, waiting periods, sub-limits, and exclusions for private health plans. |
| Third Party Administrator (TPA) | An IRDAI-licensed entity facilitating network hospital empanelment, cashless pre-authorization, and document verification for insurers. |
Compare types of Health Insurance Plans
Sources and references
| Regulatory Authority / Publication | Document Identifier / Citation | Statutory Subject / Verified Parameter | Official Source Link |
| Ministry of Labour and Employment, Government of India | Employees’ State Insurance Act, 1948 & Amendments | Statutory Social Security Framework, Wage Ceiling Mandates, and Industry Applicability | Ministry of Labour (https://labour.gov.in) |
| Employees’ State Insurance Corporation (ESIC) | ESIC Operational Manual & Contribution Guidelines (2019 Notification) | Revised Contribution Rates (0.75% Employee, 3.25% Employer) and Benefit Schedules | ESIC Official Portal (https://esic.gov.in) |
| Insurance Regulatory and Development Authority of India (IRDAI) | Master Circular on Operations and Allied Matters of Health Insurance Business (Ref: IRDAI/HLT/CIR/PRO/84/5/2024) | Retail Health Insurance Standards, Cashless SLAs, and Waiting Period Continuity | IRDAI Official Portal (https://irdai.gov.in) |
| Ministry of Finance, Government of India | Income-tax Act, 2025 (Section 126) / Income-tax Act, 1961 (Section 80D) | Direct Tax Deductions on Premiums Paid for Supplementary Private Health Insurance | Income Tax India (https://incometaxindia.gov.in) |
Tax-savings plans for you
Conclusion
The Employees’ State Insurance Scheme is a vital pillar of social security in India, providing millions of formal sector workers with uncapped medical care, cash sickness allowances, maternity coverage, and lifelong disability pensions. For employees earning up to Rs. 21,000 monthly, ESI ensures that healthcare crises do not result in catastrophic financial destitution.
However, as your career advances and your salary rises past the statutory wage ceiling, ESI coverage will cease. Relying exclusively on ESI leaves you vulnerable to an abrupt loss of coverage in mid-career. Proactive financial planning demands complementing your statutory ESI cover with an affordable retail family floater policy from a leading partner insurer. Explore and compare partner health plans: apply now on Bajaj Finance today to secure direct cashless access to premier private hospitals, protect your family against wage-ceiling cliffs, and build lifelong health security.
What our customer say about us
+ Customers
Play Store Rating
Reviews
Arjun Mehta
13 Jul 2025
I opted for the Health Infinity plan for my parents. The digital onboarding was incredibly fast with no medical tests required since they are under 50. We had a minor daycare procedure last month, and the cashless approval came through in less than 2 hours. Very impressed with the efficiency.
Priya Sharma
28 Feb 2025
The Bajaj Finance Health app is a lifesaver. I use it for my regular OPD consultations and medicine orders. The 10% discount on pharmacy bills and the easy reimbursement for doctor visits make it much more than just a 'hospitalization' policy. It’s daily health support.
Sneha Kapoor
15 Mar 2025
Switched my family floater to Bajaj General this year. The network of hospitals in my city (Pune) is excellent. The only downside was a slight delay in getting my physical card, but the digital copy on the app works everywhere. The 'Wellness Rewards' for hitting step goals is a cool touch!
Explore and stay informed
Can you buy health insurance on EMI
Why buy health insurance
Health Insurance for family
Health Insurance Claim settlement ratio
Health Insurance waiting period
Importance of health insurance
Health Insurance for Senior Citizens
Health Insurance tax benefits
Health Insurance for parents
Health Insurance premium calculator
Health Insurance for Other Diseases

Antral Gastritis

Hepatomegaly Symptoms Causes & Treatment

Blood Pressure Range

PCOS Causes and Symptoms

Health insurance for Obesity
Frequently Asked Questions
Scheme eligibility, wage ceilings, and contributions
Benefits, private hospital access, and supplementary coverage
What is the Employee's State Insurance Scheme?
The ESI scheme is a statutory social security program enacted under the ESI Act, 1948, providing comprehensive medical care and cash compensation for sickness, maternity, disablement, and death to eligible employees.
How is the ESIS funded?
ESIS is self-financed through mandatory monthly contributions from employees (0.75% of gross wages) and employers (3.25% of gross wages), deposited into the centralized ESIC social security fund.
Who is eligible for the ESIS?
Any employee working in a registered factory or commercial establishment employing 10 or more persons with a monthly gross wage not exceeding Rs. 21,000 (Rs. 25,000 for persons with disabilities) is eligible.
Is employee state insurance mandatory in India?
Yes. For all eligible employees working in covered establishments earning within the statutory wage limit, ESI registration and contribution are legally mandatory under the ESI Act, 1948.
What is the wage limit for employee state insurance?
The statutory gross wage limit is Rs. 21,000 per month for standard employees and Rs. 25,000 per month for employees with certified disabilities.
What are the 5 core benefits of ESIC?
The five core benefits are medical benefit (full hospitalisation and outpatient care), sickness benefit (70% wage replacement), maternity benefit (100% wage for 26 weeks), disablement benefit (90% wage), and dependants benefit (90% monthly pension to family upon death).
Can an ESI beneficiary visit private hospitals directly?
In non-emergencies, beneficiaries must first visit their designated ESI dispensary, which provides a formal referral to an empaneled private tie-up hospital. In acute life-threatening emergencies, direct admission to tie-up hospitals is permissible subject to timely intimation.
What happens to ESI benefits when your salary crosses Rs. 21,000?
When your gross salary exceeds Rs. 21,000, your ESI coverage terminates at the end of the ongoing contribution period. To prevent being left uninsured, employees should purchase a private retail health plan before crossing this threshold.
Can you hold a private health insurance policy while being covered under ESI?
Yes. You can hold both ESI and a private health insurance policy simultaneously. A private health floater grants direct cashless access to leading private hospitals without requiring ESI dispensary referrals.
Are private health insurance premiums tax-deductible if you are also in ESI?
Yes. Premiums paid for supplementary private health insurance policies qualify for direct tax deductions under Section 126 of the Income-tax Act, 2025 (formerly Section 80D) under the Old Tax Regime.
Articles and Insights
Disclaimer
*T&C Apply - Bajaj Finance Limited (‘BFL’) is a registered corporate agent of third party insurance products of Bajaj Allianz Life Insurance Company Limited, HDFC Life Insurance Company Limited, Life Insurance Corporation of India (LIC), Bajaj Allianz General Insurance Company Limited, SBI General Insurance Company Limited, ACKO General Insurance Company Limited, HDFC ERGO General Insurance Company, TATA AIG General Insurance Company Limited, ICICI Lombard General Insurance Company Limited, New India Assurance Limited, Chola MS General Insurance Company Limited, Zurich Kotak General Insurance Co. Limited , Star Health & Allied Insurance Co. Limited, Care Health Insurance Company Limited, Niva Bupa Health Insurance Company Limited , Aditya Birla Health Insurance Company Limited and Manipal Cigna Health Insurance Company Limited under the IRDAI composite CA registration number CA0101. Please note that, BFL does not underwrite the risk or act as an insurer. Your purchase of an insurance product is purely on a voluntary basis after your exercise of an independent due diligence on the suitability, viability of any insurance product. Any decision to purchase insurance product is solely at your own risk and responsibility and BFL shall not be liable for any loss or damage that any person may suffer, whether directly or indirectly. Please refer insurer's website for Policy Wordings. For more details on risk factors, terms and conditions and exclusions please read the product sales brochure carefully before concluding a sale. Tax benefits applicable if any, will be as per the prevailing tax laws. Tax laws are subject to change. Tax laws are subject to change. BFL does NOT provide Tax/Investment advisory services. Please consult your advisors before proceeding to purchase an insurance product. Visitors are hereby informed that their information submitted on the website may also be shared with insurers. BFL is also a distributor of other third-party products from Assistance Services providers such as CPP Assistance Services Pvt. Ltd., Bajaj Finance Health Ltd. etc. All product information such as premium, benefits, exclusions, sum insured, value added services, etc. are authentic and solely based on the information received from the respective insurance company or the respective Assistance service provider company.
Note – While we have made all efforts and taken utmost care in gathering precise information about the products, features, benefits, etc. However, BFL cannot be held liable for any direct or indirect damage/loss. We request our customers to conduct their research about these products and refer to the respective product’s sales brochures before concluding their sale.