







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
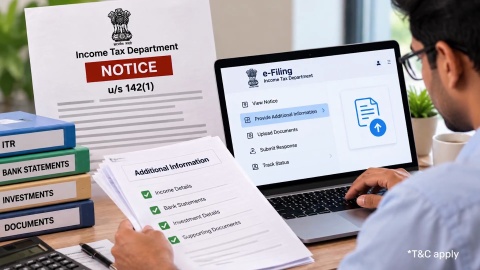
Income Tax Notice under Section 142(1) of Income Tax Act
Last updated: Sept 2026
Two genuinely different situations trigger a Section 142(1) notice, and confusing them leads to the wrong response. One asks you to file; the other asks you to explain something already filed.
- Trigger 1: you haven't filed a return the department believes was due
- Trigger 2: the assessing officer needs specific accounts, documents or clarification before completing an assessment on a return already filed
- Response window: a specified number of days stated in the notice itself, commonly 15 to 30 days
- Consequence of non-compliance: the officer can proceed to a best-judgment assessment under Section 144, based only on available information
Distinct from Section 143(2): 142(1) is a broader inquiry notice; 143(2) specifically initiates scrutiny assessment
Respond within the notice's stated window through the income tax portal, since a best-judgment assessment under Section 144 rarely favours the taxpayer.
Does a Section 142(1) notice mean I'm being audited?
Not necessarily, and this is the real anxiety behind most searches for this notice. Section 142(1) covers two distinct scenarios. One is a simple prompt to file a missing return. The other requests specific information during a routine or scrutiny assessment. Neither is automatically an audit in the everyday sense of that word.
Identifying which of the two triggers applies to your specific notice determines how serious a response you need to prepare. The realistic scenarios a recipient finds themselves in are:
- A straightforward reminder to file a return you missed, requiring only that you file the pending return within the stated window
- A request for specific documents or clarification on an already-filed return, requiring a targeted, factual response to what's actually asked
Part of a broader scrutiny assessment, where the notice is one of several communications and warrants more careful preparation, possibly with professional help
Reading the specific wording of your notice, rather than assuming the worst based on receiving any notice at all, is the first genuine step in responding correctly. This creates a real trade-off in how much you prepare: over-preparing for a simple missing-return notice wastes time and, if you hire a CA unnecessarily, money, while under-preparing for a genuine scrutiny-linked notice risks an inadequate response that invites further questions.
Show more
Show less
What can the assessing officer actually ask for under this section?
The section's scope is broad, but it is not unlimited.
| Request type | Example |
|---|---|
| Filing a missing return | A return for a year the department believes was due but not filed |
| Producing accounts or documents | Bank statements, invoices, investment proofs relevant to a filed return |
| Furnishing specific information | Clarification on a specific transaction or income source |
| Explaining a discrepancy | A mismatch between declared income and information the department already holds (from AIS, TDS records, or similar) |
A notice citing a specific transaction, such as a large deposit or property purchase, traces to a data mismatch the department has already identified in most cases. This most often comes through the Annual Information Statement (AIS).
Show more
Show less
How do I respond to a Section 142(1) notice correctly?
Four steps structure a response that actually addresses what the officer is asking for.
- Read the notice carefully to identify exactly what is being requested — a missing return, specific documents, or an explanation.
- Gather the requested documents or information, organised to directly match each specific point raised in the notice.
- Submit your response through the income tax e-filing portal within the stated window, using the notice's specific reference number.
Retain a copy of your submission and any acknowledgment, since this becomes your record if the matter is later questioned.
Submitting a vague or incomplete response is the most common reason a straightforward inquiry escalates. Address each specific point the notice raises directly, rather than replying in general terms.
Show more
Show less
A worked example: responding to a documentation request
Consider Meena, a 39-year-old consultant with a household income of Rs. 1.2 lakh a month and a CIBIL Score of 747, who receives a Section 142(1) notice asking her to explain a specific bank deposit flagged in her AIS.
| Step | What Meena did |
|---|---|
| Identified the trigger | A Rs. 8 lakh deposit not matching her declared income sources |
| Gathered documentation | Traced the deposit to a matured fixed deposit, with the bank's maturity statement as proof |
| Drafted a targeted response | Explained the source directly, attaching the maturity statement |
| Submitted within the window | Filed the response through the portal 6 days after receiving the notice |
Because Meena's response directly addressed the specific flagged transaction with matching documentation, the inquiry closed without escalating to a broader scrutiny assessment.
Show more
Show less
Home loan for professionals
Financing a home with a clean assessment history using Bajaj Finance
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 Crore* |
| Tenure | Up to 32 years |
A resolved, well-documented response to any income tax notice strengthens your overall financial documentation for a home loan application. Approval timelines can extend where unresolved notices or pending assessments need clarification, and minimum income thresholds can differ by city. Check your home loan eligibility once any pending notice is resolved.
Show more
Show less
Frequently Asked Questions
Understanding the notice
Responding effectively
Can I ignore a Section 142(1) notice if I believe it was sent in error?
No, even if you believe the notice is mistaken, respond within the window explaining why, rather than ignoring it entirely. Non-response risks a best-judgment assessment under Section 144, which is based only on information available to the officer and rarely works in the taxpayer's favour, regardless of the notice's original accuracy.
Is a Section 142(1) notice the same as a scrutiny notice under Section 143(2)?
No, these are separate provisions. Section 142(1) is a broader inquiry notice, which can request a missing return or specific information. Section 143(2) specifically initiates scrutiny assessment for a return already filed. A single case can involve both notices at different stages of the same assessment, so check the notice's specific section reference.
Do I need a chartered accountant to respond to a Section 142(1) notice?
Not strictly required for a straightforward missing-return or simple-documentation request, but recommended where the notice involves a complex transaction, multiple discrepancies, or forms part of a broader scrutiny assessment, since a professional can help structure a complete, accurate response the officer accepts without further follow-up.
What happens if I can't gather all requested documents within the stated window?
Request an extension through the portal or in writing before the deadline passes, explaining specifically what you need more time for, rather than missing the deadline silently. A reasonable extension request, made proactively, is viewed more favourably as a rule than a late or incomplete response with no explanation given at all.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.