








₹ 2 lakh – ₹ 80 lakh
Check your pre-approved offer and other benefits
Enter mobile and OTP | Check offer | Know your exact loan terms
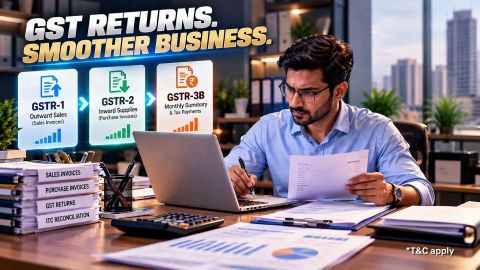
GST Returns Explained
-
In summary
GSTR-2A is a dynamic, read-only statement on the GST portal showing inward supplies reported by suppliers. Use it to review purchase records and support accurate GST return preparation.
- GSTN generates GSTR-2A from relevant supplier filings; recipients do not file the statement themselves.
- It generally becomes available from the 11th of the following month for relevant data and may update as suppliers file or amend information.
- It includes supplier and invoice details, taxable values, and tax amounts for comparison with your purchase register.
- GSTR-2A reconciliation means matching supplier-reported data with purchase records and investigating missing invoices or value differences.
- GSTR-2A is dynamic, while GSTR-2B is static and supports period-based ITC decisions; check current rules before reporting credit in GSTR-3B.
Maintain accurate GST records and review ITC eligibility before filing. If you need funding for an eligible business purpose, explore Bajaj Finance Business Loan.
What is GSTR-2A?
-
GSTR-2A is an auto-generated, read-only statement on the GST portal that shows inward-supply details reported by suppliers through applicable filings, including GSTR-1. It is generated for the recipient by the Goods and Services Tax Network (GSTN), so you do not prepare or file it yourself. Because it is dynamic, the details can change when suppliers submit or amend relevant information.
Use GSTR-2A to check whether supplier-reported information agrees with your invoices and purchase register. It supports reconciliation, but the appearance of an invoice in GSTR-2A does not, by itself, establish that input tax credit (ITC) is eligible. Review GSTR-2B, the underlying documents, and the conditions in current GST law before reporting ITC in GSTR-3B.
What does GSTR-2A contain?
-
The GSTR-2A format can show supplier registration details, invoice information, tax values, credit or debit notes, and other applicable inward-supply information. The fields available depend on the transaction and the supplier information reported.
Detail Description GSTIN The supplier’s Goods and Services Tax Identification Number. Supplier details Supplier name and relevant registration details. Tax period The return period to which the reported supply relates. Invoice number and date The supplier’s invoice identifier and issue date. Invoice value and taxable value The total invoice amount and the value on which GST is calculated. Tax charged Applicable tax amounts, including CGST, SGST or IGST. Credit/debit notes and amendments Adjustments or corrections reported against earlier documents. Other inward-supply details Applicable import, SEZ or other-source information where included in the available statement. Use the table below as a practical checklist of the details to compare. For linked guidance, see GSTIN, CGST, SGST, and IGST.
Why is timely GSTR-2A reconciliation important?
Timely GSTR-2A reconciliation helps you find missing invoices, incorrect supplier details, and differences between your purchase register and supplier-reported data before you finalise your GST records.
- Missing invoices: identify purchases not visible in the statement and follow up with the supplier.
- Incorrect values or GSTINs: correct invoice details with the supplier and keep supporting documents.
- ITC differences: check eligible credit against applicable records before reporting it in GSTR-3B.
- Unresolved differences may lead to follow-up questions or scrutiny in relevant cases. A notice such as GST ASMT-10 is not an automatic consequence of every mismatch; the response required depends on the notice, facts, and applicable law.
Regular reconciliation also helps you maintain organised records when reviewing your business finances or applying for an MSME loan.


What happens if a seller delays GSTR-1 or fails to upload invoices?
If a supplier delays GSTR-1 or omits an invoice, the transaction may not appear in your GSTR-2A until the relevant information is reported or corrected. Follow up promptly, retain your invoice and correspondence, and reassess the ITC treatment under current rules rather than assuming the credit is automatically available.
- Delayed matching: your purchase register may contain an invoice that is not yet visible in GSTR-2A.
- Cash-flow or filing pressure: you may need to contact the supplier and resolve the discrepancy before finalising the relevant return.
- ITC eligibility risk: an invoice alone does not guarantee that credit is claimable. Check statutory conditions, supplier reporting requirements, and current rules.
Keep a record of supplier follow-ups and recheck the statement after the supplier files or corrects the relevant details. If you run a new venture, consider startup business loans only when external funding fits your needs and repayment capacity.
What is the difference between GSTR-2A and GSTR-2B?
GSTR-2A is dynamic and may update as supplier information is filed or amended. GSTR-2B is a static, period-based statement intended to support ITC decisions for the relevant tax period.
| Parameter | GSTR-2A | GSTR-2B | Best used for |
| Update frequency | Dynamic; updates as relevant data is filed or amended. | Static statement for a tax period. | GSTR-2A for tracking changes; GSTR-2B for period-based review. |
| Data sources | Supplier-reported inward-supply information and applicable sources. | Auto-drafted ITC information from applicable supplier and system sources. | Use the statement relevant to the transaction and period. |
| ITC role | Useful for checking invoice appearance and reconciling records. | Designed to support ITC decisions for the relevant period. | Check current GST rules and eligibility before reporting ITC in GSTR-3B. |
| Amendments | May change when supplier information is amended. | Static for the period; later information may be reflected according to applicable processes. | Investigate differences and track later-period changes. |
Use GSTR-2A to track supplier-reported changes and investigate missing information. For monthly ITC decisions, review GSTR-2B alongside invoices, purchase records, and the applicable GST provisions; do not treat either statement as a substitute for checking statutory eligibility.
What is the difference between GSTR-2A and GSTR-3B?
GSTR-2A is an auto-generated, read-only statement of inward-supply information reported by suppliers. GSTR-3B is a summary return filed by applicable taxpayers to report tax liability and eligible ITC.
| Parameter | GSTR-2A | GSTR-3B |
| Nature | Auto-generated statement; not filed by the recipient. | Self-declared summary return filed by applicable taxpayers. |
| Purpose | Shows inward-supply details reported by suppliers. | Reports summary tax liability and eligible ITC. |
| Due date | No filing due date because the recipient does not file GSTR-2A. | Depends on taxpayer and filing frequency; monthly filers commonly have a due date on the 20th, while quarterly filers may have different dates. |
| ITC role | Supports checking and reconciliation. | Eligible ITC is reported here subject to GST rules. |
Reconcile the supplier information and purchase records before filing GSTR-3B, and report only the credit that meets the applicable legal conditions.
What is the difference between GSTR-2A and GSTR-9 table 8A?
GSTR-2A is used for ongoing review of supplier-reported inward supplies, while Table 8A of GSTR-9 belongs to the annual-return process and follows the instructions applicable to the relevant financial year.
| Parameter | GSTR-2A | GSTR-9 Table 8A |
| Data source | Supplier-reported data available in the dynamic statement. | Annual-return data populated according to applicable table instructions and filed-return sources. |
| Purpose | Ongoing invoice-level checking and reconciliation. | Annual reconciliation of ITC-related information. |
| Scope | Tax-period information that can update when suppliers amend filings. | Annual-return reporting for the relevant financial year. |
Check the current GSTR-9 instructions for the financial year you are filing. Do not assume that the figures or source data used for Table 8A are identical across financial years.
How to reconcile GSTR-3B with GSTR-2A or GSTR-2B?
To reconcile GSTR-3B with GSTR-2A or GSTR-2B, compare the return figures with your purchase register, invoices, supplier-reported data, and applicable ITC rules. Then investigate each difference before deciding how to treat it.
- View the relevant GSTR-2A and GSTR-2B statement for the tax period.
- Compare invoice numbers, dates, supplier GSTINs, taxable values, and tax amounts with your purchase register.
- Identify missing invoices, duplicate entries, amendments, and differences in tax amounts.
- Follow up with suppliers where reporting or invoice details need correction.
- Review whether each item meets current ITC conditions before reporting or retaining the credit.
- Keep reconciliation workings, invoices, correspondence, and explanations for unresolved differences.
Unresolved differences may prompt a query or notice, including GST ASMT-10 in relevant cases. Respond within the stated timeline and seek professional advice where the position is uncertain.
A practical reconciliation example
For example, if your purchase register includes an invoice that is missing from GSTR-2A, verify the invoice and supplier GSTIN, then ask the supplier whether the relevant return was filed and the invoice was reported correctly. Recheck the statement after the supplier corrects the data. Separately assess ITC eligibility using GSTR-2B, supporting documents, and current GST rules.
What causes GSTR-2A or GSTR-2B to not match GSTR-3B?
GSTR-2A or GSTR-2B may not match GSTR-3B because the statements serve different purposes, suppliers may report or amend details later, and some transactions follow different reporting routes.
| Cause | Explanation |
| Import IGST on goods | Import-related credit may be supported by a bill of entry and import records rather than a domestic supplier invoice. |
| Import of services | Reverse-charge treatment and supporting records may affect how a transaction appears. |
| Reverse charge | Tax paid under reverse-charge provisions may not appear in the same way as supplier-reported forward-charge invoices. |
| Transitional or special-period credit | Legacy or transitional claims may not map directly to current supplier-reported invoice data; verify applicable provisions. |
| Timing or amendments | A supplier may file or amend details later, so the statement may change after an initial review. |
Do not assume that every difference is an error or that every difference is acceptable. Identify the reason, retain supporting evidence, and confirm the treatment under current GST rules.
How is GSTR-2A generated?
GSTR-2A is generated automatically by GSTN using relevant supplier-reported information. The recipient does not manually prepare or file the statement.
- Suppliers report outward-supply information in their applicable returns.
- GSTN processes the reported details and associates relevant inward-supply information with the recipient.
- The statement becomes available for the relevant tax period, generally from the 11th of the following month for relevant supplier return data.
- Supplier amendments or later filings can change the information shown in the dynamic statement.
- The statement may change when suppliers file or amend relevant information. Review it against invoices and your purchase register, and investigate differences before finalising the related return.
How to use GSTR-2A for return filing?
You do not file GSTR-2A. You use it as a read-only statement to review supplier-reported purchases and reconcile records before filing GSTR-3B.
- Log in to the GST portal and open the relevant returns dashboard.
- Choose the financial year and tax period.
- View GSTR-2A and review invoice-level entries.
- Compare the statement with your purchase register and supporting invoices.
- Resolve or document differences and check ITC eligibility under current rules.
- Complete and file GSTR-3B with eligible amounts and required disclosures.
Check the applicable return instructions and statutory conditions for each tax period. GSTR-2A supports reconciliation; it does not independently approve an ITC claim.
Check your pre-approved business loan offer
Common errors in GSTR-2A and how to fix them
Common GSTR-2A mismatches often arise from supplier non-filing, incorrect GSTINs, omitted invoices, or differences in taxable values and tax amounts. Use the table to identify the next practical step.
| Common error | How to fix it |
| Missing invoice | Ask the supplier to check and report the invoice in the applicable return; recheck the statement after filing. |
| Incorrect supplier GSTIN | Verify the GSTIN on the invoice and request correction through the supplier’s applicable return process. |
| Supplier has not filed the return | Follow up with the supplier and track the invoice until the details appear. |
| Mismatch in taxable value | Compare the invoice with the reported data and ask the supplier to correct any error. |
| Incorrect tax rate or tax amount | Check the applicable rate and calculation, then request correction if needed. |
After making a correction or receiving a supplier update, recheck the statement and document how the mismatch was resolved.
How do I download GSTR-2A from the GST portal?
To download GSTR-2A, sign in to the GST portal, open Services > Returns > Returns Dashboard, and select the relevant financial year and tax period.
- Log in to the GST portal at www.gst.gov.in using your credentials.
- Open Services > Returns > Returns Dashboard.
- Select the financial year and return period, then search for available returns.
- Open the GSTR-2A tile and choose the download option if available for the selected period.
- Select an available download option and file format shown on the portal, then save the statement for reconciliation.
Portal workflows, formats, and download limits can change. Follow the current instructions displayed on the GST portal and use the relevant official utility where required.
Can I claim input tax credit (ITC) based on GSTR-2A?
GSTR-2A helps you verify supplier-reported invoices, but you should not claim ITC solely because an invoice appears in the statement. For period-based ITC decisions, review GSTR-2B, the supporting documents, and all applicable conditions under GST law.
Check the invoice, receipt of goods or services, supplier reporting, tax-payment conditions where relevant, and other statutory requirements. A mismatch or missing entry should be investigated; it does not, by itself, determine every aspect of eligibility. Seek qualified tax advice where the treatment is uncertain.
Keep your GST records and business finances organised. If you are considering funding for an eligible business need, check your business loan eligibility before applying.
How can business financing support your business?
Accurate GST records can support day-to-day financial management, but borrowing should be based on a defined business need and your ability to repay. Bajaj Finance Business Loan offers eligible applicants funding from Rs. 2 lakh to Rs. 80 lakh, with repayment tenures ranging from 12 to 96 months. The loan is unsecured, so collateral is not required.
The eligibility criteria include Indian nationality, self-employed status, a business vintage of at least 3 years, a CIBIL score of 650 or higher, and an age range of 21 to 80 years, with the upper age limit applying at loan maturity. Documents required include KYC proof, PAN, and proof of business ownership; additional financial documents may be requested.
The interest-rate range is 14%–23.50% per annum, and processing fees may be up to 4.72% of the loan amount, inclusive of applicable taxes. Your actual offer, charges, and repayment schedule depend on the application and the applicable terms.
Before applying, check your pre-approved business loan offer to see whether an offer is available. Review the amount, interest rate, fees, and repayment schedule against your business requirements.









Select loan by amount
Applicable fees and charges on our business loan

Loans for business needs















Get business loan for your needs

Women Business Loan
Get Women Business Loan upto 80 Lakh

Medical Store Business Loan
Get Medical Store Business Loan upto 80 Lakh

Manufacturer Business Loan
Get Manufacturer Business Loan upto 80 Lakh
Business loan in different cities

Business loan in bangalore

Business loan in mumbai

Business loan in pune

Business loan in Jaipur

Business loan in Kerala
Business loan for different budgets

2 lakh business loan
3 lakh business loan
5 lakh business loan
10 lakh business loan

15 lakh business loan
20 lakh business loan
25 lakh business loan
30 lakh business loan
50 lakh business loan
Types of business loan
Unsecured Business Loan
Secured Business Loan
Term Loan
Cash Credit
Working Capital Loan
Machinery Loan
Line of Credit
Micro Loan
Merchant cash Loan
Frequently asked questions
Overview
What is GSTR-2A reconciliation and why does it matter?
GSTR-2A reconciliation is matching supplier-reported information with your purchase register and invoices to identify missing entries or differences. It helps you review ITC before filing GSTR-3B. Unresolved discrepancies may prompt questions or notices, including GST ASMT-10 in relevant cases, so keep supporting documents and explanations.
When is GSTR-2A generated and who can access it?
GSTR-2A is generated automatically for GST-registered recipients from relevant supplier filings and other applicable information. It is generally available from the 11th of the following month for relevant supplier return data, but remains dynamic as later filings or amendments are processed. Access it through the GST portal.
Is GSTR-2A auto-generated or manually filed?
GSTR-2A is auto-generated by GSTN; the recipient does not manually file it. It reflects relevant inward-supply information reported by suppliers, including details from GSTR-1 filings. Review it against your purchase records and use it as part of reconciliation before filing applicable returns.
How is GSTR-2A linked to GSTR-3B?
GSTR-2A shows supplier-reported inward-supply information that you compare with purchase records before filing GSTR-3B. GSTR-3B is the summary return in which eligible ITC is reported under applicable rules. Reconcile differences and retain documents; unresolved mismatches may lead to follow-up from tax authorities.
What is the difference between GSTR-2A and GSTR-2B?
GSTR-2A is dynamic and can update when supplier details are filed or amended, while GSTR-2B is a static statement for a tax period. GSTR-2A helps track supplier data and reconcile invoices; GSTR-2B supports period-based ITC decisions. Check current GST rules before claiming credit in GSTR-3B.
Does GSTR-2A represent sales or purchases?
GSTR-2A represents purchases, or inward supplies, from the recipient’s perspective. It displays information reported by suppliers about supplies made to the recipient and helps the buyer compare invoices with its purchase register and review ITC records.
Can I claim ITC if an invoice is missing from GSTR-2A?
If an invoice is missing from GSTR-2A, contact the supplier and check applicable GST rules before claiming ITC. Its absence may indicate incomplete supplier reporting, but eligibility depends on statutory conditions and the facts. Claiming credit without meeting the rules can lead to a mismatch or notice and may have further consequences.
Who can view or access GSTR-2A?
GST-registered taxpayers can generally access their inward-supply statement through the GST portal after signing in. It is generated using relevant supplier information, including GSTR-1 and other applicable filings. The information available depends on supplier reporting and portal features.
What is the due date or cut-off date for GSTR-2A?
GSTR-2A has no filing due date because the recipient does not file it, and the statement can update when relevant supplier information changes. It is generally available from the 11th of the following month for relevant supplier return data. Check the portal calendar for current GSTR-2B generation details.
Is GSTR-2A still active or has it been discontinued?
GSTR-2A remains a relevant dynamic statement for reviewing supplier-reported inward supplies. Portal download and viewing workflows may change, so check current GST portal instructions for options available to your account and period. GSTR-2B is the static statement used to support period-based ITC decisions.
More articles

Disclaimer
Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.