







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
Section 14 of the Income Tax Act - Heads of Income us 14
Last updated: Sept 2026
Section 14 of the Income Tax Act is the starting point for every tax calculation. Before any deduction or exemption applies, income must first be sorted into the correct head. Getting this classification wrong changes which rules, rates and deductions actually apply to that income.
- The 5 heads: Salary, Income from House Property, Profits and Gains of Business or Profession, Capital Gains, Income from Other Sources
- Each head has its own computation rules and permitted deductions
- Total income is the sum across all 5 heads, after head-specific adjustments
- Losses under one head can sometimes be set off against income under another, subject to specific rules
Income not fitting any of the first 4 heads falls into Other Sources, a residual category
Classify each income source under its correct head first. The applicable deductions and rates follow from that classification.
Why does income need sorting into heads first?
Each head under Section 14 carries its own set of computation rules, permitted deductions, and in some cases, different treatment for losses. Taxing all income identically, without this classification, would ignore the genuinely different economic nature of salary versus rental income versus a business profit.
Classification is not paperwork for its own sake — it determines which specific deductions actually apply to a given rupee of income. The practical consequences of correct classification are:
- Salary income gets standard deduction and specific salary-linked exemptions, which do not apply to business income
- House property income gets a standard 30% deduction for repairs and maintenance, regardless of actual expense, which no other head offers
- Business income allows deduction of actual documented expenses, which salary income does not
Capital gains get indexation benefits and different tax rates depending on the holding period, unlike any other head
Misclassifying income, such as treating freelance income as salary, denies you the deductions your income is actually entitled to under its correct head.
Show more
Show less
What falls under each of the 5 heads?
The table below is the practical reference most people actually need — matching a specific income type to its correct head.
| Head | What it covers | Common examples |
|---|---|---|
| Salary | Income from an employer-employee relationship | Basic pay, HRA, bonus, perquisites |
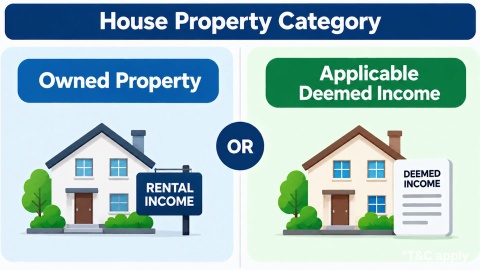
| House Property | Income from ownership of a building or land attached to it | Rental income, deemed rental value of a second self-occupied home |
| Business or Profession | Income from carrying on a business, trade or profession | Trading profit, consulting fees, professional practice income |
| Capital Gains | Profit from transferring a capital asset | Property sale profit, shares sold at a gain |
| Other Sources | Income not covered by the first 4 heads | Interest income, dividends, lottery winnings |
Rental income specifically sits under House Property, not Other Sources or Business Income, even though it might intuitively feel like passive "other" income to someone unfamiliar with this classification.
Show more
Show less
How do I classify income that seems to overlap?
Four questions, worked through in order, resolve most classification ambiguity.
- Ask whether the income comes from an employer-employee relationship. If yes, it is Salary, regardless of how the payment is described.
- Ask whether the income comes from owning a building or attached land. If yes, it is House Property income, even if you also actively manage the property.
- Ask whether the income comes from an ongoing trade, business or professional activity you actively carry on. If yes, it is Business or Profession income.
If none of the above apply and the income is not a capital gain, it falls under Other Sources by default.
A freelancer's consulting income is a common point of confusion under Section 14 of the Income Tax Act. It falls under Business or Profession, not Salary, since no employer-employee relationship exists, even if the client treats the arrangement informally like employment.
Show more
Show less
A worked example: classifying income across multiple heads
Consider Deepak, a 40-year-old professional in Hyderabad with a CIBIL Score of 748, who earns a salary, rents out a second property, and holds mutual fund investments generating dividends.
Formula used: Total income = Salary income + House Property income (after standard 30% deduction) + Other Sources income
| Income source | Head | Amount before head-specific deduction |
|---|---|---|
| Employer salary | Salary | Rs. 14,40,000/year |
| Rent from second property | House Property | Rs. 3,00,000/year |
| Mutual fund dividends | Other Sources | Rs. 40,000/year |
Deepak's rental income gets a standard 30% deduction (Rs. 90,000) before being added to his total income, a benefit his salary and dividend income do not receive under their own heads.
Show more
Show less
Home loan for professionals
Financing a second property across multiple income heads with Bajaj Finance
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 crore* |
| Tenure | Up to 32 years |
A lender assessing your home loan eligibility looks at income across the relevant heads, particularly Salary and House Property if you already hold rental property. Approval timelines can extend where income from multiple heads needs separate documentation, and minimum income thresholds can differ by city. Check your home loan eligibility with all your income sources correctly classified.
Show more
Show less
Frequently Asked Questions
Understanding the classification
Practical classification
Can the same income ever fall under two different heads at once?
No. Section 14 requires each specific item of income to be classified under exactly one head, even where the classification is not immediately obvious. Where genuine ambiguity exists, specific rules and case law guide which single head applies, but the income is never taxed twice under two separate heads for the same transaction.
Why does a self-occupied second home still count as House Property income?
Under specific rules, a second self-occupied property (beyond your first) can be treated as having a deemed rental value for tax purposes, even though you receive no actual rent. This closes what would otherwise be a gap where owning multiple homes for personal use avoided House Property taxation entirely, regardless of how many properties a taxpayer actually holds.
I run a small business alongside my full-time job. How is that income classified?
Your salary from employment falls under the Salary head, while your business income falls separately under Business or Profession. These are computed independently, with each head's own deductions applied before both are added together into your total income for the year.
Does classifying income under the wrong head just mean I pay the wrong amount, or something more serious?
In most cases, it means a wrong amount is paid rather than a compliance violation. However, some misclassifications, particularly claiming business-style expense deductions against salary income, can draw scrutiny and potential penalty on audit if the assessing officer determines the classification was made to reduce tax rather than through a genuine error. Correcting an honest misclassification voluntarily, before it is flagged, is treated more leniently than one caught on review, as a rule.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.