







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
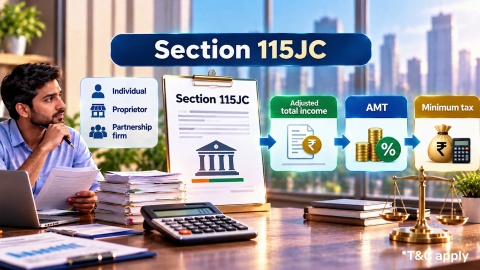
Section 115JC of Income Tax Act - How to Calculate Tax us 115JC
Last updated: Oct 2026
Section 115JC makes sure that a non-corporate taxpayer who claims large profit-linked deductions still pays a minimum tax. You pay the higher of your regular tax and the alternative minimum tax (AMT).
- Rate under Section 115JC: 18.5% of adjusted total income, plus surcharge and cess
- Trigger: deductions under Chapter VI-A Part C, Section 10AA or Section 35AD
- Threshold: AMT does not apply to an individual, Hindu Undivided Family (HUF), association of persons or body of individuals at Rs. 20 lakh or below
- Credit: AMT paid above regular tax is carried forward for 15 assessment years
Report: Form 29C from a Chartered Accountant
Compute both taxes before you file, and keep Form 29C ready. Section 80C and similar investments do not trigger AMT, so most salaried people never meet this section.
What is Section 115JC?
Section 115JC is the provision for alternative minimum tax. It applies to non-corporate persons, such as individuals, HUFs, firms, limited liability partnerships (LLPs) and co-operative societies. Companies pay minimum alternate tax under Section 115JB instead.
The Finance Act, 2016 introduced the section in its current form. Under the Income Tax Act, 2025, Sections 115JAA, 115JB and 115JC are replaced by Section 206.
Show more
Show less
Who has to pay AMT under Section 115JC?
You pay it only if you claim specific deductions, and the Rs. 20 lakh floor protects only certain taxpayers.
| Taxpayer | AMT applies if |
|---|---|
| Individual, HUF, association of persons, body of individuals | Adjusted total income is above Rs. 20 lakh and a specified deduction is claimed |
| Partnership firm or LLP | A specified deduction is claimed, with no Rs. 20 lakh floor |
| Co-operative society | A specified deduction is claimed, at 15% |
| Unit in an International Financial Services Centre (IFSC) | A specified deduction is claimed, at 9% |
The specified deductions are those under Chapter VI-A Part C (such as Section 80-IA), Section 10AA for special economic zones and Section 35AD for specified businesses. The rates for co-operative societies and IFSC units come from two third-party guides.
Show more
Show less
How do I calculate AMT under Section 115JC?
Add back the specified deductions to your total income, then apply 18.5%.
Formula used: Adjusted total income = total income + specified deductions. AMT = 18.5% × adjusted total income. Tax payable = higher of AMT and regular tax.
The figures below leave out surcharge and 4% cess.
| Case | Individual | LLP |
|---|---|---|
| Total income | Rs. 30,00,000 | Rs. 18,00,000 |
| Section 35AD deduction added back | Rs. 25,00,000 | Rs. 10,00,000 |
| Adjusted total income | Rs. 55,00,000 | Rs. 28,00,000 |
| AMT at 18.5% | Rs. 10,17,500 | Rs. 5,18,000 |
| Regular tax | Rs. 7,12,500 (old-regime slabs) | Rs. 5,40,000 (30%) |
| Tax payable | Rs. 10,17,500 | Rs. 5,40,000 |
| AMT credit | Rs. 3,05,000 | Nil |
The individual pays AMT because it is higher. The LLP pays its regular tax, because that is higher, so no credit arises.
Show more
Show less
How does the AMT credit work?
The excess of AMT over regular tax becomes a credit that you can carry forward for 15 assessment years. You use it in a year when your regular tax exceeds AMT.
Formula used: Credit set off in a year = lower of (credit available, regular tax − AMT of that year).
Section 115JD governs the credit, which is a prepayment of tax for the Section 115JC year. It carries no interest. In the individual's case above, Rs. 3,05,000 carries forward. In a later year with regular tax of Rs. 6,00,000 and AMT of Rs. 4,50,000, the set-off is limited to Rs. 1,50,000, and Rs. 1,55,000 remains.
Show more
Show less
Home loan for professionals
What forms and steps does AMT need?
AMT is applicable in the following scenarios:
- Taxpayers claiming deductions under sections such as 10AA (Special Economic Zone benefits) or 35AD (specified business deductions).
- Individuals or entities with adjusted total income exceeding Rs. 20 lakh.
- Companies and LLPs availing specified deductions.
Alternate Minimum Tax (AMT), replacing Form 29C. The earlier Form 67 used for claiming foreign tax credit has been replaced by Form 44. Do not confuse the two. See the guide to Form 67 and foreign tax credit.
Show more
Show less
A worked example: an individual with a Section 35AD claim
Consider Rajiv, a 48-year-old hotel owner in Nashik with a household income of Rs. 4.5 lakh a month and a CIBIL Score of 769. He claims Rs. 25 lakh under Section 35AD on a new specified business, and his total income is Rs. 30 lakh.
| Step | Amount |
|---|---|
| Adjusted total income | Rs. 55,00,000 |
| AMT | Rs. 10,17,500 |
| Regular tax | Rs. 7,12,500 |
| Pays | Rs. 10,17,500 |
| Credit carried forward | Rs. 3,05,000 |
His credit is not lost, but it is a prepayment. Rajiv asks his Chartered Accountant to plan the year when the credit is used. The tax-regime choice is explained in the guide to tax regime meaning.
Show more
Show less
Does AMT affect my home loan with Bajaj Finance?
Bajaj Finance assesses self-employed applicants on returns and financial statements. AMT paid reduces the income left after tax, so show it with your returns and the Form 29C.
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 crore* |
| Tenure | Up to 32 years |
Approval timelines can extend where returns show AMT or a credit that needs explaining, and minimum income thresholds can differ by city. Check your home loan eligibility.
Show more
Show less
Frequently Asked Questions
Applicability
Credit and forms
Does AMT apply to salaried employees?
Not unless they claim a specified deduction, which is rare for salaried people. AMT is triggered by deductions under Chapter VI-A Part C, Section 10AA or Section 35AD. Section 80C, 80D and similar deductions do not trigger it. A salaried person with a side business that claims Section 35AD should check with a Chartered Accountant.
Does the Rs. 20 lakh limit protect an LLP?
No. The Rs. 20 lakh floor applies only to individuals, HUFs, associations of persons and bodies of individuals. A firm or an LLP that claims a specified deduction can fall under AMT at any income. It pays the higher of regular tax and AMT, so compute both before you file.
How long can I carry forward AMT credit?
You can carry it forward for 15 assessment years, and you can set it off only in a year when regular tax is more than AMT. The set-off is limited to that difference. The credit earns no interest. Keep a year-wise record, because the set-off needs the AMT of the year in which the credit arose.
What is Form 29C?
Form 29C is the report from a Chartered Accountant that certifies adjusted total income and the AMT computation, under Rule 40BA. You file it before the return. Under the Income-tax Rules, 2026, the new Form 67 is listed as its replacement, so check the portal's forms list for the year before you file.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.