








Applicable for all Bajaj Finance loan products
Clear your overdue EMI today & protect your credit score
*T&C Apply
In Summary
Penal Charges: How They're Calculated
Penal interest on a fixed deposit generally means a reduction in the interest earned, with a possible penalty, when the deposit is withdrawn before its maturity date. It is different from current account charges, which relate to banking services, and from overdue loan charges, which arise when a loan repayment is not paid by its due date. Check the deposit terms before withdrawing early, and pay any overdue EMI through My Account, because closing an FD does not by itself clear an overdue loan amount or a legal notice.
- Premature withdrawal of an FD generally reduces the interest earned and does not reduce the principal invested.
- The interest and any penalty depend on the deposit terms and the period for which the deposit was held.
- Overdue loan charges are separate from FD penalties, and an unpaid EMI becomes overdue and is reported to credit bureaus.
- Closing an FD or moving money between accounts does not by itself resolve an overdue loan amount or a legal notice.
- Check the latest loan statement, pay the full overdue amount through My Account or the app, and keep the receipt.
- Check the FD terms and any link to a loan before you withdraw early.
What is penal interest on a fixed deposit?
Penal interest on a fixed deposit generally means a reduction in the interest earned when the deposit is withdrawn before its agreed maturity date. The treatment depends on the institution's policy and the terms provided when the deposit was opened, and the penalty is disclosed when the deposit is accepted. When a deposit is closed early, the interest is generally based on the rate for the period it was held, not on the original rate. If a deposit is withdrawn before the minimum period, no interest may be payable.
Early withdrawal can therefore mean lower interest, a penalty or reduced proceeds. Check the deposit terms and the policy before you withdraw.
Premature withdrawal reduces the interest you earn, not your principal
Withdrawing a fixed deposit before its maturity date generally does not reduce the principal you invested, but it can reduce the interest you earn. The interest may be recalculated at the rate for the period the deposit was actually held, and a penalty may apply under the institution's terms. For example, a deposit planned for two years but withdrawn after one year is paid interest at the rate applicable for one year, less any penalty. Penalty and interest rates vary with the institution's policy, the deposit period and the product, and some deposits have specific conditions for partial withdrawal or particular customer categories.
What are current account charges?
Current account charges are fees that may apply to specific banking services, transactions or account requirements. They are separate from premature withdrawal charges on a fixed deposit, and the institution discloses them in its schedule of charges. Common charges may relate to:
- Account requirements: Not meeting the conditions of the account.
- Cheque services: Cheque processing, other cheque services or returned cheques.
- Cash transactions: Cash deposits or withdrawals beyond specified limits.
- Account services: Statements or other service requests.
- Remittances: Certain fund transfers and transaction services.
- Account closure: Closing the account, where it applies.
Check the schedule of charges and terms before assuming a fee applies, as charges vary by institution and account type.
How do FD penalties, account charges and overdue loan charges differ?
These charges apply in different situations and should be checked separately. A fixed deposit penalty applies if you close a deposit before maturity, and current account charges relate to services or account conditions. Overdue loan charges arise when a required loan repayment is not paid by its due date. The table sets out each one and what to check.
| Product or situation | Nature of charge | When it may apply | What to check |
|---|---|---|---|
| Fixed deposit | Premature withdrawal penalty or reduced interest | The FD is withdrawn before maturity | FD terms and the premature withdrawal policy |
| Current account | Service or account charge | A chargeable service or account condition applies | The account's schedule of charges |
| Overdue loan account | Penal or other overdue charges | A required loan repayment is not paid by its due date | The loan agreement and latest statement |
| Matured FD | Interest treatment on unpaid proceeds | The deposit has matured but the proceeds remain unpaid | The deposit terms and interest policy |
For loans, the term used is penal charge. The penal interest calculation page explains how it works.
What if you have an overdue loan and a fixed deposit?
Overdue loan charges and fixed deposit penalties are separate, and one does not settle the other. If a loan EMI is not paid by its due date, it becomes overdue and can attract penal charges as set out in your loan agreement. The overdue status is reported to credit bureaus in the lender's regular reporting cycle, and a later payment does not remove the earlier entry. Withdrawing a fixed deposit early to pay an overdue EMI means accepting the reduced interest, so check the deposit terms, and any link between the deposit and the loan, first.
Closing an FD or moving money between accounts does not by itself resolve the amount in a legal notice. Read the notice, check the amount against your latest loan statement, and respond within the stated timeline. If you are not able to pay in full, contact the lender early through Help and Support to understand the options for your loan. Any option is subject to the lender's assessment and is not guaranteed.
Your rights as a borrower include the following:
- Recovery agents may contact you only between 8:00 AM and 7:00 PM.
- Recovery communication must not include threats or harassment.
- You can raise a grievance with the lender and, if it stays unresolved, escalate it through the RBI Integrated Ombudsman Scheme (cms.rbi.org.in).
How to check and pay an overdue loan amount
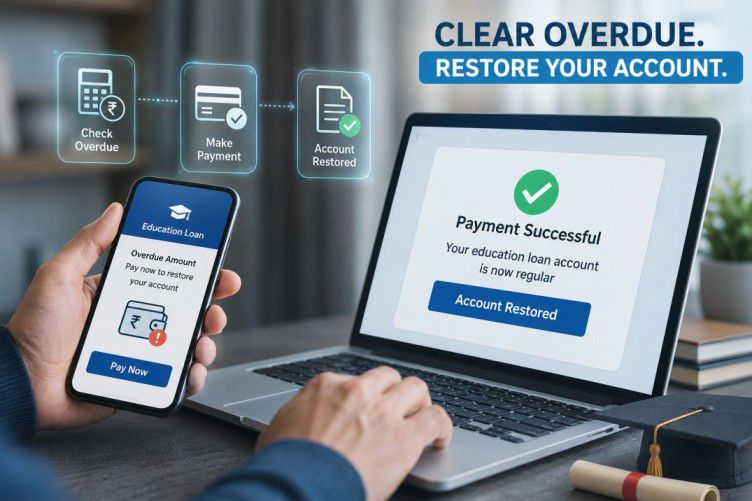
Check your loan account before you make a payment, so that you know the outstanding amount, any overdue amount and the charges. You can do this in My Account or the app.
- Open My Account or the app and sign in using your registered mobile number and OTP.
- Verify your details with your date of birth.
- Go to Service and select your loan under Your Relations.
- Review the outstanding amount, overdue amount and charges in the loan details.
- Choose Make loan payments, then Missed instalments or Other overdues, and pay using UPI, net banking or a debit card.
- If you need clarification, go to Help and Support and raise a request.
Loan Repayment and Account Management Guides
Not your nearest branch?

Frequently Asked Questions
Fixed deposits and account charges
Overdue loans and fixed deposits
What happens to the interest when a fixed deposit is renewed?
The interest rate after renewal may differ from the rate on the original deposit. A renewed deposit is generally governed by the terms and rate applicable on the renewal date.
What should you check before closing a fixed deposit early?
The premature withdrawal terms, applicable interest rate, penalty conditions, completed deposit period and expected proceeds should be checked before an FD is closed early. This shows the financial impact before closure is requested.
How does premature withdrawal affect fixed deposit maturity proceeds?
Premature withdrawal can reduce the interest payable compared with the original maturity calculation. The final proceeds depend on the applicable rate, the deposit period and any premature withdrawal conditions.
What happens if a fixed deposit is linked to a loan?
A fixed deposit linked to a loan may be subject to specific terms on withdrawal and on how it relates to the loan. The loan and deposit documents should be reviewed before any withdrawal or closure is requested.
Where can you find the applicable charges for a current account?
The institution's schedule of charges and account terms generally list the current account charges. Reviewing them shows the charges for services, transactions and account requirements.
Is penal interest on a loan the same as the penalty on a fixed deposit?
An FD penalty is a reduction in interest when a deposit is withdrawn before maturity. Penal charges on a loan apply when an EMI is not paid by its due date. The two are separate and are checked against different documents.
Can I break a fixed deposit to pay an overdue EMI?
A fixed deposit can be withdrawn early under its terms, which may reduce the interest earned. The overdue EMI stays overdue until the full amount is paid, so the deposit terms, including any link to a loan, should be checked first.
Does closing a fixed deposit stop a legal notice?
Closing a fixed deposit does not by itself resolve a legal notice. The notice refers to a specific loan amount, so the latest loan statement should be checked against it and a response made within the stated timeline.
More Articles

Disclaimer
While care is taken to update the information, products, and services included in or available on our website and related platforms/websites, there may be inadvertent inaccuracies or typographical errors or delays in updating the information. The material contained in this site, and on associated web pages, is for reference and general information purpose and the details mentioned in the respective product/service document shall prevail in case of any inconsistency. Subscribers and users should seek professional advice before acting on the basis of the information contained herein. Please take an informed decision with respect to any product or service after going through the relevant product/service document and applicable terms and conditions. In case any inconsistencies observed, please click on reach us.
*Terms and conditions apply.