







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
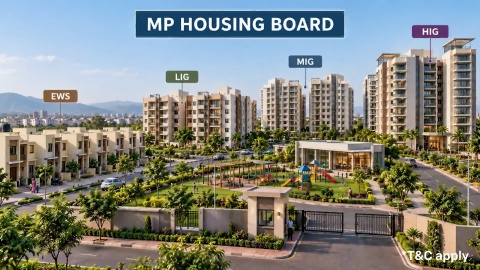
MP Housing Board Scheme
In summary
Last Updated: September 2026
MPHIDB and PMAY-MP are often confused, but they're structurally different — one allots housing directly, the other subsidises a home loan on a separately purchased property.
- Full name: Madhya Pradesh Housing and Infrastructure Development Board
- Function: direct development and allotment of residential units across the state
- Active projects: 461 units in Shivpuri; approximately 15,000 planned in Jabalpur
- Distinct from PMAY-MP, which offers loan interest subsidy rather than direct allotment
Allotment method: application-based, commonly through a computerised draw for oversubscribed schemes
Confirm which specific MPHIDB scheme is currently active in your target city before applying, since availability varies significantly by location and timing.
Is MPHIDB the same as PMAY in Madhya Pradesh?
No, and this distinction genuinely matters for how you'd actually apply. MPHIDB is a state body that develops and directly allots housing units it has built; PMAY-MP is a central scheme offering interest subsidy on a home loan for a property purchased through the open market or a private developer.
The realistic housing options for an MP resident are:
- Apply for an MPHIDB-developed unit directly, going through the board's own allotment process
- Buy a property independently and separately check PMAY-MP subsidy eligibility for the home loan
Combine both where applicable, if an MPHIDB unit's purchase also happens to qualify for PMAY-MP subsidy under the scheme's specific terms
Confirming which path fits your situation before applying saves the effort of pursuing the wrong process for your actual goal. A resident who applies to MPHIDB expecting an interest subsidy, or applies for PMAY-MP expecting direct government allotment, is pursuing the wrong mechanism for that specific expectation.
Show more
Show less
What does MPHIDB currently offer?
| Attribute | Detail |
|---|---|
| Full name | Madhya Pradesh Housing and Infrastructure Development Board |
| Function | Direct development and allotment of residential units |
| Shivpuri project | 461 units |
| Jabalpur project | Approximately 15,000 units planned |
| Allotment method | Application-based, often via computerised draw |
MPHIDB's project pipeline varies by city and time — a scheme active in one city today may not have an equivalent currently open elsewhere in the state, which is why checking current, location-specific availability matters more than assuming statewide uniform access. Following the board's official communication channels directly, rather than relying on informal word-of-mouth about scheme availability, is the more reliable way to catch a new launch in your specific city.
Show more
Show less
How do I apply for an MPHIDB scheme?
- Identify current active MPHIDB schemes in your target city through the board's official channels.
- Confirm the specific scheme's eligibility criteria — income category, residency, and any priority conditions.
- Submit your application with required documents — identity, address, and income proof.
- Pay the applicable registration or application fee.
- Track your application status and await the allotment draw result where applicable.
On selection, complete the payment schedule and documentation required for possession.
Applications submitted with complete, correctly formatted documentation move through verification faster than those requiring follow-up for missing paperwork.
Show more
Show less
A worked example: applying for a Jabalpur MPHIDB unit
Consider Sanjay, a 37-year-old government employee in Jabalpur with a household income of Rs. 62,000 a month and a CIBIL Score of 743, applying for a unit under MPHIDB's Jabalpur housing pipeline.
| Step | What Sanjay did |
|---|---|
| Checked eligibility | Confirmed his income category matched the scheme's stated criteria |
| Applied | Submitted documentation and paid the application fee |
| Selected | Allotted a unit through the scheme's draw process |
| Financed | Applied for a Bajaj Finance home loan to cover the balance beyond his down payment |
Because MPHIDB is a government body with an established allotment process, Sanjay's lender's legal verification moved without the additional complexity that can arise in a private resale transaction. Sanjay also kept his allotment letter and payment schedule filed alongside his loan documents, since his lender referenced both directly when structuring his disbursement.
Financing your MPHIDB unit with Bajaj Finance
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.* |
| Loan amount | Up to Rs. 15 Crore* |
| Tenure | Up to 32 years |
Bajaj Finance offers home loans usable against an MPHIDB allotment, structured around the board's own payment schedule. Check your home loan eligibility before applying to a specific scheme.
Frequently Asked Questions
Understanding MPHIDB
Financing an MPHIDB unit
Can I apply for both an MPHIDB unit and PMAY-MP subsidy at the same time?
Potentially, depending on the specific scheme's terms and your eligibility for both separately — they are administered independently, so check both sets of criteria rather than assuming one automatically covers the other.
Are MPHIDB schemes available in every Madhya Pradesh city?
No. Availability varies by city and time, with active projects concentrated in specific locations like Shivpuri and Jabalpur at any given point. Check the board's current scheme listings for your specific target city before assuming a scheme is available.
Does MPHIDB income eligibility affect my Bajaj Finance Home Loan eligibility?
No, they're assessed independently. MPHIDB's income category determines which scheme you can apply for; Bajaj Finance's loan eligibility is assessed separately based on your income, obligations, and credit score.
Can I get a home loan for an MPHIDB unit still under construction?
Yes, provided the scheme's terms allow financing during construction — confirm with both MPHIDB and your lender how the payment schedule aligns with a construction-linked disbursement structure.
Home loan for professionals
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles


Watch our videos
Documents required to get a Bajaj Finserv Home Loan

Tips to increase your Home Loan eligibility

Things you need to know about pre-approved home loan

Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.