







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
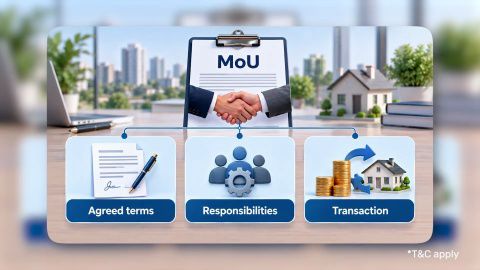
A Detailed Guide on Memorandum of Understanding (MOU)
An MOU (Memorandum of Understanding) records the parties’ intent and preliminary agreement, often before a formal contract is drafted. Its legal enforceability depends on its actual language and content, not simply its title.
- Key elements include the parties involved, purpose, scope, responsibilities and timeline.
- Common uses include business partnerships, joint ventures, property pre-agreements and government or institutional collaborations.
- An MOU is different from an MOD (Memorandum of Deposit of Title Deed), which is a home-loan mortgage security document.
- In property transactions, an MOU may precede a formal sale agreement, so it is important to understand what it does and does not commit you to before signing.
What is a Memorandum of Understanding?
A Memorandum of Understanding is a document recording a mutual agreement or understanding between two or more parties, outlining the general terms of a planned collaboration in most cases before a formal, legally binding contract is executed.
| Attribute | Detail |
|---|---|
| Purpose | Records preliminary agreement and mutual intent |
| Typical stage | Before a formal, binding contract |
| Legal status | Depends on content and wording, not the "MOU" label alone |
| Common contexts | Business partnerships, joint ventures, property pre-agreements, institutional collaborations |
The critical point often misunderstood: simply calling a document an "MOU" doesn't automatically make it non-binding. Courts look at the actual language and the parties' demonstrated intent to determine enforceability, not the title on the page.
This distinction has practical consequences beyond legal theory — parties who assume their "MOU" carries no real obligations, purely because of its label, can find themselves bound by specific clauses within it that a court reads as sufficiently definite and intended to create legal relations, regardless of what the document is called at the top of the page.
Show more
Show less
Is an MOU legally binding?
This is the single most common question about MOUs, and the honest answer is: it depends entirely on the document's specific content, not its label.
| Factor | Leans toward binding | Leans toward non-binding |
|---|---|---|
| Language used | "Shall," "agrees to," definitive commitments | "Intends to," "may," aspirational language |
| Specificity | Detailed, specific terms and obligations | General, high-level statements of intent |
| Consideration | Clear exchange of value or obligation | No exchange of value specified |
| Explicit statement | Silent on enforceability, or states binding intent | Explicitly states "non-binding" or "subject to a formal agreement" |
Because of this ambiguity, careful drafting matters — a party wanting a genuinely non-binding preliminary understanding should say so explicitly in the document itself, rather than assuming the "MOU" title alone provides that protection.
This is exactly why legal review of an MOU, even a seemingly simple or preliminary one, is worth the modest cost involved — a party who skips this step because "it's just an MOU" is precisely the party most likely to be surprised later by an unintended binding obligation buried in otherwise routine-sounding language.
Show more
Show less
Key elements of a well-drafted MOU
A clear, well-structured MOU includes several standard elements as a rule, regardless of the specific context it's used for.
- Parties involved: Full legal names and details of all parties to the understanding.
- Purpose and background: Why the parties are entering into this understanding, and the broader context.
- Scope of collaboration: What the arrangement covers, and — often more importantly — what it explicitly does not cover.
- Roles and responsibilities: What each party is expected to contribute or do.
- Timeline: Key dates, including how long the MOU itself remains valid.
- Confidentiality provisions: Where relevant, what information must be kept confidential.
- Termination clause: How either party can exit the understanding, and under what conditions.
- Binding/non-binding statement: An explicit statement of whether the document, or specific clauses within it, are intended to be legally binding.
The binding/ non-binding statement specifically is worth treating as mandatory rather than optional — its absence is precisely what creates the ambiguity that leads to later disputes about what the parties actually agreed to.
Show more
Show less
MOU in property transactions
In real estate specifically, an MOU sometimes appears as a preliminary document before a formal sale agreement, and understanding its actual role matters for anyone encountering one during a property transaction.
- What it covers, in most cases: Broad terms — the property, an agreed price range, and a general timeline for moving to a formal agreement
- What it doesn't replace, as a rule: The formal, registered sale agreement and sale deed, which remain the legally operative documents for the actual transfer
- Earnest money: Sometimes accompanies an MOU as a token commitment, though its treatment (refundable or not) should be explicitly stated
- Risk for buyers: Treating an MOU as equivalent to a binding sale agreement, when it may not be, can lead to a false sense of security about the transaction's certainty
A buyer or seller should never treat a property MOU as a substitute for the formal registered sale agreement — it's a preliminary step, and its specific terms determine how much protection it actually offers if the other party doesn't follow through.
Show more
Show less
Home loan for professionals
A worked example: an MOU before a property sale
Consider Nikhil, a 43-year-old business consultant in Pune with a household income of Rs. 1.9 lakh a month and a CIBIL Score of 763, who signs an MOU with a seller for a Rs. 1.2 crore property, ahead of finalising his home loan and the formal sale agreement.
| Element | What Nikhil's MOU specified |
|---|---|
| Price | Rs. 1.2 crore, agreed and stated |
| Earnest money | Rs. 5 lakh, explicitly stated as refundable if the sale doesn't proceed due to loan rejection |
| Timeline | 60 days to complete the formal sale agreement, contingent on loan approval |
| Binding statement | Explicitly non-binding on the final sale, but earnest money terms stated as binding |
Because the MOU explicitly addressed what happens if his loan application isn't approved, Nikhil has clarity on his earnest money's fate before committing it — a protection that a vaguely worded MOU, silent on this specific scenario, would not have provided. This single clause — tying earnest money refundability to loan approval — is exactly the kind of specific, foreseeable-risk provision that separates a genuinely useful MOU from one that merely restates goodwill without addressing what happens if things don't go as planned.
Show more
Show less
How an MOU fits into your property purchase and home loan timeline
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.* |
| Loan amount | Up to Rs. 15 Crore* |
| Tenure | Up to 32 years |
If your property purchase involves an MOU before the formal sale agreement, ensure it explicitly addresses what happens to any earnest money if your home loan application isn't approved — this protects you from losing a deposit over a financing outcome outside your direct control. Check your home loan eligibility before committing to any preliminary agreement.
Show more
Show less
Frequently Asked Questions
Understanding MOUs
Property-related MOUs
Is an MOU the same as a Letter of Intent (LOI)?
They're closely related and sometimes used interchangeably, though an LOI is often viewed as slightly more formal and closer to signalling a firm intention to proceed, while an MOU more commonly documents a mutual understanding between parties still working out terms. In practice, the specific document's content matters more than which label is used.
Can I be sued for breaching a non-binding MOU?
Not as a rule, for the core commitments themselves, if the document is genuinely and explicitly non-binding. However, specific clauses — like confidentiality provisions or an earnest money arrangement — can still be enforceable even within an otherwise non-binding MOU, if they're drafted as standalone binding commitments. Read the specific clauses carefully rather than assuming the whole document carries one uniform status.
Should I pay earnest money before or after signing an MOU?
This varies by transaction, but the earnest money terms — amount, refundability, and the specific conditions under which it's forfeited or returned — should always be explicitly stated in the MOU itself before any payment changes hands, rather than relying on a verbal understanding.
Is a Memorandum of Understanding the same as MOD used in home loans?
No — these are entirely different documents despite the similar-sounding names. An MOU is a preliminary agreement document used across many contexts, including property transactions. MOD (Memorandum of Deposit of Title Deed) is a specific mortgage security document created when a borrower deposits property title deeds with a lender as collateral for a home loan — the two serve completely different legal purposes.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.