








What is Yield to Maturity & Why it Matters
-
In summary
A loan against bonds lets you borrow against eligible bond holdings without selling them. Your bonds remain pledged as collateral while you use the sanctioned funds.
- LTV ratio: For a loan against bonds in India, lenders may provide 60%–80% of the bond value, depending on the security.
- Eligible bonds: Government bonds, corporate bonds, tax-free bonds, and other approved listed bonds may be accepted.
- Interest rate: A loan against debt securities may carry an interest rate of 8%–14% p.a., based on the lender and pledged bonds.
- Basic eligibility: Applicants must meet the lender’s age, income, residency, credit, and security-ownership requirements.
- Required documents: Common documents include PAN, address proof, income details, bank statements, and proof of bond ownership.
Check your eligibility for a loan against bonds online with Bajaj Finance and review the applicable terms before applying.
-
What is yield-to-maturity
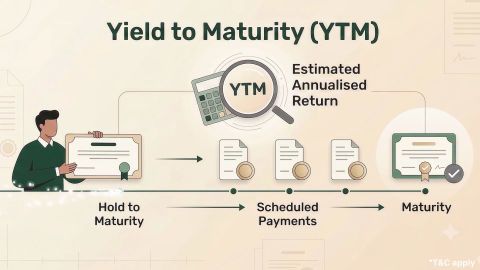
Yield to maturity is the discount rate that equates a bond’s market price with its future cash flows. These cash flows include every remaining coupon payment and the face value repaid at maturity. YTM is expressed as an annualised percentage. It represents the return expected when the investor holds the bond until maturity. The calculation assumes the issuer makes every scheduled interest and principal payment. It also assumes the investor reinvests each coupon payment at the same YTM.
For example, a bond may have a 7% coupon rate but trade below its face value. Its YTM may exceed 7% because the investor also receives a capital gain at maturity. A bond trading above face value may have a YTM below its coupon rate. The investor receives the face value at maturity, which is lower than the purchase price. YTM is sometimes called redemption yield or book yield. However, it should not be confused with current yield or the coupon rate.
If you are looking for a safe investment option, you can consider fixed deposit. They offer guaranteed returns and a fixed interest rate throughout your investment tenure.
Why is yield to maturity important?
Avoid these mistakes while booking FD
-
YTM helps investors compare bonds using one annualised measure. This is useful because two bonds may have different coupons, prices, and maturity dates. The coupon rate only measures annual interest against the bond’s face value. It does not consider the current market price or the gain or loss at maturity. Current yield considers the market price but ignores the maturity gain or loss.
YTM includes the market price, coupons, face value, and remaining tenure.
Measure What it considers Basic calculation Coupon rate Annual coupon and face value Annual coupon ÷ face value Current yield Annual coupon and market price Annual coupon ÷ market price Yield to maturity Price, coupons, face value, and tenure Discount rate on all future cash flows YTM therefore provides a broader comparison than either the coupon rate or current yield. However, investors should compare bonds with similar credit quality, structure, and maturity. A higher YTM does not automatically make one bond more suitable than another.
How do YTMs work?
-
YTM works by discounting every future bond payment to its present value. The calculated present value must equal the bond’s current market price.
The exact relationship is:
Bond price = Present value of all coupon payments + Present value of the face value
For an annual coupon bond, the formula is:
P = C ÷ (1 + YTM)¹ + C ÷ (1 + YTM)² + … + (C + F) ÷ (1 + YTM)ⁿ
Where:
- P: Current market price
- C: Annual coupon payment
- F: Face value
- n: Remaining years until maturity
- YTM: Yield to maturity
The exact YTM cannot usually be isolated through simple rearrangement.
Financial calculators, spreadsheets, and bond platforms solve it through iteration.
A commonly used approximation is:
Approximate YTM = [C + (F − P) ÷ n] ÷ [(F + P) ÷ 2] × 100
This formula provides an estimate rather than the exact internal rate of return.
-
Why is yield-to-maturity useful
YTM helps investors evaluate bond returns beyond the stated coupon rate.
Its main uses include:
- Bond comparison: YTM helps compare bonds with different coupons, prices, and maturity dates.
- Discount evaluation: It shows how a discounted purchase price affects the expected annualised return.
- Premium evaluation: It reflects the maturity loss when a bond is purchased above face value.
- Portfolio planning: Investors can compare the estimated return with their investment period and income requirements.
- Market assessment: YTM reflects how market rates and bond prices affect expected returns.
- Issuer pricing: Issuers can review yields on comparable bonds when pricing a new issue.
- Credit assessment: A high YTM may signal greater perceived credit risk when comparable bonds have lower yields.
YTM works best when used with credit ratings, duration, liquidity, and bond terms.
Also Read: Difference Between Yield and Interest Rate
-
Yield to Maturity in the investment landscape
YTM provides a common measure across many fixed-income securities. However, it should form only one part of the evaluation.
Fixed-income investments
Investors can use YTM to compare government securities and corporate bonds with similar characteristics. The comparison should consider credit quality, maturity, coupon structure, liquidity, and embedded options. A corporate bond may offer a higher YTM than a government security. The difference may compensate for greater credit risk, lower liquidity, or both. A higher number alone does not establish that the bond offers better value.
Long-term planning
YTM can help investors estimate the annualised return from holding a bond until maturity. Investors can compare this estimate with the timing of future financial goals. However, reinvestment rates may change during the holding period. The issuer may also call the bond early when the bond terms allow it. Investors should therefore match maturity, cash flows, and risk with their planned requirements.
-
Yield to maturity example
Suppose an investor buys a bond for Rs. 900. The bond has a face value of Rs. 1,000 and matures after five years. It pays an annual coupon of Rs. 80. The investor receives Rs. 80 each year and Rs. 1,000 at maturity. As the bond was purchased below face value, the investor also receives a Rs. 100 maturity gain.
The approximate YTM is:
Approximate YTM = [80 + (1,000 − 900) ÷ 5] ÷ [(1,000 + 900) ÷ 2] × 100
Approximate YTM = [80 + 20] ÷ 950 × 100
Approximate YTM = 10.53%
The exact YTM is approximately 10.68% when calculated by discounting every cash flow. This difference shows why the simplified formula should be treated as an approximation.
-
Conclusion
Yield to maturity estimates a bond’s annualised return when it is held until maturity. It considers the market price, coupons, face value, and remaining tenure. However, the estimate assumes timely payments and reinvestment at the same yield. Actual returns may differ because of default, early sale, call provisions, costs, taxes, or changing reinvestment rates.Use YTM with credit quality, duration, liquidity, and bond terms before comparing investments.
-
Calculate your expected investment returns with the help of our investment calculators
Investment Calculator Fixed Deposit calculator RD Calculator Gratuity Calculator Sukanya Samriddhi Yojana Calculator EPF Calculator Public Provident Fund Calculator
Check out different FD Rates
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles
Frequently Asked Questions
Overview
What is yield to maturity (YTM) and how is it calculated?
Yield to maturity is the annualised return an investor earns if a bond is held until maturity and all payments are reinvested at the same rate. The simplified YTM formula is: [Annual coupon + (Face value − Market price) ÷ Years to maturity] ÷ [(Face value + Market price) ÷ 2] × 100. This bond yield is an estimate and may differ from the realised return.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.