








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
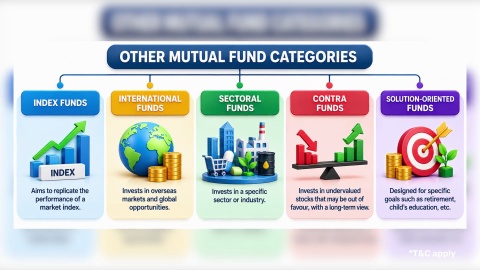
Types of Mutual Funds Explained- Which One Should You Choose
In summary
Idle funds are money that is not currently being invested or earning meaningful returns. Keeping some cash aside can be useful, but leaving surplus money unused for long periods can have an opportunity cost.
- Idle funds can provide quick access to cash.
- Inflation can reduce the purchasing power of uninvested money over time.
- Emergency savings should not automatically be invested.
- Matured investments can become idle if you do not redeploy the money.
- The right use of surplus cash depends on your goal and timeframe.
As of August 2026, India's mutual fund industry had Rs. 87.08 lakh crore in net assets.
Idle funds are not necessarily wasted money. Cash kept for an emergency, a near-term expense, or a planned purchase has a purpose even when it is not invested.
The important question is whether your money is sitting unused when you could reasonably put it to a suitable use.
What are idle funds?
Idle funds are amounts that are not currently being spent, saved for a defined near-term need, or invested in an income-generating asset. They may also include money earning a return that is significantly below what is appropriate for the owner’s goal and risk capacity.
Idle funds are also called idle cash, idle money, or surplus cash. They may belong to individuals, businesses, trusts, or government bodies.
However, not all uninvested money is wasted. Cash kept for emergencies, operating expenses, taxes, or an upcoming purchase serves a specific purpose. It provides liquidity, which means the money can be accessed quickly when required.
How do idle funds affect your finances?
Idle funds may create an opportunity cost. Opportunity cost is the potential benefit you give up by keeping money in one place instead of using another suitable option.
Money in an appropriate savings or investment product may earn interest, dividends, or market-linked returns. Reinvested earnings may also benefit from compounding, where returns can generate additional returns over time.
However, compounding requires positive returns and sufficient time. It does not guarantee growth, particularly in market-linked investments.
Inflation is another concern. When prices rise, the same amount of money buys fewer goods and services. SEBI provides an inflation calculator to demonstrate how future costs may increase, while RBI has noted that sustained inflation can erode purchasing power.
What is the value of idle funds over time?
The nominal value of physical cash remains unchanged. For example, Rs. 1 lakh kept at home will still be Rs. 1 lakh after one year.
Its real value may decline if prices rise during that year. This means the money may purchase fewer goods and services than before.
Consider an illustrative comparison. If Rs. 1 lakh earns a hypothetical simple annual return of 6.5%, it may generate Rs. 6,500 before tax and other conditions. If the same amount remains as cash, it generates no financial return.
This is only a mathematical illustration. It does not represent a current savings-account rate, investment recommendation, or guaranteed return.
Also read: Types of investment in India
What are some real-life examples of idle funds?
Idle funds can appear in personal and business finances. The following examples show where unused money may accumulate.
| Example | Why it may be idle | What to check |
|---|---|---|
| Excess current-account balance | It may earn no interest and exceed operating needs | Upcoming payments and business liquidity |
| Matured investment proceeds | Money may remain unallocated after maturity | Goal, timeline, tax, and reinvestment options |
| Unused physical cash | It earns nothing and faces theft or loss risk | Emergency requirement and safe storage |
| Unclaimed amounts | The owner may have forgotten or lost track of the funds | Claim process, records, and applicable interest |
| Excess savings-account balance | The amount may exceed emergency and near-term requirements | Interest rate, inflation, and available alternatives |
Provident fund balances should not automatically be described as idle. Their interest treatment depends on the member’s age, account status, and applicable EPFO rules. EPFO states that current interest treatment can differ for inoperative accounts and members approaching the specified age.
Tax treatment can also affect the return you retain.
Also read: What is direct tax code
What are the benefits of keeping some funds accessible?
Keeping part of your money liquid can be useful when it serves a defined purpose. The benefit comes from accessibility rather than high returns.
The main potential benefits are:
- Emergency access: Accessible money can help cover medical costs, income loss, repairs, or urgent family expenses.
- Planned payments: Individuals and businesses may need cash for taxes, salaries, rent, fees, or upcoming purchases.
- Reduced forced selling: An emergency reserve can help you avoid selling investments during an unfavourable market.
- Financial flexibility: Available cash may help you respond to changing household or business needs.
- Lower market exposure: Money required soon may be protected from short-term market fluctuations when kept outside market-linked investments.
SEBI recommends maintaining an emergency fund before investing. It also advises having stable income for daily expenses and suitable insurance protection.
What are the disadvantages of excess idle funds?
Keeping more idle money than necessary can affect long-term financial progress. The impact depends on the amount, duration, inflation, and available alternatives.
The main disadvantages include:
- Opportunity cost: You may lose the chance to earn interest or market-linked returns from a suitable financial product.
- Reduced purchasing power: Inflation can make the same amount of money less useful over time.
- Missed compounding: Money earning no return cannot benefit from reinvested earnings.
- Physical security risk: Cash kept at home can be lost, stolen, or damaged.
- Delayed goals: Excess idle money may slow progress towards education, retirement, housing, or other objectives.
- Lack of structure: Unallocated cash can make it difficult to distinguish emergency savings from investible surplus.
For families using different ownership structures, the person or entity holding the money may affect documentation and taxation.
See What is Hindu Undivided Family for related information.
How should you manage idle funds?
Start by dividing your money according to when and why you may need it. Do not move the entire balance into an investment simply to avoid the idle-funds label.
You can follow these steps:
- Identify the purpose: Separate money for household expenses, emergencies, taxes, planned purchases, and long-term goals.
- Estimate the timeline: Determine whether you need the money immediately, within a few months, or after several years.
- Keep emergency money accessible: Use an account or product that prioritises liquidity and capital access.
- Repay expensive debt: Compare potential investment returns with the certain cost of high-interest borrowing.
- Review suitable options: Compare liquidity, risk, costs, taxation, and withdrawal conditions before moving surplus funds.
- Avoid market timing: Waiting indefinitely for a market correction can leave money unused without improving the eventual investment decision.
- Review periodically: Reassess surplus cash when your income, expenses, goals, or responsibilities change.
A written allocation can help you see which amount is genuinely idle and which amount serves a valid financial purpose.
Can mutual funds be used for idle money?
Mutual funds may be considered for surplus money when the selected scheme matches your goal, horizon, and risk capacity. They are not suitable for every emergency or near-term requirement.
Liquid funds invest in debt and money market instruments with maturities of up to 91 days. However, they remain market-linked and can carry interest-rate, credit, and liquidity risks. Exit loads may also apply in some cases.
For longer-term goals, different debt, hybrid, or equity schemes may be considered according to their objectives and Riskometer. Learn how to choose mutual funds before investing.
Conclusion
Idle funds are not simply any money outside an investment. Cash kept for emergencies, immediate expenses, or defined short-term goals provides valuable liquidity.
The concern arises when surplus money remains unused for long periods without a clear purpose. Review such funds against your goals, debt, emergency needs, investment horizon, and risk capacity. Choose an appropriate financial product only after checking its costs, access conditions, taxation, and risks.
The Bajaj Broking website offers access to 4,000+ mutual fund schemes through SIP and lumpsum modes. KYC is mandatory. You can use an online lumpsum calculator or a SIP calculator from Bajaj Finance for illustrations, but calculated returns are not guaranteed.
Essential tools for mutual fund investors
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Managing and using idle funds
Idle money, returns, and emergencies
How do you manage idle funds?
Separate money needed for emergencies and short-term expenses. Then identify the remaining surplus, repay expensive debt, and compare suitable savings or investment options based on liquidity, risk, taxation, costs, and your goal timeline.
What is the best option for me to activate idle funds?
There is no single suitable option for everyone. Your choice depends on when you need the money and your risk capacity. Options may include interest-bearing accounts, deposits, or mutual funds available through the Bajaj Broking website.
Can idle funds ever improve your money?
Idle funds do not generate financial returns when held as cash. However, accessible money can support emergencies, planned payments, and business expenses. Its value comes from liquidity rather than investment growth.
How can idle money affect long-term investment returns?
Excess idle money may reduce long-term portfolio growth because it misses potential returns and compounding. Inflation can also reduce its purchasing power. However, investment returns remain market-linked and are never guaranteed.
Should emergency funds be treated as idle funds?
No. Emergency funds have a clear purpose and should remain accessible for unexpected expenses. They should not be invested in unsuitable long-term or volatile assets merely to earn higher potential returns.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.