








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
Alternative Investment Options
In summary
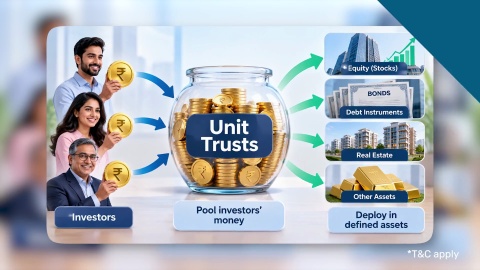
A unit trust pools money from multiple investors and holds investments through a trust structure. In India, mutual funds are constituted as trusts, with trustees overseeing the fund and an Asset Management Company managing investments.
- You invest by buying units that represent your interest in the scheme.
- The fund can invest across asset classes such as equity, debt, and money market instruments.
- Your investment value changes with the value of the underlying portfolio and applicable NAV.
- Professional management and diversification can simplify investing, but neither removes market risk.
- Unit Trust of India was established in 1963 as India’s first mutual fund institution.
The term “unit trust” can have different meanings across countries. For an Indian investor, it is important to distinguish the general trust structure of mutual funds from specific products or institutions called unit trusts.
What is a unit trust?
A unit trust is a trust-based investment structure in which investors hold units representing their interest in the underlying assets. The pooled money can then be invested according to the trust or scheme’s stated objective.
In India, mutual funds are constituted in the form of trusts. The structure includes a sponsor, trustees, an Asset Management Company (AMC), and a custodian. The trustees hold the property of the mutual fund for the benefit of unitholders, while the AMC manages the investments. Source: SEBI, mutual fund regulatory framework.
You can read more about mutual funds, investment management, and mutual fund units.
How does a unit trust work?
The basic process involves pooling investor money, investing it according to the stated objective, valuing the portfolio, and allocating ownership through units.
For example, suppose Riya invests Rs. 20,000 in a mutual fund scheme. If the applicable NAV is Rs. 20, she would receive 1,000 units, before considering applicable charges or other factors. If the NAV later becomes Rs. 22, the value of her units would be Rs. 22,000, before applicable charges and taxes.
The NAV represents the per-unit value of the scheme’s net assets. You can learn more about NAV and asset classes.
How is a unit trust managed?
A trust-based mutual fund has different parties with different responsibilities. This separation helps create checks and balances around the management and custody of the scheme’s assets.
- Sponsor - The sponsor establishes the mutual fund and meets the applicable regulatory requirements.
- Trustees - Trustees oversee the mutual fund and protect the interests of unitholders. They monitor the functioning of the AMC and the scheme.
- Asset Management Company - The AMC manages the scheme’s investments according to its investment objective and applicable regulations. A fund manager makes portfolio decisions within the scheme’s mandate.
- Custodian - The custodian holds the securities and other assets of the mutual fund schemes in its custody, subject to the applicable framework.
SEBI’s mutual fund regulations establish this trust-based structure and specify the roles of trustees, AMCs, and custodians.
Where can a unit trust invest?
The underlying portfolio depends on the scheme’s objective. A mutual fund can invest in different securities and asset classes, including equity, debt, and money market instruments.
For example, an equity-oriented scheme may invest primarily in shares, while a debt scheme may invest in bonds and money market instruments. A hybrid scheme can combine permitted asset classes.
You can explore types of investment, investment products, and investment trusts to understand related structures.
How do investors earn returns from a unit trust?
Your investment can generate returns mainly through an increase in the value of the underlying assets and, where applicable, income distributed by the scheme.
Capital appreciation
If the value of the securities held by the scheme rises, the NAV can increase. If you redeem your units at a higher applicable NAV than your purchase value, you may realise a capital gain, subject to applicable costs and taxes.
Income distribution
A scheme may distribute income to investors where permitted under its structure and applicable regulations. A distribution should not be treated as an additional return guaranteed by the fund.
Returns are not assured, and the value of your investment can fall. You can read about investment risk, risk tolerance, and investment funds.
What are the benefits of a unit trust structure?
A trust-based mutual fund structure can offer several practical benefits for investors.
- Diversification - Your money can be spread across multiple securities rather than being concentrated in one investment.
- Professional management - The AMC manages the portfolio, so you do not have to select and monitor every underlying security yourself.
- Unit-based ownership - You hold units representing your interest in the scheme, making it easier to track your investment through the applicable NAV.
Access to different strategies - Different schemes can provide exposure to equity, debt, hybrid, passive, and other investment approaches.
You can also explore investment strategies and SIP investment.
What are the risks and limitations of a unit trust?
A trust structure does not remove investment risk. The risks you face depend largely on the underlying scheme and its investments.
- Market risk - The value of equity, debt, and other securities can rise or fall, affecting the NAV and your investment value.
- Limited control - The AMC and fund manager make portfolio decisions within the scheme’s mandate. You do not directly choose each security.
- Costs - Mutual funds can have expenses such as the Total Expense Ratio (TER), and some schemes may have an exit load. These costs can affect your net returns.
- No guaranteed returns - Diversification and professional management can help manage certain risks, but neither guarantees profits or protects your principal.
For related information, see good returns on investments, investment risk, and investment products.
How are unit trusts different from investment trusts?
A unit trust and an investment trust are different investment structures. The distinction should not be reduced simply to the claim that one is always more stable or flexible than the other.
A unit trust is generally structured around units representing investors’ interests in the underlying pool. An investment trust can have a company structure, with investors holding shares in that company.
The way units or shares are issued, valued, bought, and sold depends on the specific structure and jurisdiction. For Indian investors, check the legal and regulatory structure of the particular product rather than applying overseas definitions.
Read more about investment trusts.
What is the history of unit trusts in India?
India’s mutual fund history began with the establishment of the Unit Trust of India (UTI) in 1963. UTI was created under an Act of Parliament and became the first mutual fund institution in India. Its first scheme, Unit Scheme 1964, followed in 1964.
The Indian mutual fund industry later expanded to include funds sponsored by banks, financial institutions, and private-sector entities, with SEBI developing and regulating the mutual fund framework.
This history is useful because Unit Trust of India is a specific Indian institution and should not be confused with the generic term “unit trust”.
How can you invest in a unit trust or mutual fund?
If you are investing in India, the practical process is generally to select a suitable mutual fund scheme, complete KYC, choose your investment mode, and place your investment through an appropriate platform or fund house.
You can choose between an SIP and lumpsum depending on your cash flow and investment plan. If you are new to investing, first understand the scheme’s objective, Riskometer, portfolio, costs, and investment horizon.
You can also explore one-time investment plans before deciding how to deploy a lumpsum amount.
What should you check before investing?
Before investing, assess the scheme rather than relying only on the term “unit trust”. These factors can help you understand whether the investment matches your circumstances.
- Investment objective: Check what the scheme is designed to achieve and where it can invest.
- Risk level: Review the SEBI Riskometer and the underlying portfolio.
- Costs: Check the TER, exit load, and other applicable charges.
- Investment horizon: Match the scheme with the time available for your financial goal.
- Past performance: Use historical returns as context, not as a promise of future performance.
- Portfolio: Check the securities, sectors, asset allocation, and concentration.
For broader context, see investment objectives, types of investment, and investment management.
Conclusion
A unit trust is a trust-based investment structure in which investors hold units representing their interest in a pooled portfolio. In India, mutual funds use a trust structure with trustees, an AMC, and a custodian.
For you as an investor, the important point is to look beyond the label. Check the underlying investments, risk, costs, investment objective, and time horizon before investing.
Last reviewed: September 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Articles and Insights

Frequently Asked Questions
Understanding unit trusts
Unit trust investment decisions
Is a unit trust the same as a mutual fund in India?
The terms can overlap, but they should not be treated as universally interchangeable. In India, mutual funds are constituted as trusts, and investors hold units in schemes. “Unit Trust” can also refer to a specific institution, such as Unit Trust of India, or to structures used in other countries. Always check the legal and regulatory structure of the particular investment.
What is the difference between a unit and a mutual fund?
A mutual fund is the pooled investment vehicle, while a unit represents your proportionate interest in a particular scheme. For example, when you invest Rs. 10,000 in a mutual fund scheme, the number of units you receive depends on the applicable NAV. The units allow you to track your share of the scheme’s value.
Are unit trusts risky?
Yes, they can carry investment risk. The level depends on what the underlying scheme invests in. An equity-oriented scheme can be more volatile than a debt-oriented scheme, while a diversified portfolio can spread exposure across securities. Check the scheme’s Riskometer, investment objective, portfolio, and time horizon before investing.
Can I invest in a unit trust through an SIP?
If the particular mutual fund scheme offers SIPs, you can invest a fixed amount at regular intervals rather than investing a larger amount at once. An SIP can help you invest systematically, but it does not guarantee returns or eliminate market risk. Check the scheme’s minimum investment and SIP terms before starting.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.