








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
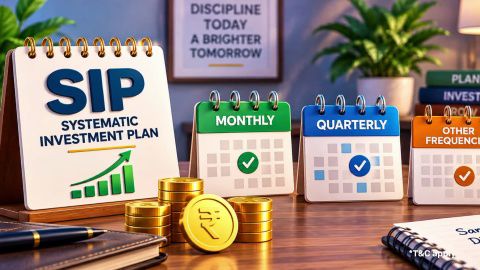
SIP Investing - How to Start, Manage & Optimise Your SIP
In summary
Surplus funds are resources remaining after accounting for financial obligations and necessary reserves. A simplified calculation subtracts total liabilities and necessary reserves from total assets, although the result may not represent immediately available cash.
- Surplus funds remain after accounting for liabilities and reserves.
- Investible surplus depends on available cash and future commitments.
- Deposits, money market instruments, and mutual funds offer investment options.
- Liquidity, investment duration, and risk determine suitable investment choices.
Understanding what a surplus fund is helps individuals and businesses allocate resources without affecting essential financial commitments.
What are surplus funds?
Surplus funds are financial resources remaining after accounting for expenses, liabilities, and necessary reserves. They can be used for investments, debt repayment, business expansion, or future financial requirements. For individuals, surplus funds generally represent money remaining after covering household expenses, loan repayments, and essential savings. Businesses may generate surplus through operating cash flows, asset sales, or accumulated earnings. However, an accounting surplus does not always represent immediately available cash. Assets such as inventory, receivables, and property may require time to convert into money.
For example, an individual earning Rs. 80,000 monthly and spending Rs. 60,000 has a potential surplus of Rs. 20,000. The actual investible amount depends on upcoming commitments and emergency savings requirements. Surplus funds can also arise in government budgeting when receipts exceed expenditure under the relevant budgetary measure.
What are the key elements of surplus funds?
The key elements used to assess surplus funds include cash and cash equivalents, other recognised assets, liabilities, and necessary reserves. Understanding these components helps individuals and businesses identify resources available after meeting financial obligations.
Cash and cash equivalents
Cash and cash equivalents include physical cash, bank balances available on demand, and qualifying short-term, highly liquid investments.
These resources help individuals and businesses meet immediate financial obligations and manage unexpected expenses. Cash equivalents can be readily converted into known amounts of cash with insignificant risk of changes in value.
Other recognised assets
Other recognised assets include accounts receivable, inventory, and marketable securities. These assets contribute to an organisation's financial position but may not be immediately available as cash.
For example, receivables depend on customer payments, while inventory must be sold before generating cash. Understanding their liquidity helps businesses assess how much money may become available for future use.
Liabilities
Liabilities are financial obligations that individuals or organisations must settle. These include outstanding loans, supplier payments, taxes payable, and other debts.
Accounting for liabilities helps determine how much surplus remains after meeting financial commitments. Repaying high-interest debt may also reduce borrowing costs and improve financial stability.
Necessary reserves
Necessary reserves are resources allocated towards future commitments, contingencies, or unexpected expenses.
Businesses may set aside cash for maintenance, operational expenses, and financial emergencies. Individuals may maintain emergency savings for medical expenses, income loss, or other unforeseen requirements.
Accounting reserves do not always represent cash held separately. Therefore, actual cash availability and existing obligations must be reviewed before determining the investible surplus.
Understanding assets and liabilities can help explain how these components affect financial planning.
How are surplus funds calculated?
Surplus funds are calculated by subtracting total liabilities and necessary reserves from total assets. This simplified calculation assumes that reserves are separate from liabilities and have not already been deducted.
Surplus funds formula:
Surplus Funds = Total Assets - (Total Liabilities + Necessary Reserves)
Follow these four steps to calculate surplus funds:
- Identify total assets: Add cash, bank balances, investments, and other recognised assets.
- Determine total liabilities: Calculate loans, payables, and other financial obligations.
- Estimate necessary reserves: Identify resources required for future commitments.
- Calculate the surplus: Subtract liabilities and reserves from total assets.
Illustrative example:
| Particulars | Amount |
|---|---|
| Total Assets | Rs. 10 crore |
| Total Liabilities | Rs. 4 crore |
| Necessary Reserves | Rs. 1 crore |
| Surplus Funds | Rs. 5 crore |
Calculation: Rs. 10 crore - (Rs. 4 crore + Rs. 1 crore) = Rs. 5 crore
The calculated surplus does not necessarily represent investible cash because some assets may be illiquid.
How can surplus funds be used?
Surplus funds can support debt repayment, emergency savings, investments, and business development. Their use depends on existing financial commitments, expected expenses, and long-term objectives.
Common uses include:
- Debt repayment: Reduce outstanding borrowings and future interest expenses.
- Emergency savings: Maintain accessible resources for unexpected financial requirements.
- Investments: Allocate available money towards short-term or long-term goals.
- Business expansion: Finance equipment purchases, operational improvements, or planned growth.
- Future expenses: Reserve money for taxes, education, retirement, and other commitments.
Businesses may also retain surplus funds to manage periods of lower revenue or unexpected operational costs. For individuals, identifying the purpose of surplus money helps determine whether it should remain accessible or be invested.
Where can surplus funds be invested?
Surplus funds can be invested in bank deposits, government securities, money market instruments, and mutual funds. The choice depends on investment duration, liquidity requirements, and risk tolerance. The following table compares common investment options:
| Investment option | Main characteristics | Key consideration |
| Savings accounts | Interest-bearing deposits with access to funds | Interest rates and withdrawal conditions |
| Fixed deposits | Contractual interest for a selected tenure | Premature withdrawal terms and issuer risk |
| Treasury bills | Short-term government securities | Market price fluctuations before maturity |
| Liquid mutual funds | Invest in short-term debt and money market instruments | Credit, interest-rate, and liquidity risks |
| Equity mutual funds | Invest primarily in equity shares | Market volatility and potential capital loss |
| Index mutual funds | Track a specified market index | Market risk, expenses, and tracking difference |
Mutual fund returns depend on the underlying investments and market conditions. Their value can rise or fall, and capital protection is not guaranteed.
What should you consider before investing?
Before investing surplus funds, evaluate liquidity needs, investment duration, financial risks, taxation, and existing commitments. These factors help determine whether money should remain accessible or be allocated towards investments.
Investment horizon
The investment horizon is the period for which you plan to keep money invested.
Money required for immediate expenses should remain readily accessible. Funds allocated towards longer-term goals may be considered for market-linked investments, depending on risk tolerance.
Withdrawing investments earlier than planned may result in losses or additional costs.
Risk and diversification
Different investments carry different levels and types of risk. For example, equity investments experience market fluctuations, while debt instruments can carry interest-rate and credit risks.
SEBI requires mutual fund schemes to disclose their risk through the Riskometer, which has six categories: Low, Low to Moderate, Moderate, Moderately High, High, and Very High.
Diversifying investments across suitable asset classes can reduce concentration risk. However, diversification does not eliminate potential losses.
Tax implications
Tax treatment depends on the investment instrument, the investor's tax status, and applicable income-tax provisions.
Interest from fixed deposits is generally taxable. Profits realised from mutual fund investments may attract capital gains tax based on the scheme's classification, acquisition date, and applicable rules.
Certain debt-oriented mutual funds are subject to specific capital gains provisions under Section 50AA of the Income-tax Act.
Investors should also review expense ratios, exit loads, and other applicable investment costs.
Existing financial commitments
Outstanding loans, emergency savings, and planned expenses should be assessed before investing.
For example, repaying an expensive loan may provide greater financial benefit than investing surplus money in a market-linked product with uncertain returns.
Businesses should similarly account for payroll, supplier payments, taxes, and working capital requirements.
How should surplus funds be managed?
Effective surplus fund management involves identifying available resources, maintaining necessary reserves, and choosing suitable investments based on financial goals.
The following steps can help:
- Review available cash: Determine money remaining after essential expenses.
- Maintain reserves: Set aside funds for emergencies and planned commitments.
- Assess debt: Review outstanding borrowings and repayment costs.
- Define goals: Separate immediate requirements from long-term objectives.
- Select investments: Compare liquidity, risks, expenses, and tax implications.
- Review periodically: Reassess investments when financial circumstances change.
Individuals considering mutual funds can invest through an SIP or a lumpsum investment. An SIP involves investing a fixed amount periodically, while a lumpsum investment involves investing an amount at one time.
Conclusion
Surplus funds represent financial resources remaining after accounting for liabilities and necessary reserves. They can be used for debt repayment, emergency savings, business requirements, or investments. However, an accounting surplus should not automatically be treated as immediately investible cash. Reviewing liquidity, future commitments, and financial risks is essential before allocating money. Individuals and businesses can manage surplus funds by identifying financial priorities and selecting investments that match their requirements. The Bajaj Broking website provides access to mutual fund investments through SIP and lumpsum modes.
Last reviewed: 13 November 2026
Disclaimer: Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights


Frequently Asked Questions
Investment options and returns
Surplus fund management and taxation
Where can the surplus fund be invested?
Surplus funds can be invested in bank deposits, government securities, money market instruments, and mutual funds. The choice depends on your financial goals, investment horizon, liquidity requirements, and ability to tolerate potential investment losses.
What is the use of surplus funds in the money market?
Surplus funds can be allocated to money market instruments for short-term cash management and potential income generation. These include treasury bills, certificates of deposit, and commercial paper, subject to availability, eligibility, and associated investment risks.
How do businesses manage surplus funds?
Businesses manage surplus funds by reviewing cash flow requirements, maintaining operational reserves, repaying debt, and considering investments. They assess liquidity needs, expected expenses, and financial risks before allocating money towards additional business activities or securities.
Can surplus funds be taxable?
Surplus funds are not automatically taxable merely because money remains after expenses. However, income generated from investing them, including deposit interest or taxable capital gains, may attract tax under applicable Indian income-tax provisions.
How can surplus funds generate additional income?
Surplus funds can generate additional income through interest-bearing deposits, debt securities, or market-linked investments. The income earned depends on the investment selected, prevailing conditions, associated costs, and risks. Returns are not guaranteed across all investment options.
How should individuals manage surplus funds?
Individuals should first review essential expenses, outstanding debt, and emergency savings before investing surplus funds. They can then allocate money according to financial goals, investment duration, and risk tolerance, while periodically reviewing their financial circumstances.
Disclaimer
Bajaj Finance Limited ("BFL"), a non-banking financial company registered with the Reserve Bank of India, is registered with the Association of Mutual Funds in India ("AMFI") as a Mutual Fund Distributor under ARN 90319 and distributing the mutual fund as a sub-distributor of Bajaj Financial Securities Limited (BFSL) registered under ARN-163403. BFL does not independently solicit, source, procure, accept or book any new mutual fund business under its own ARN. Any activities undertaken by BFL in relation to mutual fund products shall be limited to the extent permissible under applicable law and the operating arrangement approved for such products. BFL does not act as an investment adviser or research analyst.
BFL does not:
(i) provide investment advisory services in any manner or form;
(ii) undertake any customised or personalised suitability assessment;
(iii) conduct independent research or analysis in relation to any mutual fund scheme or other investment; or
(iv) provide any assurance or guarantee regarding returns, capital protection or performance. Participation in mutual fund products is entirely voluntary.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice.
Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates.
The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund.
BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Riskometer: The Riskometer is only one indicator of the risk associated with a mutual fund scheme. Before investing, investors should evaluate the scheme with reference to the applicable product labelling and Riskometer as well as other quantitative and qualitative factors, including performance, portfolio composition, fund manager and asset manager. Investors who are uncertain about the suitability of a scheme should consult their professional advisers before investing.
Disclosure: BFL holds AMFI Registration Number 90319. BFL does not independently solicit or book new mutual fund business under its own ARN. Accordingly, references on this platform to mutual fund schemes of Bajaj Finserv Asset Management Limited ("BFSAMC"), a group company of BFL, or of any other Asset Management Company shall not be construed as solicitation, sourcing, procurement, acceptance or booking of new mutual fund business by BFL under ARN 90319. BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.