








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
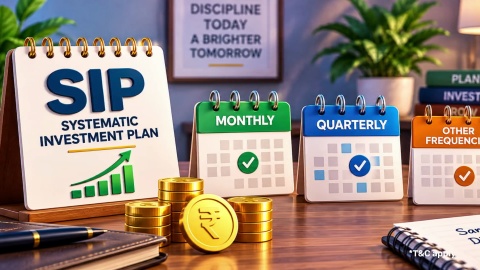
SIP Investing - How to Start, Manage & Optimise Your SIP
In summary
An SIP in an index fund lets you invest a fixed amount at regular intervals in a fund that tracks a market index. Index funds use a passive investment strategy, while the SIP determines how and when you invest.
- An SIP can spread your purchases across different NAV levels, but it cannot prevent investment losses.
- Index funds can provide diversification, but your risk depends on the index being tracked.
- Tracking error measures how closely the fund follows its benchmark.
- For equity-oriented index funds, applicable capital gains tax depends on the holding period and tax rules.
Before starting, check the underlying index, expense ratio, tracking error, Riskometer, tax treatment, and your investment horizon.
What is an SIP in an index fund?
An SIP in an index fund is a method of investing a fixed amount at regular intervals in an index mutual fund. The index fund aims to replicate the performance of a specified market index through a passive investment strategy.
The Securities and Exchange Board of India (SEBI) explains that index mutual funds aim to replicate a specific index, such as the Nifty 50, by holding all or most of its securities in similar proportions. Source: SEBI Investor, Index Mutual Funds.
You can invest in index funds through an SIP or lumpsum, subject to the scheme's terms. An index fund is also a type of passive mutual fund.
How does an SIP in an index fund work?
With an SIP, you invest a predetermined amount at a chosen frequency. Each instalment buys units of the index fund at the applicable NAV.
For example, suppose Meera invests Rs. 2,000 every month. If the NAV is Rs. 20, she buys 100 units. If the NAV falls to Rs. 10 the following month, the same Rs. 2,000 buys 200 units.
This is called rupee-cost averaging. It means the same investment amount buys more units when the NAV is lower and fewer when it is higher. AMFI states that rupee-cost averaging does not assure a profit or protect against losses in declining markets.
You can read more about SIP investment, lumpsum investment, and NAV.
What are the benefits of an SIP in index funds?
An SIP combines regular investing with the passive approach used by index funds. The main benefits are diversification, regular investing, and limited dependence on active security selection.
The following benefits are relevant when assessing an index fund SIP.
- Regular investing: You invest a fixed amount at predetermined intervals instead of deciding when to invest each time.
- Diversification: A broad index can give you exposure to several securities through one fund.
- Passive management: The fund aims to track its benchmark instead of trying to select securities to outperform it.
- Cost considerations: Passive funds generally involve less active research and trading than actively managed funds. SEBI notes that this passive structure can reduce management costs.
- Rupee-cost averaging: Your instalments buy different numbers of units as NAVs change.
Diversification depends on the index. A broad-market index can contain many securities, while a sector-specific index can be concentrated.
What risks should you consider?
An SIP does not remove the market risk of an index fund. If the underlying index falls, the value of your investment can also fall.
The main risks to consider are:
- Market risk: The index and your fund's NAV can decline.
- Tracking error: The fund's return can differ from the benchmark because of expenses, cash holdings, portfolio changes, and other factors.
- Concentration risk: A narrow index can have substantial exposure to one sector, theme, or group of securities.
- Timing risk: Regular investing does not guarantee that you will make a profit.
- Cost risk: Expenses reduce the return that reaches you.
SEBI describes tracking error as the difference between a portfolio's returns and those of its benchmark.
How should you choose an index fund for your SIP?
Start by understanding the index rather than looking only at past returns. The index determines the securities and market exposure you are buying.
Check the following factors before selecting a scheme.
| Factor | What to check |
|---|---|
| Underlying index | Companies, sectors, or securities included in the index |
| Tracking error | How closely the fund has followed its benchmark |
| Expense ratio | The fund's annual operating cost |
| Fund size | Assets managed by the scheme and its operating history |
| Riskometer | The scheme's current risk level |
| Investment horizon | Whether the fund suits your financial goal and ability to remain invested |
You can compare mutual funds before selecting a scheme.
How can you start an SIP in an index fund?
You can start by choosing an index fund, completing the required KYC process, selecting SIP as your investment method, and setting up the payment mandate. The exact minimum amount, frequency, and process depend on the scheme and platform.
Follow these steps:
- Identify the index you want to track and choose a fund that follows it.
- Check the fund's objective, portfolio, Riskometer, expense ratio, and tracking error.
- Complete KYC if you are not already KYC-compliant.
- Select SIP, enter the instalment amount and frequency, and set up the payment mandate.
- Review the details before confirming the investment.
If the relevant mutual fund is available through the Bajaj Broking website, you can review the available scheme information before investing.
You can use an SIP calculator to illustrate different investment amounts and periods. Calculator results are illustrations, not guaranteed returns.
How is an index fund SIP taxed?
Tax depends on the type of index fund and the assets it holds. For an equity-oriented index fund covered by Section 111A or Section 112A, the applicable capital gains rules depend on the holding period and other statutory conditions.
For transfers on or after 23 July 2024, short-term capital gains covered by Section 111A are taxed at 20%. Long-term capital gains covered by Section 112A are taxed at 12.5% on gains exceeding the aggregate Rs. 1.25 lakh exemption threshold for the financial year, subject to the applicable conditions. The Income Tax Department confirms these rates and the removal of indexation for these gains. Source: Income Tax Department, Tax on Sale of Shares in India, updated for the post-23 July 2024 regime.
Do not assume that every index fund receives equity-oriented tax treatment. Check the scheme's underlying assets and the tax rules applicable when you redeem.
Should you start an SIP in an index fund?
An SIP in an index fund can suit you if you want regular exposure to a particular market index and understand that its value can rise or fall with that index.
For example, Meera invests Rs. 2,000 every month because she wants a regular investment routine and does not want to select individual shares. Before starting, she checks the index, tracking error, expense ratio, Riskometer, and tax treatment.
Her SIP does not guarantee a profit. If the index falls, her investment can lose value. The SIP simply spreads her purchases across different dates and NAV levels.
Key Considerations
- Time horizon: For optimal results, it's advisable to maintain a long-term investment horizon of at least five years to mitigate short-term market volatility and harness the power of compounding.
- Tax implications:
- Short-term capital gains tax: If units are sold within one year, a 20% tax rate applies.
- Long-term capital gains tax: For holdings exceeding one year, a 12.5% tax rate applies on gains exceeding Rs. 1.25 lakh.
- Indexation benefits: Unlike other investments, index funds do not offer indexation benefits.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Understanding SIPs in index funds
Understanding returns and risk
Can I do an SIP in an index fund?
Yes, you can invest in an index fund through an SIP if the scheme offers the facility. You choose the instalment amount and frequency, and each instalment purchases units at the applicable NAV. The SIP method does not change the underlying market risk of the index fund. Check the scheme documents for its minimum SIP amount, available frequencies, and other conditions.
What is the minimum SIP amount for an index fund?
The minimum SIP amount varies between schemes, so there is no single amount for every index fund. Check the specific scheme's terms before investing. A low minimum amount does not make a fund suitable automatically. You should also consider the underlying index, tracking error, expense ratio, Riskometer, and whether the instalment fits your financial goal.
Does an SIP protect me from market losses?
No. An SIP does not protect you from market losses or guarantee returns. It spreads purchases across different dates, so the number of units you buy can vary as the NAV changes. However, if the underlying index declines, your investment can still lose value. AMFI states that rupee-cost averaging does not assure profit or protect against losses in declining markets.
Is an index fund safer than an actively managed fund?
An index fund is not risk-free or automatically safer than an actively managed fund. It carries the risks of the index it tracks. Its passive structure limits active stock selection, while an actively managed fund gives its fund manager greater discretion over security selection. Neither approach guarantees better returns or protects you from market declines.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.