








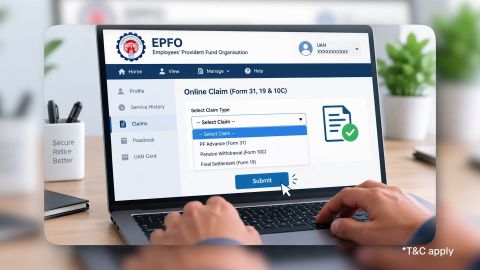
PF Withdrawal - How to Withdraw PF Online & Offline
-
In summary
EPF members may claim a partial withdrawal or final settlement when they meet the conditions under the Employees’ Provident Funds Scheme, 2026. Online claims require verified member and bank details.
- Partial claims require eligible withdrawal reasons.
- Most partial claims need 12-month membership.
- Members retain 25% of eligible savings.
- Unemployment permits an immediate 75% withdrawal.
- Online claims need verified Aadhaar details.
Tax may apply before five years.
Use the official EPFO portal and select the correct claim type. A transfer may be more suitable than a final withdrawal when you join another EPF-covered employer.
What is EPF withdrawal?
Avoid these mistakes while booking FD
-
EPF withdrawal means taking money from your Employees’ Provident Fund account under the conditions administered by the Employees’ Provident Fund Organisation. The account includes eligible employee and employer contributions with applicable interest.
There are two main types:
Withdrawal type Meaning Partial withdrawal Part of the eligible balance is withdrawn for a permitted purpose Final settlement The eligible EPF balance is paid when final-withdrawal conditions are met EPF and Employees’ Pension Scheme benefits are separate. A PF withdrawal does not automatically mean that an EPS withdrawal benefit is also available. EPF is intended primarily for retirement. If money has already been withdrawn for a valid reason and some amount remains genuinely surplus, compare fixed-income products using tenure, liquidity and issuer risk—not only the advertised rate. Bajaj Finance FDs currently offer up to 7.75% p.a. for customers below 60 and up to 8.15% p.a. for eligible senior citizens. Check the current Bajaj Finance FD interest rates.
When can you withdraw your EPF balance?
-
You can withdraw EPF partially for permitted needs or claim final settlement when a qualifying condition is met. The available amount depends on the claim category, membership period and balance-retention requirement.
When is partial withdrawal permitted?
The 2026 framework places partial withdrawals into three broad categories:
Category Examples General membership condition Essential needs Illness, education and marriage 12 months Housing needs Purchase, construction, loan repayment or renovation 12 months Special circumstances Circumstances covered by the scheme 12 months Education withdrawals may be permitted up to ten times during membership. Marriage withdrawals may be permitted up to five times. Housing withdrawals are also subject to the prescribed frequency and claim conditions.
The amount approved can be lower than the amount requested if the balance, purpose or scheme limits do not support the full claim.
What is the minimum balance requirement?
A member must generally retain 25% of the aggregate employee contribution, employer contribution and applicable interest after a partial withdrawal.
For example, suppose the relevant aggregate PF balance is Rs.2 lakh:
Calculation Illustrative amount Aggregate balance Rs.2,00,000 Minimum 25% retained Rs.50,000 Maximum above the reserve Rs.1,50,000 This does not guarantee a Rs.1.50 lakh payment. EPFO calculates the admissible amount using the relevant balance, claim category, frequency restriction and other scheme conditions.
When can you withdraw the full EPF balance?
Full withdrawal may be permitted in specified situations, including:
- Retirement after attaining 55 years of age
- Permanent and total incapacity for work
- Retrenchment under qualifying conditions
- Eligible voluntary retirement
- Permanent migration from India
- Taking employment abroad
- Completion of the prescribed unemployment period
- Other circumstances covered by the scheme
The standard route after leaving covered employment generally requires one year without employment in an establishment covered by EPF. Separate exceptions apply to qualifying retirement, incapacity and other specified cases.
What happens if you become unemployed?
A member who becomes unemployed may withdraw up to 75% of the PF balance immediately. This includes the eligible employee contribution, employer contribution and interest. The remaining 25% may be withdrawn after completing one year of unemployment. If you obtain another EPF-covered job, transferring the balance may preserve service continuity and support future pension eligibility.
Understanding the PF claim process
A PF claim begins by identifying whether you need a partial withdrawal, final EPF settlement or an EPS-related benefit. Online applications use your UAN-linked member record, while offline claims use the applicable Composite Claim Form.
Before applying, check your membership period, employment status, date of exit, Aadhaar details and bank account. The claim type must match your actual circumstances. Incorrect bank details, missing service information or an ineligible claim category can cause rejection. Keep the acknowledgement number after submission and track the request through EPFO’s official claim-status facility.
What are the eligibility criteria for EPF withdrawal?
Eligibility depends on the withdrawal type. Partial claims generally require at least 12 months’ total EPF membership under the 2026 framework. Final settlement requires a qualifying event, such as eligible retirement, prolonged unemployment, permanent incapacity or permanent migration abroad.
| Eligibility check | What to confirm |
| EPF membership | Your account and service records are available |
| UAN | UAN is activated and usable |
| Aadhaar | Aadhaar is linked and verified |
| Bank account | Account number and IFSC are correct |
| Employment record | Joining and exit details are updated |
| Claim conditions | Membership or waiting period is completed |
Documents you need for a PF Online Claim
Keep these details ready:
- Active UAN and login password
- Aadhaar linked with your EPF record
- Access to the Aadhaar-linked mobile number
- Verified bank account number and IFSC
- PAN for applicable taxable claims
- Correct joining and exit dates
- Claim reason and requested amount
| Common record or document | When it may be needed |
| UAN | Online and offline identification |
| Aadhaar | Identity and online authentication |
| Bank details | Direct claim payment |
| PAN | Particularly relevant for taxable final claims |
| Cancelled cheque | If required by the claim process |
| Composite Claim Form | Applicable offline claims |
| Supporting certification | Only where specifically required |
UAN activation for existing and new UANs now takes place through Aadhaar-based face authentication on the UMANG app. Once activated, members can use their credentials to access eligible services on the Member e-Sewa portal.
How to withdraw EPF online?
Eligible members can apply through the official EPFO Member e-Sewa portal. The claim options displayed depend on the member’s service records and eligibility.
Step 1: Log in to the EPFO member portal
Enter your UAN, password and security code on the official Member e-Sewa portal. Do not use a claim link received from an unknown caller, message or social media account.
Step 2: Check your profile and KYC details
Confirm that your:
- Name matches your Aadhaar
- Aadhaar is verified
- Bank account and IFSC are correct
- PAN is available where relevant
- Joining and exit dates are updated
Mobile number can receive authentication messages
Correct any mismatch before submitting the claim.
Step 3: Open the claim service
Select the claim option under the online-services menu. Follow the labels shown on the live portal, as EPFO may update menu names or workflows.
Step 4: Verify your bank details
Enter or confirm the bank account details requested by the portal. The account should be active and held in the member’s name.
Incorrect bank details can cause rejection or payment failure.
Step 5: Select the applicable claim type
Choose the option matching your requirement:
| Claim option | Purpose |
| Final PF settlement | Withdrawal of eligible EPF balance |
| PF advance | Permitted partial withdrawal |
| EPS withdrawal benefit | Eligible pension-scheme withdrawal benefit |
| Scheme certificate | Preservation of eligible EPS service |
EPF and EPS claims have different rules. Do not select an EPS withdrawal merely because you are also settling EPF.
Step 6: Complete the claim details
Select the genuine withdrawal reason and enter the requested amount where required. Check any declaration displayed by the portal.
The requested amount cannot exceed the amount admissible under the applicable rules.
Step 7: Complete authentication and submit
Review the details and complete Aadhaar OTP or the authentication method requested by EPFO.
Never disclose your password or OTP. EPFO states that it does not call members asking for Aadhaar, PAN, bank details, passwords or payments.
Step 8: Track the claim status
Save the claim reference number. Track progress through EPFO’s claim-status service or the EPF passbook and claim-status facility.
If the claim is rejected, first read the rejection reason. Correct the relevant record before submitting another claim.
Check out different FD Rates
How to withdraw EPF offline?
An offline claim may be used when a member cannot complete the digital process or EPFO requires a physical application. Confirm the currently accepted form with the relevant EPFO office before submission.
Step 1: Identify the correct claim form
Select the form matching the benefit being claimed. The Composite Claim Form may cover final PF settlement, a PF advance and eligible pension withdrawal benefits.
Step 2: Complete the form accurately
Enter your:
- Name and UAN
- Aadhaar or identity details
- Employment information
- Joining and exit dates
- Bank account details
- Claim category and amount
- Postal and contact details
The information should match EPFO’s records.
Step 3: Check attestation and supporting requirements
The Aadhaar-based Composite Claim Form may be submitted without employer attestation when the required UAN, Aadhaar, Form 11 and bank details are available and verified.
The non-Aadhaar process may require employer attestation and additional verification. A cancelled cheque or bank record may also be requested.
Step 4: Submit through the prescribed channel
Submit the completed form to the appropriate EPFO office or designated channel. Retain a copy and obtain an acknowledgement.
Which forms are used for EPF withdrawal?
| Form or claim | Main purpose |
| Form 19 | Final EPF settlement |
| Form 31 | Eligible partial withdrawal or PF advance |
| Form 10C | EPS withdrawal benefit or scheme certificate |
| Composite Claim Form | Combined offline claim route |
| Form 10D | Monthly EPS pension application |
The current online process may present claim names instead of requiring a separate paper form.
Please note: Form 121 is not a prescribed EPF withdrawal form. It should not be confused with Form 19, Form 31, Form 10C or the Composite Claim Form.
What are the tax implications of EPF withdrawal?
EPF final-settlement tax treatment depends on continuous service, the reason employment ended and whether earlier EPF balances were transferred.
| Situation | General treatment |
| Five years or more of continuous service | Withdrawal is generally exempt |
| PF transferred between eligible employers | Earlier service may count |
| Less than five years’ service | Withdrawal may be taxable |
| Termination beyond employee’s control | Exemption may apply |
| Taxable payment above Rs.50,000 | TDS may apply |
| Applicable TDS rate | 10% |
From 1 April 2026, section 392(7) of the Income-tax Act, 2025 covers TDS on a taxable accumulated provident fund balance. TDS is not necessarily the member’s final tax liability. Partial withdrawals made within the scheme conditions may have different tax treatment from an early final settlement. Obtain professional advice where service history, transfers or termination circumstances are complicated.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
How long does an EPF withdrawal take?
Processing time depends on the claim type and whether EPFO’s validations are completed successfully.
| Claim category | Published service position |
| Eligible auto-settled advance up to Rs.5 lakh | Normally within three days |
| Final PF settlement | Citizens’ Charter target: seven working days |
| Other part withdrawals | Citizens’ Charter target: seven working days |
| Statutory scheme timeline | Up to 20 days for listed claims |
The Citizens’ Charter timelines are service targets, not guaranteed payment dates. Incorrect KYC, bank details or employment records may delay settlement.
Should you withdraw or transfer your PF after changing jobs?
Transfer is generally more suitable when you join another EPF-covered employer and do not need an eligible withdrawal.
| Consideration | Transfer | Withdrawal |
| Retirement corpus | Preserved | Reduced |
| Service continuity | Generally retained | May be interrupted |
| Five-year tax test | Earlier transferred service may count | Early settlement may be taxable |
| EPS eligibility | Service may continue | Withdrawal may affect pension rights |
| Immediate cash | Not received | Paid if eligible |
Do not withdraw EPF solely to place the proceeds in another fixed-income product. If a withdrawal is independently necessary and money later remains surplus, compare liquidity, credit risk and post-tax returns. Bajaj Finance FDs have CRISIL AAA/STABLE and [ICRA]AAA(Stable) ratings, but credit ratings may change and do not guarantee repayment. Review the Bajaj Finance Fixed Deposit terms before investing.
To summarise
EPF may be withdrawn online through the Member e-Sewa portal or offline through the applicable claim form. Before applying, identify whether you need a partial withdrawal, final settlement or EPS benefit. Check your UAN, Aadhaar, bank and service details, and retain the required 25% balance for partial claims. After changing jobs, transferring EPF may better preserve tax and pension continuity. Always follow the current EPFO portal and scheme provisions rather than older withdrawal guides.
Explore popular investment calculators such as Fixed Deposit and Provident Fund Calculators.
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
Can I withdraw my PF online without visiting an EPFO office?
Eligible members can submit claims through the official EPFO Member e-Sewa portal after completing the required verification. Whether a particular claim can be completed entirely online depends on the claim type and the current portal requirements.
Is Form 121 mandatory for PF withdrawal?
No, Form 121 is not a prescribed EPF withdrawal form. Common claim forms include Form 19, Form 31, Form 10C and the Composite Claim Form, depending on the benefit requested.
How long does EPFO take to process a claim?
Eligible auto-settled advances of up to Rs.5 lakh may be processed within three days. The Citizens’ Charter lists seven-working-day targets for several other claims, while the applicable scheme timeline may extend to 20 days.
Can I apply for PF withdrawal without updated KYC?
An online claim generally cannot be completed if the required Aadhaar and bank details are missing or unverified. Update the relevant record first or confirm the applicable offline process with EPFO.
Can I apply for PF withdrawal offline?
Yes, you may submit the applicable Composite Claim Form through the prescribed EPFO channel. Aadhaar-based and non-Aadhaar forms have different verification and employer-attestation requirements.
Can I withdraw 100% of my EPF balance?
Full withdrawal is permitted only under specified circumstances. Partial withdrawals are subject to eligibility rules and a minimum balance requirement under the Scheme 2026 framework. Do not assume that you can withdraw the entire account balance for every permitted purpose.
Can I withdraw my PF if I leave my job?
Leaving employment does not automatically make the entire PF balance immediately withdrawable. The applicable waiting period, membership conditions and circumstances determine whether you can apply for partial withdrawal or final settlement. A transfer may be more appropriate if you have moved to another covered job.
Can I apply for PF withdrawal offline?
An offline process may be available for an applicable claim. Confirm the correct form, attestation requirements and submission channel through official EPFO instructions before filing a physical application.
Is EPF withdrawal taxable?
Some withdrawals may be taxable, particularly where the applicable continuous-service conditions have not been met. TDS may apply depending on the withdrawal amount and circumstances, but TDS is not the same as the final tax liability.
Can I withdraw my EPS pension contribution along with EPF?
EPS benefits are governed by separate rules. Eligibility for a withdrawal benefit or pension depends on factors such as qualifying service and age. Check the appropriate EPS claim process before applying.
What should I do if my EPF claim is rejected?
Read the rejection reason in the claim-status service, correct any missing or mismatched information and follow the official instructions for resubmission or grievance escalation. Avoid submitting duplicate claims without understanding why the earlier request failed.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.