







Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
Alternative Investment Options
In summary
Private equity (PE) is money invested in companies that do not trade on a stock exchange. In India, you invest in PE mainly through a Category II Alternative Investment Fund (AIF) registered with the Securities and Exchange Board of India (SEBI).
- The minimum investment in an AIF is Rs. 1 crore per investor.
- Employees or directors of the AIF or its manager can invest from Rs. 25 lakh.
- Category II AIFs are close-ended, with a minimum term of 3 years.
- You commit an amount, and the fund draws it from you in instalments.
You can lose part or all of the money you invest.
PE suits investors who can commit Rs. 1 crore, leave it untouched for at least 3 years and absorb a full loss without changing their lifestyle. If that does not describe you, look at the listed routes below.
Last reviewed: September 2026
What is private equity?
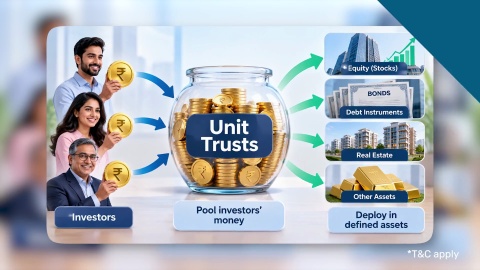
Private equity is an investment in a company whose shares do not trade on a stock exchange. A PE fund pools money from investors, buys stakes in such companies and sells those stakes later at a profit or a loss.
The fund's manager works with each company to raise its value, through expansion, new products, better processes or a change in how it borrows. The fund then exits, by selling its stake to another investor or through an initial public offering (IPO). Your return depends on the price at exit, minus fees and taxes.
How does a private equity fund work in India?
A private equity fund in India operates as an AIF. An AIF is a privately pooled investment vehicle, registered with SEBI, that collects money from investors to invest under a defined investment policy. SEBI places PE funds in Category II, which covers AIFs that do not use leverage except for day-to-day operating needs. Four terms explain how your money moves:
| Term | What it means for you |
|---|---|
| Commitment | The total amount you agree to invest, at least Rs. 1 crore |
| Drawdown | Each instalment the fund calls from your commitment when it finds a company to invest in |
| Private placement memorandum (PPM) | The fund's offer document, listing its strategy, fees, term and exit rules |
| Distribution | Money the fund returns to you after it sells a stake |
A Category II AIF is close-ended, so you cannot redeem your units before the fund's term ends. The minimum term is 3 years, and investors holding two-thirds of the fund's value can approve an extension of up to 2 years.
Source for the rules in this section: SEBI (Alternative Investment Funds) Regulations, 2012, last amended July 2026. For a wider view of the category, read alternative investment funds.
What are the main types of private equity?
The 4 main types of private equity differ by the company's stage and the way the fund puts in money. Each type carries a different level of risk.
| Type | Company stage | How the fund invests |
|---|---|---|
| Venture capital | Start-up or early stage | Buys a minority stake in exchange for capital to grow |
| Growth equity | Established and expanding | Buys a minority stake to fund expansion |
| Leveraged buyout | Mature | Buys control, using a mix of fund capital and debt raised by the company |
| Mezzanine capital | Mature | Lends money that can convert into equity |
In India, venture capital funds register as Category I AIFs, while growth, buyout and mezzanine funds register as Category II. Read more about Venture Capital Funds.
How can you invest in private equity?
You can invest in private equity directly only by committing at least Rs. 1 crore to a SEBI-registered AIF. The routes below show what each option gives you.
| Route | Minimum investment | What you own |
|---|---|---|
| Category II PE fund | Rs. 1 crore | Units in a fund that holds unlisted companies |
| Category I venture capital fund | Rs. 1 crore | Units in a fund that holds start-ups |
| AIF that invests in other AIFs (fund of funds) | Rs. 1 crore | Units in a fund that holds 2 or more PE funds |
| Listed shares or equity mutual funds | No AIF minimum | Shares of listed companies, not a stake in a PE fund |
If you have less than Rs. 1 crore, the real question is what to do instead. The only lower AIF minimum is Rs. 25 lakh, for employees or directors of the AIF or its manager. Listed shares and equity mutual funds give you exposure to company growth, but they do not give you the unlisted holdings, fees or lock-in of a PE fund.
How much money do you need to invest in private equity?
You need a commitment of at least Rs. 1 crore to invest in private equity, plus enough liquid money to meet each drawdown when the fund calls it. Work out the share of your wealth the commitment takes with the formula below.
Share of investable assets = Commitment ÷ Investable assets × 100
Example: Anil, 48, Bengaluru. Anil runs a business, earns Rs. 60 lakh a year and holds Rs. 5 crore in investable assets. He does not need this money for the next 8 years. He commits Rs. 1 crore to a Category II PE fund with a 7-year term.
His commitment is Rs. 1 crore ÷ Rs. 5 crore × 100 = 20% of his investable assets. The fund plans to draw Rs. 25 lakh a year for 4 years, so Anil keeps the undrawn Rs. 75 lakh in assets he can sell within a week. If the fund returns 30% less than he put in, he gets back Rs. 70 lakh; if it returns 30% more, he gets back Rs. 1.3 crore.
These outcomes are before fees and taxes and are illustrations, not forecasts. They assume Anil meets every drawdown and the fund exits within its 7-year term.
Two practical limits apply. The manager, not you, decides when each drawdown arrives, so keep the undrawn amount ready from day one. The fund's contribution agreement also sets the consequences of missing a drawdown, so read that clause before you sign.
What are the risks of private equity?
The main risk of private equity is that you can lose part or all of your money, with no way to exit before the fund's term ends. The table sets out each risk and what it means for you.
| Risk | What it means for you |
|---|---|
| Capital loss | A portfolio company can fail, and you can lose your entire investment in it |
| Lock-in | You cannot redeem units for at least 3 years, and the term can extend by 2 more |
| Valuation | Unlisted companies have no daily market price, so you see changes in value only at each valuation date |
| Concentration | A fund holds a small number of companies, so one failure hits your return hard |
| Manager | Your result depends on the skill and continuity of the people running the fund |
PE does not suit money you need for a goal within the fund's term, such as a child's education or a home purchase. It also does not suit you if a loss of Rs. 1 crore would change how you live. For how PE fits with other holdings, read about asset casses.
How is private equity taxed in India?
You, not the fund, pay tax on income from a Category II private equity fund. Category I and II AIFs have pass-through status for most income, so you pay tax on your share of the gains as if you held the investments directly. This is the position under Indian income tax law as of September 2026; confirm the treatment for your fund with a tax adviser before you invest.
What are the steps to invest in private equity?
To invest in private equity, you check your eligibility, choose a SEBI-registered fund, read its PPM and sign a contribution agreement. The process has 7 steps.
- Confirm you can commit Rs. 1 crore. Check that you can also keep the undrawn amount available for the fund's full term.
- Shortlist Category II PE funds. Confirm each fund's SEBI registration on the SEBI website.
- Read the PPM. Note the strategy, term, drawdown schedule, fees and exit rules.
- Complete Know Your Customer (KYC) checks. The fund or its distributor verifies your identity and address.
- Sign the contribution agreement. This document records your commitment and your obligation to meet drawdowns.
- Meet each drawdown. Transfer each instalment by the date the fund sets.
- Track distributions. Record each amount the fund returns, for your tax filing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Exits and fees
Checking a fund and its targets
Can you exit a private equity fund before its term ends?
No, you cannot redeem your units early, because Category II funds are close-ended. You can transfer your units to another eligible investor only if the PPM allows it and the buyer meets the Rs. 1 crore minimum. Before you commit, check the PPM's transfer clause and plan to hold your units for the full term, plus a possible extension of up to 2 years.
What fees does a private equity fund charge?
You pay two main fees. The manager charges a management fee each year on your committed or invested capital. Carried interest is the manager's share of profits above a set minimum return, called the hurdle rate. The fund also passes on setup and operating costs. The PPM lists each fee and how the fund calculates it, so compare these figures across funds before you commit.
How do you check that a private equity fund is registered with SEBI?
Search for the fund's name in the list of registered AIFs on the SEBI website. A Category II fund's registration number begins with IN/AIF2/, and a Category I fund's begins with IN/AIF1/. If you cannot find the fund on the list, do not invest in it. Check the manager's name as well, because the manager runs the fund day to day.
What is the Rule of 72 in private equity?
The Rule of 72 estimates how many years an investment takes to double at a fixed annual return. You divide 72 by the annual return: at an assumed 12% a year, 72 ÷ 12 = 6 years. PE returns arrive unevenly, only when the fund sells a stake, so treat the result as a rough check on a fund's target, not a forecast.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.