








Fixed Deposit Account Management Premature Withdrawal, Claims
-
In Summary
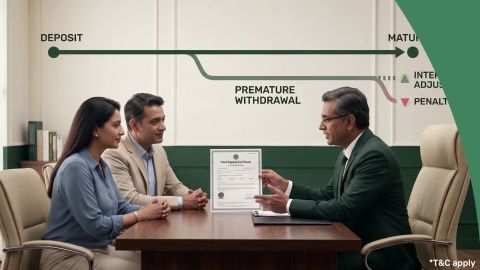
You can request premature withdrawal of an FD before its maturity date, provided the deposit provider's terms allow it. The process usually involves signing in to the provider's portal or submitting a withdrawal request through the prescribed offline channel. However, early closure may reduce the interest earned or result in no interest being payable.
For Bajaj Finance FDs, the published terms generally provide that:
- Within the first three months: Premature withdrawal is not permitted under ordinary circumstances, subject to specified exceptions.
- After three months but before six months: Withdrawal is permitted, but interest is not payable.
- After six months and before maturity: Interest is calculated at a reduced rate based on the applicable rules.
Before submitting a request, check the terms applicable to your FD, the estimated payout and any tax deductions. If you need funds urgently, compare premature withdrawal with other available options before deciding.
What does it mean to break an FD before maturity?
Avoid these mistakes while booking FD
-
Breaking an FD means withdrawing the deposit before the maturity date agreed upon when it was opened. It is also called premature closure or premature withdrawal.
For example, suppose you open an FD for 36 months but need the money after 18 months. If your deposit provider permits early closure, you can submit a request to withdraw the funds. The final amount may be lower than the maturity amount originally estimated because the interest may be recalculated under the provider's premature withdrawal rules.
The conditions differ between banks and non-banking financial companies (NBFCs). Some deposits, including tax-saving FDs, may have restrictions that prevent ordinary premature withdrawal. Therefore, check the terms of the specific deposit rather than assuming that every FD can be closed early.
How can you break a Bajaj Finance FD online?
-
You can submit a premature withdrawal request through the Bajaj Finance customer service portal. Keep your registered mobile number and FD details available before starting.
Steps to request premature withdrawal online
- Visit the official website: Open the Bajaj Finance website.
- Sign in to your account: Use the registered mobile number and complete the OTP-based verification process.
- Open the service request section: Verify your details and navigate to Raise a Request.
- Select the relevant service: Go to Service, select Relations, choose Fixed Deposit and then select Premature withdrawal.
- Review the withdrawal details: Check the displayed premature withdrawal calculation and the amount payable.
- Submit the request: Follow the on-screen instructions and complete any required OTP verification.
After submission, a representative is expected to contact you within 48 business hours to guide you through the next steps, according to the published service instructions. This is a response timeframe, not a guarantee that the money will be credited within 48 business hours.
For the latest process, refer to the official Bajaj Finance premature FD withdrawal guide.
Can you break an FD offline?
The offline process depends on the provider. If an online request is unavailable or you need assistance, contact the bank or financial institution that holds the deposit to confirm its prescribed procedure.
You may be asked to:
- Obtain and complete the premature withdrawal request form.
- Provide your FD receipt or deposit details.
- Submit identity and other supporting documents, if required.
- Complete the verification process specified by the provider.
- Confirm the bank account into which the eligible proceeds will be paid.
For a Bajaj Finance FD, check with customer support or a branch before visiting, so you can confirm the current procedure and documents required. Do not assume that the process for a bank FD applies to an NBFC deposit.
What are the premature withdrawal rules for Bajaj Finance FDs?
The published Bajaj Finance terms set out different conditions according to how long the deposit has been held. The following table summarises those terms; the applicable deposit agreement and current rules should be checked before making a request.
| When you request withdrawal | General condition under the published terms |
|---|---|
| Within the first three months | Premature withdrawal is generally not permitted, subject to specified exceptions. |
| After three months but before six months | Withdrawal is permitted, but interest is not payable. |
| After six months but before maturity | Interest is payable at a reduced rate based on the applicable completed-tenure rate and the prescribed reduction. |
Important exceptions: The published terms include provisions for certain situations, such as the death of a depositor and specified emergencies. For eligible emergency expenses during the first three months, partial premature withdrawal may be allowed up to the lower of 50% of the principal or Rs. 5 lakh, subject to the company's verification and applicable policy. Specific conditions also apply to certain critical illness cases and small deposits.
These exceptions are not a blanket entitlement to withdraw every FD early. The eligibility criteria and documentation must be confirmed with Bajaj Finance.
For the full conditions, read the official Bajaj Finance premature withdrawal terms and conditions.
How does breaking an FD affect the interest you earn?
Premature withdrawal can reduce the interest you receive because the provider may calculate interest using the rate applicable to the period for which the FD was actually held, followed by any prescribed reduction.
For Bajaj Finance FDs, the published terms specify that after six months but before maturity, interest is calculated at a rate two percentage points below the rate specified for the period during which the deposit ran. If no rate is specified for that period, the terms provide for a rate three percentage points below the company's lowest offered rate.
The actual calculation depends on the applicable terms and the deposit's details.
Illustrative example
Suppose an FD was originally booked for a longer tenure, but you request closure after completing a shorter period. The provider may use the rate applicable to that completed period rather than the rate associated with the original tenure. The prescribed reduction may then apply.
This means the interest payable can be lower than the amount shown in the original maturity illustration. The example is conceptual; use the provider's actual calculation for your deposit before deciding.
Will TDS already deducted be refunded?
Tax deducted at source (TDS) is tax withheld and deposited with the government when applicable. The published Bajaj Finance premature withdrawal terms state that tax deducted at source and remitted to the tax authority before premature withdrawal will not be refunded by the company as part of that withdrawal.
TDS is not necessarily the final tax liability. The tax treatment of FD interest and any credit available for TDS depend on the individual's circumstances and applicable tax rules. Review the relevant tax records when filing your income tax return.
What should you check before breaking an FD?
Before submitting a request, consider the following points.
- The withdrawal rules: Confirm whether premature closure is permitted for your particular FD and whether any exceptions apply.
- The amount you will receive: Review the provider's calculation, including the interest payable and any applicable deductions.
- Your original and completed tenures: The interest rate used for premature closure may differ from the rate offered for the original tenure.
- Tax implications: Check the interest already credited, any TDS deducted and the tax treatment applicable to you.
- The payment account: Confirm the bank account details recorded with the provider and follow any required verification process.
- The processing time: A submitted request may require additional verification before the payout is processed.
- The alternatives: If you need only part of the money, check whether partial withdrawal is allowed or whether another funding option is more suitable.
Reviewing these details can help you understand the likely financial impact before closing the deposit.
What are the alternatives to breaking an FD?
If you need money before maturity, premature withdrawal is not the only option in every situation. The alternatives available depend on the provider, the deposit terms and your financial circumstances.
Partial withdrawal
Some deposit products or providers may allow part of a deposit to be withdrawn while the balance remains invested. This facility is not universal. Confirm whether it applies to your FD and how the remaining deposit will earn interest.
Loan against an FD
Some banks and financial institutions offer a loan or overdraft against an eligible FD. This may allow you to access funds without closing the deposit, but interest, fees, borrowing limits and repayment obligations may apply.
Check whether your deposit qualifies and compare the borrowing cost with the interest you could lose through premature withdrawal. Do not assume that every FD provider offers this facility.
Using other available savings
If the amount needed is small and you have accessible savings, compare using those funds with closing an FD early. Consider your emergency reserve and upcoming expenses before making a decision.
No alternative is automatically preferable. The choice depends on how much money you need, how quickly you need it, the cost of borrowing and the effect on your savings.
Check out different FD Rates
In conclusion
Breaking an FD before maturity can provide access to funds, but it may reduce the interest you receive or, in some circumstances, mean that no interest is payable. The rules depend on the provider, the type of deposit and the period for which it has been held. For a Bajaj Finance FD, review the applicable premature withdrawal terms and the payout calculation before submitting a request. If you need only part of the money, check whether partial withdrawal or a loan against an eligible FD is available. Comparing these options can help you understand the financial implications before deciding.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
Can I break an FD before maturity?
It depends on the FD provider and the deposit's terms. Many regular FDs allow premature withdrawal, subject to conditions or reduced interest. Some deposits, such as tax-saving FDs, have restrictions. Check the applicable terms before requesting closure.
How do I break a Bajaj Finance FD online?
Sign in to the official Bajaj Finance service portal using your registered mobile number and complete the required verification. Navigate to Raise a Request, then Service, Relations, Fixed Deposit and Premature withdrawal. Review the calculation and submit the request by following the on-screen instructions.
What happens if I break my Bajaj Finance FD before six months?
Under the published terms, premature withdrawal is generally not permitted within the first three months, subject to specified exceptions. After three months but before six months, withdrawal is permitted without interest. Check the terms applicable to your deposit for the precise conditions.
Can I break a five-year FD before maturity?
It depends on the product. A regular FD may permit premature withdrawal under its terms, while a tax-saving FD generally has a lock-in period that restricts ordinary early withdrawal. Confirm the conditions for your particular deposit.
Can I avoid premature withdrawal penalties?
There is no universal way to avoid a premature withdrawal reduction. The rules depend on the provider and product. Check whether partial withdrawal or a loan against an eligible FD is available, and compare the costs before making a decision.
How long does premature FD withdrawal take?
Processing time varies by provider and the verification required. For Bajaj Finance, the published service guide says a representative will contact the customer within 48 business hours after the request is submitted to guide the next steps. This does not guarantee that the funds will be credited within that period.
What are the penalty charges for premature closure of FD?
After six months, the applicable rate is generally reduced by 2%. A 3% reduction applies when no corresponding rate exists.
Can the FD account be broken without any penalty?
Normal closure at maturity does not attract a premature withdrawal reduction. Approved exceptions may still provide only the principal without interest.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.