








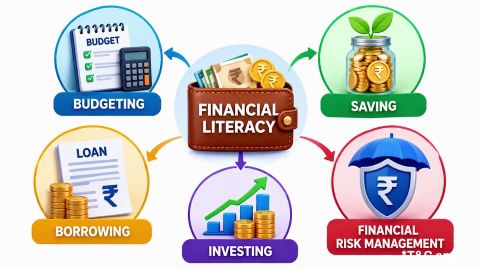
What is financial literacy
-
In summary
Financial literacy helps people make thoughtful decisions about everyday spending, borrowing, saving and investing while preparing for planned expenses and financial emergencies.
- Its importance lies in helping individuals compare costs, risks, returns and financial obligations.
- The RBI framework covers three components: financial knowledge, financial behaviour and financial attitude.
- Core financial literacy skills include budgeting, saving, managing debt, investing, using insurance and identifying fraud risks.
- Different investments carry different levels of risk, liquidity, potential return, taxation and cost.
- Bajaj Finance FDs currently start from Rs. 15,000. At-maturity rates go up to 7.75% p.a. for customers below 60 and 8.15% p.a. for senior citizens, depending on tenure and applicable terms.
If an FD matches your goal and investment period, compare the current Bajaj Finance FD rates, payout choices and withdrawal conditions before investing.
What is financial literacy?
Financial literacy means understanding how money works and applying that knowledge to financial decisions. It includes managing income, spending, savings, debt, insurance, investments and long-term goals.
The Reserve Bank of India’s financial-literacy framework covers three broad components:
| Component | What it means |
| Financial knowledge | Understanding inflation, interest, borrowing costs, diversification, risk and return |
| Financial behaviour | Budgeting, saving, investing, managing debt and planning for future needs |
| Financial attitude | Balancing present spending with future financial security and understanding personal risk preferences |
Financial literacy is therefore more than knowing financial terms. It involves using that knowledge when choosing a product, evaluating a loan or deciding how much money to save.
Also read: Smart investment options
Scope of financial literacy
The scope of financial literacy covers the knowledge and practical skills required to manage everyday finances and work towards future goals.
It commonly includes:
- Understanding savings accounts, fixed deposits, loans, insurance and investments
- Creating a budget and tracking income and expenses
- Building regular savings and an accessible emergency fund
- Understanding interest, inflation, fees, taxes and borrowing costs
- Managing credit and debt within an affordable repayment capacity
- Comparing investments by risk, liquidity, tenure, potential return and taxation
- Planning for education, housing, retirement and other major expenses
- Recognising fraud risks and knowing where to raise a complaint
Financial literacy also helps people recognise that products serving different purposes should not be compared only by their advertised returns.
Why does financial literacy matter?
How to Choose the Right Fixed Deposit for Your Financial Goals
-
Financial literacy matters because it helps people make decisions that reflect their income, responsibilities, financial goals and capacity for risk:
Security
Understanding borrowing costs, product conditions and fraud warning signs can help individuals avoid unsuitable commitments. It also encourages people to verify whether a provider or intermediary is appropriately regulated.
Goal achievement
Financial knowledge can turn a broad objective into a measurable goal. A person can estimate the required amount, set a timeline and decide how much to save or invest regularly.
Better financial confidence
Knowing your income, expenses, savings and liabilities makes financial choices easier to assess. It can also help you ask clearer questions before accepting a loan, insurance policy or investment.
Building healthy financial habits
Regular budgeting, timely repayments and planned saving can gradually improve financial discipline. Families can also introduce younger members to needs, wants, saving and responsible digital payments.
Key areas to focus on for building financial literacy
Building financial literacy requires attention to several connected areas. The following table explains what each area covers and why it matters:
| Area | What it means | Why it matters |
| Budgeting | Tracking income and expenses | Helps keep spending within available income |
| Saving | Setting aside money regularly | Supports planned expenses and emergencies |
| Debt management | Understanding interest, fees and repayment periods | Helps assess the complete borrowing cost |
| Financial products | Comparing features, eligibility and conditions | Reduces the chance of choosing an unsuitable product |
| Investing | Understanding risk, return, liquidity and tenure | Helps match investments to financial goals |
| Risk management | Using emergency savings, insurance and diversification appropriately | Helps manage different financial uncertainties |
| Fraud awareness | Verifying providers and protecting credentials | Helps identify suspicious offers and communications |
| Starting with an FD | Placing eligible surplus funds for a fixed tenure at a predetermined rate | May suit goals requiring predictable interest, subject to issuer risk and withdrawal terms |
An FD should not replace an emergency fund because premature withdrawal may be restricted or may result in lower interest.
Getting started with financial literacy
Begin by preparing a simple financial snapshot. Record your monthly income, essential expenses, discretionary spending, outstanding debt, available savings, insurance cover and major financial goals. Next, identify one or two areas that need attention. For example, you may need to reduce high-cost debt, build an emergency fund or begin saving for a defined goal. Small, consistent improvements are usually easier to maintain than attempting to change every financial habit at once.
How can you improve your financial literacy to budget, save, manage debt and invest better?
You can improve financial literacy by following a structured process and reviewing your progress regularly.
Steps to build financial literacy
- Track your spending: Record regular income and expenses. Separate essential costs from discretionary spending to understand where your money goes.
- Create a realistic budget: Allocate money for household needs, repayments, savings, insurance and investments while keeping the total within your available income.
- Set measurable financial goals: Define the required amount and target date for goals such as an emergency fund, education, a home or retirement.
- Build an emergency fund: Keep emergency money in an accessible form so that unexpected expenses do not immediately require additional borrowing.
- Understand debt before borrowing: Compare interest rates, processing fees, penalties, repayment periods and total borrowing costs instead of looking only at the monthly instalment.
- Learn before investing: Check the investment’s risk, liquidity, costs, tax treatment, return potential and time horizon. A Bajaj Finance FD calculator can estimate interest and maturity proceeds for different deposit amounts, tenures and payout choices. Calculator results are estimates and remain subject to applicable product terms.
- Review your progress: Revisit your budget, goals, debt and investments periodically because income, expenses and financial priorities can change.
For securities-market learning, investors can also use RBI and SEBI educational resources rather than relying only on social-media recommendations.
Benefits of financial literacy
The importance of financial literacy lies in helping people make better money decisions, from comparing FD interest rates to understanding debt costs and investment risks. It improves the ability to evaluate product conditions, prepare for emergencies and build plans around realistic financial goals.
| Benefit | How it can help |
| Better budgeting | Helps align spending with available income |
| More disciplined saving | Encourages preparation for planned and unexpected expenses |
| Informed borrowing | Helps compare interest costs and repayment obligations |
| Better investment assessment | Supports comparisons involving risk, return, liquidity and tenure |
| Fraud awareness | Helps identify suspicious offers and misleading claims |
| Retirement planning | Encourages earlier preparation for future income requirements |
| Risk management | Supports informed decisions about insurance and emergency savings |
SEBI’s investor education resources show that practical financial literacy includes understanding products, risks, investor rights, fraud prevention and grievance mechanisms. If predictable interest suits a defined goal, compare the latest Bajaj Finance FD rate, tenure, payout option and premature-withdrawal terms before deciding whether to open an FD.
Types of investments and what to know before choosing one
-
Different investments serve different purposes. The right choice depends on your goal, time horizon, need for access to money and ability to accept fluctuations or issuer risk. An FD offers predetermined interest and lower market volatility, but it should not be described as universally risk-free or suitable for every investor.
Investment Main characteristic May be suitable for Important consideration Fixed deposits Predetermined interest for a selected tenure Investors seeking predictable interest for a defined period Issuer credit quality, liquidity, tax and withdrawal conditions Stocks Ownership in listed companies Long-term investors able to accept market fluctuations Market and company-specific risk Bonds Debt issued by governments or organisations Investors seeking fixed-income exposure Credit, interest-rate and liquidity risk Mutual funds Pooled investments managed according to stated objectives Investors seeking diversification across selected asset classes Scheme category, costs and market risk ETFs Exchange-traded funds tracking an index, asset or strategy Investors seeking market-linked diversification and exchange trading Market movements, tracking difference and liquidity For company FDs, credit ratings express the rating agency’s opinion about credit risk. They do not guarantee repayment. Bajaj Finance is an NBFC, and deposits mobilised by NBFCs are not covered under DICGC deposit insurance.
Also read: What is a Real Estate Investment Trust?
-
Conclusion
Financial literacy develops through continuous learning, regular financial planning, disciplined habits, and careful evaluation of financial products and associated risks.
Start by understanding your income, expenses, emergency requirements, outstanding debt, protection needs, financial goals, and available investment horizon.
When comparing investments, examine risk, liquidity, potential returns, costs, taxation, product conditions, and whether the investment matches your objectives.
Those prioritising predictable returns can explore safe investment approaches, including Fixed Deposits, while understanding that every financial product has considerations.
Calculate your expected investment returns with the help of our investment calculators such as PPF and Provident Fund Calculators.
Check out different FD Rates
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
What are the key financial literacy skills for smart purchasing?
Important skills include budgeting, price comparison, understanding borrowing costs, reviewing fees, assessing affordability, and distinguishing genuine needs from discretionary purchases. Reading product conditions carefully and avoiding impulsive borrowing can also help consumers make more informed purchasing decisions and control unnecessary debt.
How can I improve my financial literacy while in college?
Students can improve financial literacy by creating budgets, tracking expenses, learning about banking, credit, insurance, taxes, investing, and common financial scams. Starting with small savings goals and using reputable RBI, SEBI, or regulated-provider resources can strengthen practical money-management skills over time.
What are the three components of financial literacy according to the RBI?
The RBI framework identifies financial knowledge, financial behaviour and financial attitude. Knowledge covers financial concepts, behaviour covers how people manage money, and attitude reflects their approach to saving, spending, long-term security and risk.
Why is financial literacy important in India?
Financial literacy helps Indian consumers use banking, digital payments, loans, insurance and investments more carefully. It also supports responsible borrowing, fraud awareness, long-term planning and informed participation in formal financial services.
What is financial literacy, and what does it include?
Financial literacy is the ability to understand and apply money-related concepts. It includes budgeting, saving, borrowing, investing, insurance, taxation, fraud awareness, risk management, retirement planning and comparing financial products according to their costs and conditions.
How can students improve their financial literacy?
Students can begin by preparing a monthly budget, tracking small expenses and distinguishing needs from wants. They should also learn how bank accounts, interest, credit, digital payments, taxes and basic investments work while protecting passwords and other financial information.
What is financial literacy?
Financial literacy means having the knowledge, behaviour, and skills required to understand money and make informed personal financial decisions. It includes budgeting, saving, borrowing, investing, managing risks, understanding financial products, and planning effectively for short-term and long-term goals.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.