








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
Current Ratio - Meaning, Formula, and Example
In summary
The current ratio compares a company's current assets with its current liabilities. It provides a quick view of whether the company has enough short-term assets to cover obligations due soon.
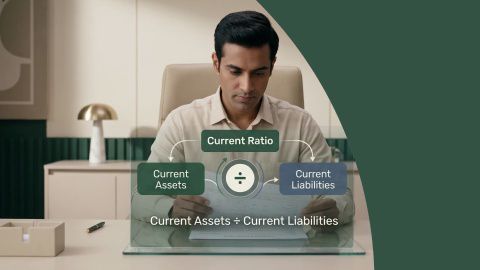
- Current Ratio = Current Assets ÷ Current Liabilities.
- A ratio above 1 means current assets exceed current liabilities.
- A ratio below 1 means current liabilities exceed current assets.
- A ratio of 1.5 means Rs. 1.50 of current assets for every Rs. 1 of current liabilities.
- There is no universal ideal current ratio.
- Industry, asset quality, and changes over time affect interpretation.
The current ratio is a liquidity measure, not a complete measure of financial health. A company with a high ratio can still face financial difficulties.
Compare the ratio with similar companies and review it alongside other financial measures before drawing conclusions.
What is current ratio?
The current ratio is a financial measure that compares a company's current assets with its current liabilities. It helps show whether the company has enough short-term assets to meet its short-term payment obligations.
Current assets are assets that a company expects to use, sell or convert into cash within a short period. They may include cash, accounts receivable and inventory. Accounts receivable means money that customers owe the company.
Current liabilities are amounts that the company needs to pay within a short period. They may include accounts payable, short-term borrowings and other amounts due soon.
A current ratio above 1 means the company has more current assets than current liabilities. However, this does not automatically mean that the company is financially strong. The type of assets, the industry and the company's past ratios also matter.
What is the current ratio formula?
The current ratio is calculated using the following formula:
Current Ratio = Current Assets ÷ Current Liabilities
The formula compares the value of a company's current assets with the value of its current liabilities.
For example, if a company has current assets of Rs. 6,50,000 and current liabilities of Rs. 4,00,000, the calculation is:
Current Ratio = Rs. 6,50,000 ÷ Rs. 4,00,000 = 1.625
This means the company has Rs. 1.625 of current assets for every Rs. 1 of current liabilities.
A ratio of 1 means current assets and current liabilities are equal. A ratio above 1 means current assets are higher. A ratio below 1 means current liabilities are higher.
What are the components of the current ratio?
The current ratio has two main parts: current assets and current liabilities. Understanding both makes it easier to understand what the ratio tells you.
Current assets are assets that a company expects to use, sell or convert into cash within a short period. They may include:
- Cash and cash equivalents
- Accounts receivable
- Inventory
- Marketable securities
- Short-term deposits
Current liabilities are amounts that a company expects to pay within a short period. They may include:
- Accounts payable
- Short-term borrowings
- Taxes due
- Declared dividends
- Outstanding wages
The value of these assets and liabilities is used in the current ratio formula. The result gives you a simple measure of the company's short-term financial position.
How do you calculate the current ratio?
You can calculate the current ratio by dividing total current assets by total current liabilities. Follow these steps to understand the calculation.
- Find the company's total current assets.
- Find the company's total current liabilities.
- Divide current assets by current liabilities.
- Read the result to understand the relationship between the two amounts.
For example, consider a company with the following figures:
| Specification | Details |
|---|---|
| Cash and cash equivalents | Rs. 1,50,000 |
| Accounts receivable | Rs. 3,00,000 |
| Inventory | Rs. 2,00,000 |
| Total current assets | Rs. 6,50,000 |
| Accounts payable | Rs. 2,50,000 |
| Short-term debt | Rs. 1,00,000 |
| Accrued expenses | Rs. 50,000 |
| Total current liabilities | Rs. 4,00,000 |
The calculation is:
Current Ratio = Rs. 6,50,000 ÷ Rs. 4,00,000 = 1.625
So, the company's current ratio is 1.625. This means it has Rs. 1.625 of current assets for every Rs. 1 of current liabilities.
What does the current ratio tell you?
The current ratio gives you an idea of how a company may manage its short-term payment obligations. However, you should not use the ratio on its own to judge the company's overall financial health.
A ratio above 1 means current assets are higher than current liabilities. This can indicate that the company has a stronger short-term position.
A ratio below 1 means current liabilities are higher than current assets. This may indicate that the company could face greater pressure when meeting its short-term obligations.
A very high ratio is not automatically better. It may mean that a company holds a large amount of cash, inventory or other current assets. These resources may not always be used efficiently.
The industry also matters. A company that holds a large amount of inventory may have a different current ratio from a service company. Therefore, it is more useful to compare a company with similar companies and look at changes over time.
What does a current ratio of 1.5 mean?
A current ratio of 1.5 means that a company has Rs. 1.50 of current assets for every Rs. 1 of current liabilities.
This may indicate that the company has some assets available beyond its current liabilities. However, 1.5 should not be treated as a universal ideal ratio. The appropriate level can vary across industries and businesses.
You can also compare the ratio with the company's earlier results. A steady improvement or decline may provide useful information when viewed with other financial measures.
Why is the current ratio important?
The current ratio is important because it gives a quick view of a company's ability to meet short-term financial obligations.
Different people may use the ratio for different reasons. The following are the main users of the current ratio:
- Investors: They may use it to understand a company's short-term financial position before making an investment decision.
- Creditors: Lenders may use it to assess whether a company appears able to meet its short-term payments.
- Management: Company managers may use it to monitor current assets and liabilities.
- Analysts: Analysts may compare the current ratio with other financial measures to understand a company's financial position.
The ratio is more useful when you consider it along with other information. A single current ratio cannot show the complete financial health of a company.
Who uses the current ratio?
The current ratio can be useful to investors, lenders, company management and financial analysts. Each group may use the ratio to understand the company's ability to meet short-term obligations.
Investors may compare the ratio with earlier periods or similar companies. Lenders may use it as one measure when assessing short-term repayment ability. Company management can use it to monitor current assets and liabilities.
The ratio should not be viewed in isolation. Other financial measures and information about the company are also important when assessing its financial position.
What are the limitations of the current ratio?
The current ratio is useful, but it has several limitations. These points are important because the ratio alone cannot give you a complete picture of a company's financial health.
- It does not show asset quality: Two companies may have the same current ratio, but their current assets may be very different.
- Inventory may take time to sell: Inventory is included in current assets, but it may not be converted into cash quickly.
- Seasonal changes can affect the ratio: A company's ratio may change at different points in its operating cycle.
- Inventory values can affect the result: Changes in inventory valuation can change the current ratio.
- It does not show the full financial position: Other financial measures are needed to understand the company's performance and risks.
- It can be misleading when viewed alone: A company may have a high current ratio but still face other financial problems.
For these reasons, use the current ratio along with other financial information. Comparing the ratio with similar companies and reviewing its movement over time can also give better context.
How is the current ratio different from the quick ratio?
The current ratio and quick ratio both help assess a company's short-term liquidity. However, they do not use exactly the same assets.
The current ratio includes all current assets. This can include inventory. The quick ratio is more conservative because it excludes inventory and focuses on assets that can generally be converted into cash more quickly.
The main difference can be summarised as follows:
| Specification | Details |
|---|---|
| Current ratio | Uses current assets, including inventory |
| Quick ratio | Uses more liquid current assets and excludes inventory |
| Main purpose | Gives a broader view of short-term liquidity |
| Comparison | Quick ratio gives a stricter view of the company's ability to meet short-term obligations |
Using both ratios can give a better understanding of a company's short-term financial position.
Conclusion
The current ratio compares a company's current assets with its current liabilities. It helps you understand whether the company has enough short-term assets to meet its short-term obligations.
A ratio above 1 means current assets are higher than current liabilities, while a ratio below 1 may indicate greater pressure on short-term payments. However, there is no single ratio that is ideal for every company.
Consider the company's industry, compare it with similar businesses and review changes over time. Also remember that the current ratio has limitations and should be used with other financial measures.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Interpreting the result
Using the ratio in financial analysis
How is the current ratio different from the quick ratio?
A current ratio of zero would mean the company has no current assets while having current liabilities greater than zero. This would indicate a serious short-term liquidity concern. If current liabilities are zero, the ratio cannot be calculated by dividing by zero. Review the balance sheet and reporting details before interpreting the result.
Can a company’s current ratio improve while its financial position worsens?
Yes. The ratio can rise because current liabilities have fallen or current assets have increased, but the reason matters. For example, a build-up of unsold inventory may increase current assets without improving cash availability. Check cash flow, inventory movement, receivables, and debt obligations before concluding that liquidity has improved.
How often should you review a company’s current ratio?
Review it whenever new financial statements become available, typically each quarter for listed companies and at least annually for annual accounts. Comparing several reporting periods can reveal changes in liquidity. For seasonal businesses, also consider the time of year because inventory, sales, and payment obligations can vary substantially during the operating cycle.
Can the current ratio be used to compare companies in different industries?
You can calculate the ratio for companies in different industries, but direct comparisons may be misleading. Retailers, manufacturers, and service providers have different inventory levels, payment terms, and working capital requirements. The ratio is generally more informative when compared with similar businesses and interpreted alongside industry practices and other financial measures.
Does a current ratio above 1 guarantee that a company can pay its bills?
No. A ratio above 1 means current assets exceed current liabilities on the reporting date, but some assets may not be available quickly. Inventory can take time to sell, and customers may pay late. Review cash flow forecasts, debt maturities, and the quality of receivables to assess payment capacity more fully.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.