The Sacred Valley and Cusco offer additional Inca sites and cultural attractions, but they are separate from the Machu Picchu citadel. Allow one or two extra days if these stops are part of your itinerary.
- Ollantaytambo: Explore the Inca terraces and the town's historic centre. The town is also an important departure point for trains to Aguas Calientes.
- Pisac: Visit the archaeological site and, depending on your schedule, the local market.
- Cusco's old town: Explore the historic centre of the former Inca capital.
- Moray: See the circular agricultural terraces associated with Inca farming practices.
Cusco is at a high altitude, so give yourself some time to rest after arrival before scheduling demanding walks or excursions. This also gives you room to adjust if the journey takes longer than planned.
Worked example: Siddharth in Pune
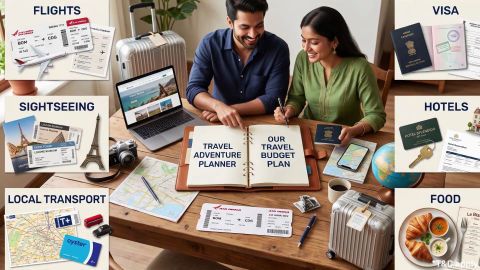
Siddharth is 38 and works as a salaried IT architect in Pune. He earns Rs. 1,30,000 per month, has a CIBIL score of 785 and holds a valid US visa. He plans a 10-day trip to Peru with his wife and sets an illustrative travel budget of Rs. 5 lakh based on the quotes he obtains.
| Expense | Budget for two (Rs.) |
|---|
| International flights | 2,10,000 |
| Visas, if required, and travel insurance | 30,000 |
| Domestic flights and trains | 60,000 |
| Hotels for 9 nights | 90,000 |
| Entry tickets, buses and guide | 30,000 |
| Food and local travel | 50,000 |
| Buffer | 30,000 |
| Total travel budget | 5,00,000 |
Illustrative budget. Obtain fresh quotes before booking, as prices depend on travel dates, availability and booking conditions.
Siddharth plans to use Rs. 2.4 lakh from savings and borrow the remaining Rs. 2.6 lakh through a personal loan. His US visa qualifies for Peru's visa exemption only if it meets the applicable validity requirements at the time of entry. The budget allows for visa expenses if required, along with travel insurance.
The loan calculations below assume an illustrative fixed interest rate of 14% per annum. This is an example for comparing repayment tenures, not a guaranteed Bajaj Finance offer.
EMI formula
EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]
Here, P is the principal in rupees, R is the monthly interest rate expressed as a decimal, and N is the repayment tenure in months. For an annual rate of 14%, R is 14 ÷ 12 ÷ 100. The EMI covers principal and interest, with the interest component declining as the outstanding principal reduces. Figures are rounded to the nearest rupee.
| Tenure | Monthly EMI (Rs.) | Total interest (Rs.) | EMI as a share of monthly salary |
|---|
| 24 months (2 years) | 12,483 | 39,600 | 9.6% |
| 36 months (3 years) | 8,886 | 59,903 | 6.8% |
Last reviewed: October 2026
The 36-month tenure lowers Siddharth's EMI by Rs. 3,597 per month but adds Rs. 20,303 in total interest. The processing fee on a Rs. 2.6 lakh loan can be up to Rs. 10,738, inclusive of applicable taxes. This fee is a financing cost in addition to the travel expenses shown in the budget.
Siddharth chooses the 24-month tenure in this illustration. The EMI is 9.6% of his monthly salary, and the shorter tenure reduces the total interest compared with the 36-month option. He should still account for his other monthly commitments before deciding whether the EMI is affordable.
What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.
Booking your Machu Picchu trip? With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online in about 5 minutes → receive funds within 24 hours* of approval.