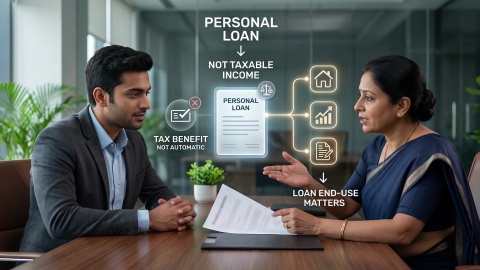
A personal loan does not provide any standard or special tax benefit. However, the interest paid may qualify for a tax deduction in certain circumstances, depending on the purpose for which the loan is used and the applicable provisions of the Income Tax Act. Eligibility for any deduction is subject to the relevant conditions and documentation requirements. Borrowers should refer to the latest applicable tax rules before claiming a deduction.
- Renovation of the home: In accordance with the Income Tax Act, you are entitled to a tax deduction if you borrow money to renovate your home or repair your home.
- Purchase a home or construct a home: If you borrow money to buy or build a home, you can deduct the interest you paid on the loan. You may deduct interest up to a certain limit if the home is used for personal use. The entire interest payment is deductible from your taxes if you rent it out.
- Education costs: You can claim tax deductions if you take out a personal loan to pay for your own education, that of your spouse, or that of your children. For a maximum of eight years, or until the debt is repaid, whichever comes first, this deduction may be used.
- Starting a business: As per the Income Tax Act, you may be allowed to deduct the interest paid on a personal loan taken out to launch or invest in a business.
Documents required to claim tax benefits
A personal loan is generally not taxable income because the borrowed amount must be repaid. However, interest may qualify for a tax deduction when the funds are used for an eligible purpose and the applicable tax conditions are met.
Key documents include:
Keep these records to support any eligible claim during tax assessment. The documents required may vary depending on the deduction claimed.
What tax benefit can you claim on a personal loan?
For personal loan income tax purposes, deductions may apply to eligible property-related interest or business borrowing costs. A personal loan does not automatically qualify for these deductions.
| Purpose of loan | Section | Potential deduction |
|---|
| Home purchase or construction | Section 80C | Up to Rs. 1.5 lakh overall, subject to conditions; ordinary personal loan repayments generally do not qualify |
| Eligible home purchase or construction interest | Section 24(b) | Up to Rs. 2 lakh for qualifying self-occupied property, subject to conditions |
| Home repair or renovation | Section 24(b) | Generally up to Rs. 30,000 for a self-occupied property |
| Business use | Section 36(1)(iii) or other applicable provisions | No fixed general monetary cap; eligibility and conditions apply |
| Education expenses | Section 80E | Interest deduction may apply only to a qualifying higher-education loan from an eligible institution |
The limits above are subject to the applicable tax regime and statutory conditions. Section 80C does not automatically cover personal loan principal repayments, and Section 80E does not cover every loan used for education.
Before applying for a Bajaj Finance Personal Loan, retain the relevant loan and expense records and consult a tax professional to confirm whether any deduction applies.
Tax deductions mentioned above are subject to the applicable provisions of the Income Tax Act, the relevant tax regime and eligibility conditions. A personal loan does not automatically qualify for tax benefits. The availability and amount of any deduction depend on the purpose of the loan and the borrower’s individual circumstances. Please verify the latest tax rules or consult a qualified tax professional before claiming a deduction.