7 Personal Loan Charges to Know Before You Borrow

7 Personal Loan Charges to Know Before You Borrow

Some personal loan charges apply to every loan, while others arise only if you slip, repay early or ask for something extra. Knowing which is which shows the real cost and which charges you can avoid.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


In summary

Of the 7 personal loan charges, 3 apply to every loan: interest, the processing fee and stamp duty. Two apply only if an equated monthly instalment (EMI) is late or bounces, and 2 only if you repay a Term Loan early. All are listed in the Key Fact Statement. The processing fee matters more than it looks: on a Rs. 2 lakh loan at an illustrative 16.75%, it lifts the true annual cost to about 21.1%.


  • Interest, processing fee and stamp duty: every loan.
  • Bounce and penal charges: only if you slip.
  • Prepayment and foreclosure: only if you repay early.
  • Compare the annual percentage rate, not the headline rate.


Want to see the personal loan charges before you borrow? Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.

What are the 7 charges?

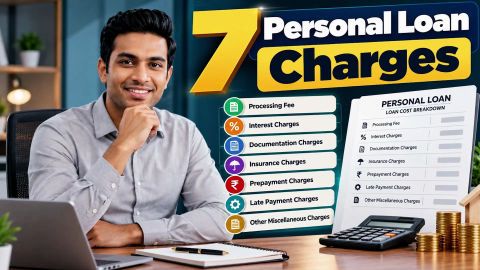
The table sets out the charges on a Bajaj Finance Personal Loan taken as a Term Loan, grouped by what triggers them. These are the personal loan charges you see in the Key Fact Statement.


ChargeWhen it appliesHow much
InterestEvery loanAt the rate in your Key Fact Statement, on the principal outstanding
Processing feeEvery loanUp to 4.13% of the loan amount, inclusive of applicable taxes
Stamp dutyEvery loanAs per the law of your state
Bounce chargeOnly if an EMI bouncesRs. 700 to Rs. 1,200 per bounce
Penal chargeOnly if an EMI is overdueUp to 36% per annum on the overdue instalment
Part-prepayment (Term Loan)Only if you prepayUp to 4.72% of the principal prepaid
Foreclosure (Term Loan)Only if you close earlyUp to 4.72% of the outstanding principal

Last updated: 26th October, 2026


Read the second column first. It shows that only 3 of the 7 are certain; the other 4 depend on how you run the loan. Your Key Fact Statement shows the exact figures for your loan, which can be lower than the caps above.

Show More Show Less

Which charges does every borrower pay?

These 3 personal loan charges come with the loan itself:

  • Interest: The largest of the personal loan charges in rupees, charged on the principal still owed, at the annual rate in your Key Fact Statement. It falls as the principal falls, which is why early prepayments save the most.
  • Processing fee: A one-time fee for assessing and setting up the loan. It comes out of the loan amount, so the money credited to your account is less than the amount you repay.
  • Stamp duty: One of the personal loan charges set outside the lender, this is a state levy on the loan agreement, set by the law of the state you sign in. The amount varies from state to state.

Of these personal loan charges, the processing fee is the one to watch when comparing offers. Two loans at the same rate can cost different amounts once these personal loan charges are counted.

Show More Show Less

How does the processing fee change the true cost?

Because the fee comes out of the money you receive, you pay interest on a larger amount than you get. The annual percentage rate (APR) captures this by folding the fee into one yearly figure. The table works it out for one loan with the fee at its upper limit.


Rs. 2 lakh at an illustrative 16.75% over 24 monthsFigure
Loan amountRs. 2,00,000
Processing fee at the upper limitRs. 8,260
Amount creditedRs. 1,91,740
EMI over 24 months at 16.75%Rs. 9,864
Annual percentage rate, fee includedAbout 21.1%

Last updated: 26th October, 2026


A headline rate of 16.75% becomes about 21.1% once the fee is counted. Regulated lenders show the APR in the Key Fact Statement, so compare offers on that figure, not on the rate alone. The shorter the tenure, the more the fee lifts the APR, as the fee is spread over fewer months.

Show More Show Less

Which charges can you avoid?

Four personal loan charges arise only from how you run the loan:

  • Bounce charge: Applied when an EMI presented for auto-debit is returned unpaid. An auto-debit set 1 to 3 days after payday, with a buffer in the account, removes the risk.
  • Penal charge: Applied on an overdue instalment from the due date until it is paid. It is a charge, not added interest, and stops once you clear the overdue amount.
  • Part-prepayment charge: Applied on a Term Loan when you pay part of the principal early. Set it against the interest the payment would save; if the saving is larger, prepay.
  • Foreclosure charge: Applied on a Term Loan when you close it before the tenure ends. Weigh it against the interest left on the schedule.

Bounce and penal personal loan charges are pure cost: they buy you nothing. Prepayment personal loan charges are different, as they come with an interest saving that can outweigh them.


Rahul's comparison

Rahul, 33, manages pharmaceutical sales in Bhopal on a salary of Rs. 48,000, and his CIBIL score sits at 738. The APR figures above are from his loan. He needed Rs. 2 lakh for his wife's postgraduate course fees, at an illustrative 16.75% per annum. He compared the EMI at 2 and 3 years, then read the personal loan charges in his offer.

EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. Here P = Rs. 2,00,000, R = 16.75 ÷ 1,200 and N = months.


TenureMonthly EMI (Rs.)Total interest (Rs.)EMI as share of salary (%)
24 months (2 years)9,86436,74720.5
36 months (3 years)7,10655,80514.8

Last updated: 26th October, 2026


A 3-year term means Rs. 2,758 less per EMI and Rs. 19,058 more interest, more than any of the other personal loan charges. With no plan to prepay, Rahul chose 24 months, kept the fee in his total cost, and set his EMI date 2 days after payday to avoid bounce charges.


What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.

Comparing offers on total cost? With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.


Show More

What about statements and documents?

Not every service carries one of the personal loan charges. Account statements, repayment schedules, interest certificates and no-dues certificates can be downloaded free from My Account. You do not need to pay a branch for copies you can download yourself. Keep your copies of the Key Fact Statement and agreement from the start, as they list every one of the personal loan charges that can apply to your loan.


Show More

How do you keep the total cost down?

Most of the cost, and most personal loan charges, are set before you sign, so the choices that matter come early:

  • Compare APRs: Get a Key Fact Statement from each lender on an identical amount and tenure, and compare the annual percentage rate.
  • Borrow only what you need: A smaller loan means smaller personal loan charges: a lower fee as well as less interest.
  • Choose the shortest tenure you can carry: Interest falls sharply with a shorter tenure, as Rahul's table shows.
  • Never miss an EMI: Set auto-debit after payday and keep one EMI as a buffer in the account.
  • Prepay when the maths works: Set any prepayment charge against the interest saved before you pay.
Show More

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Fees

Prepayment and closure

What is the processing fee on a Bajaj Finance Personal Loan?

The processing fee is up to 4.13% of the loan amount, inclusive of applicable taxes. It is a one-time charge, and on a Rs. 2.75 lakh loan, it is up to Rs. 11,358. Of all personal loan charges, it is the only one every borrower pays, so add it to the interest when you compare offers.

A bounce charge applies each time an EMI payment fails, and penal charges apply on the overdue amount until it is paid. On Kavya's EMI of Rs. 9,466, penal charges would be up to about Rs. 284 for a month overdue. Pay as soon as you can, since these personal loan charges grow with time.

It depends on the variant. Flexi Dropline and Flexi Hybrid Loans allow part-prepayment with no extra charge. On a Term Loan, the part-prepayment charge is listed in the fees table; on Rs. 50,000, it is up to Rs. 2,360. Compare the charge with the interest saved before you prepay, since personal loan charges reduce the saving.

On a Term Loan, the foreclosure charge is a percentage of the outstanding principal, as listed in the fees table. In Kavya's case, closing after 12 EMIs with Rs. 1,96,184 outstanding would cost up to Rs. 9,260. Check the outstanding amount in My Account and your KFS before you decide, and list all personal loan charges first.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000