How Can Salaried Professionals Obtain a Personal Loan For an MBA

How Can Salaried Professionals Obtain a Personal Loan For an MBA

Check your eligibility foaA personal loan for an MBA lets salaried professionals fund fees while they keep earning, with amounts up to Rs. 75 lakh. Check eligibility, documents and monthly repayments before you enrol.r personal loan of Rs. 3 lakh in Pune with your phone and OTP - no branch visit needed.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed

Key Takeways


Last updated: 13th October, 2026


In summary

A personal loan for an MBA suits working professionals who will keep their salary during the course, because repayments start straight away. Fee timing and tenure matter as much as the interest rate.


  • Bajaj Finance Personal Loan amounts range from Rs. 40,000 to Rs. 75 lakh.
  • The interest rate ranges from 10% to 30.5% per annum, subject to eligibility.
  • Tenure runs from 12 months to 108 months (1 years to 9 years).
  • A CIBIL score of 650 or higher is a listed criterion.
  • Rs. 8 lakh at 14% per annum costs Rs. 27,342 a month over 36 months (3 years).


If your fees are due semester by semester, a Flexi Dropline Loan lets you withdraw as each payment falls due. Compare it with a Term Loan before you apply.

How does a personal loan for an MBA work?

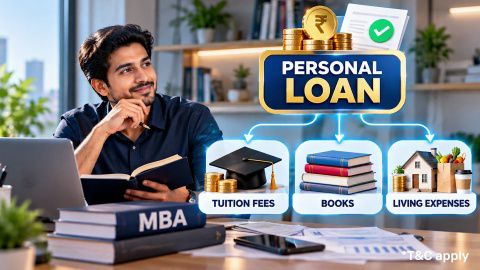
A personal loan is an unsecured loan: you borrow a fixed sum without pledging collateral and repay it in equated monthly instalments (EMIs). For an MBA, you use the funds for tuition, books, a laptop or travel to campus. Repayment starts after disbursal, so the loan suits professionals who keep their salary while they study, such as on an executive, weekend or online MBA.


Because the loan is not tied to a college or course, you decide how to spend it. You also carry the full EMI during the course, so plan it against your current take-home pay.

Show More Show Less

How should you compare MBA financing options?

Each option has its own terms, rate and repayment schedule. Compare them before you choose.


OptionSuits you ifTrade-off
SavingsYou can cover fees and still keep an emergency fundSmaller cushion during the course
Employer sponsorshipYour employer funds part of the courseOften comes with a service bond
Education loanYou will study full-time and want to defer repaymentTied to the institution; may need a co-borrower or collateral
Personal loanYou keep working and want funds you controlEMIs start at once; unsecured-loan rates apply
Show More Show Less

What should you plan before you borrow?

Map your fee schedule before you choose the amount and variant. Most MBA programmes split fees across terms, and some add costs for books, residential weeks or international modules.


QuestionWhy it matters
When is each fee due?Decides whether a Term Loan or a Flexi Dropline Loan suits you
Will your employer reimburse any fees?Lowers the amount you need to borrow
Will your salary continue through the course?EMIs start straight away, so you need steady income
Do you expect a raise after the MBA?A planned part-prepayment can shorten the loan

Answering these first stops you borrowing the full course fee on day one when only the first term is due. It also tells you how much of your salary the EMI can safely take.

Show More Show Less

Why does your CIBIL score matter?

Your CIBIL score affects both your approval chances and the rate you are offered. It reflects your payment history, outstanding debt and the length of your credit history. A score of 650 or higher is one of the listed criteria for a Bajaj Finance Personal Loan, but meeting it does not guarantee approval.


If your score is close to the threshold, pay every EMI and card bill on time for a few months before you apply. A higher score can lower the rate, which matters on a large, multi-year MBA loan.

Show More

Am I eligible for a personal loan for an MBA?

Check the personal loan eligibility criteria before you apply. The basic criteria are:


CriterionRequirement
NationalityIndian
Age21 years to 80 years
EmploymentPublic, private or multinational company (MNC)
CIBIL score650 or higher
Customer profileSalaried or self-employed

*You should be 80 years or younger, at the end of the loan tenure.

Show More

Which documents do you need?

The documents required for a personal loan vary by applicant. You may need:


Document categoryAccepted options
KYC proofAadhaar/ passport/ voter’s ID/ driving license/ Letter of National Population Register/ NREGA job card
Identity proofPAN card, Real-time image / photograph
Employment proofEmployee ID card, Letter of Allotment of Accommodation Issued by Employer
Income proofSalary slips — last 3 months, Bank account statements — last 3 months
OthersPension order, Utility bill, Phone bill, Piped gas bill, Property / Municipal tax receipt

Keep your MBA admission letter and fee schedule handy too. They help you decide the amount and timing, even though they are not on the listed document set.

Show More

Term Loan or Flexi Loan for MBA fees?

MBA fees are often paid in instalments across semesters. The loan variant you pick changes how much interest you pay while those instalments are still due.


VariantHow it worksSuits MBA fees if
Term LoanFull amount disbursed once; fixed EMIs on the whole sumThe college wants the full fee upfront
Flexi Dropline LoanWithdraw from a limit as needed; interest only on the amount usedFees fall due semester by semester
Flexi Hybrid LoanInterest-only EMIs for up to the first 36 months (3 years), then principal and interestYou want lower EMIs during the course

Flexi Loans carry no part-prepayment charge, which helps if you plan to repay early after a post-MBA salary rise. A Flexi facility charge and annual maintenance charges apply, so compare the total cost in the Key Fact Statement.

Show More

What will an MBA loan cost each month?

Worked example: Varun in Chennai

Varun is 29 and works as a salaried product analyst in Chennai. He earns Rs. 1,20,000 a month and has a CIBIL score of 775. He has joined a two-year executive MBA with total fees of Rs. 8 lakh. He compares a Term Loan for the full amount at an illustrative 14% per annum.


EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1], where R is the monthly rate and N is the tenure in months. All figures are rounded to the nearest rupee.


TenureMonthly EMITotal interestEMI as share of salary
36 months (3 years)Rs. 27,342Rs. 1,84,31622.8%
60 months (5 years)Rs. 18,615Rs. 3,16,87615.5%

The 60-month option lowers the EMI by Rs. 8,727 but adds Rs. 1,32,560 in interest. The processing fee on Rs. 8 lakh is up to Rs. 33,040, inclusive of applicable taxes. Varun picks 36 months (3 years) and plans to part-prepay if his salary rises after the MBA. Because his fees are due semester-wise, he also asks for a Flexi Dropline quote so he pays interest only on what he has drawn.


What can delay approval: a CIBIL score below 650, high existing EMIs relative to income, mismatched document details or several recent loan applications. Apply well before your first fee deadline.

Show More

How do you apply for a personal loan for an MBA?

  1. Check loan eligibility: Enter the loan amount and repayment period, then click "CHECK LOAN OFFER".
  2. Enter personal details: Enter your personal, financial and employment details to receive a personalised offer.
  3. Loan offer: Review the offer and adjust the amount or tenure to suit your needs.
  4. KYC verification: Complete KYC information checks and verify your bank details.
  5. Talk to loan specialist: Your application is submitted, and an executive contacts you about the next steps.


Once your documents are verified, the amount may reach your account within 24 hours* of approval. Use the personal loan EMI calculator and review the personal loan interest rates before you accept an offer.


*Terms and conditions apply.

Show More

Is a personal loan the right way to fund your MBA?

A personal loan suits you if you will keep working through the course and the EMI fits your current budget. If you plan to study full-time and stop earning, an education loan with deferred repayment may suit you better. Either way, work out the total cost, including fees, before you commit.

Show More

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Planning the loan

Costs and repayment

Can you get a personal loan for a full-time MBA?

You can apply if you meet the eligibility criteria, but a personal loan's EMIs start soon after disbursal. If you leave your job to study full-time, you would need another way to pay those EMIs during the course. Salaried professionals on executive, weekend or online programmes are better placed, because their income continues while they repay.

Borrow the gap between your total course cost and what savings or employer support cover. Add tuition, books, a laptop and travel, then subtract what you can pay yourself. On Rs. 8 lakh at 14% per annum, the EMI is Rs. 27,342 over 36 months (3 years), so test smaller amounts if that share of your salary feels high.

It can be, if your fees are due in stages. A Flexi Dropline Loan charges interest only on the amount you withdraw, so you avoid paying interest on fees not yet due. Flexi Loans also carry a Flexi facility charge and annual maintenance charges, so compare the total cost of both in the Key Fact Statement.

Yes. Flexi Dropline and Flexi Hybrid Loans carry no part-prepayment charge, so you can pay down the balance when your income grows. A Term Loan may carry part-prepayment and foreclosure charges of up to 4.72%, inclusive of applicable taxes. Check your loan agreement for the exact charges before you prepay.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000