







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
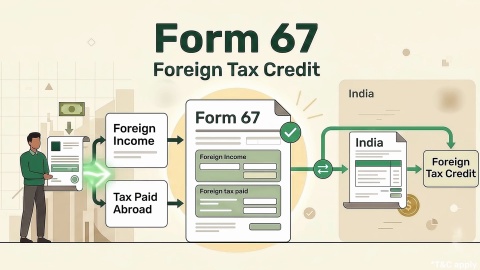
Form 67 - Claim Of Foreign Tax Credit
Last updated: Oct 2026
Form 67 lets a resident claim credit in India for tax already paid abroad on the same income. The credit is the lower of the foreign tax paid and the Indian tax on that income. File it before your return.
- Earlier years: assessment year (AY) 2026-27 and earlier, under Rule 128 of the Income Tax Rules, 1962
- Form 44: Tax Year 2026-27 onwards, under Rule 76 of the Income Tax Rules, 2026
- Deadline: the end of the assessment year, which is 31 March 2027 for AY 2026-27
- Cap: the lower of foreign tax paid and Indian tax attributable
Example: Rs. 1,00,000 of foreign tax on Rs. 4,00,000 of dividends gives a Rs. 1,00,000 credit
Match the figures on the statement to your return schedules. A return processed without the credit raises a demand that is harder to reverse.
What is Form 67 and who files it?
Form 67 is the online statement through which a resident taxpayer claims a foreign tax credit (FTC). It prevents the same income being taxed twice, once abroad and once in India.
It applies where foreign income is taxed abroad and also taxable in India. The relief comes from the Double Taxation Avoidance Agreement (DTAA) with the other country, under Sections 90, 90A and 91 of the Income Tax Act, 1961. Section 90 becomes Section 159 under the Income Tax Act, 2025.
Show more
Show less
Which form applies to which year?
The year of the income decides the form, not the year in which you file.
| Income earned in | Form | Rule |
|---|---|---|
| Financial year 2025-26 (AY 2026-27) and earlier | Form 67 | Rule 128, Income-tax Rules, 1962 |
| From 1 April 2026 (Tax Year 2026-27) | Form 44 | Rule 76, Income-tax Rules, 2026 |
The older form stays valid for earlier years even when you file it after 1 April 2026. Form 44 makes the foreign Tax Identification Number (TIN) mandatory. Select the right form and the matching year on the portal, because a wrong year mismatches your return.
Show more
Show less
What is the deadline for Form 67?
For AY 2026-27, the outer date is 31 March 2027, the end of the assessment year. Rule 128(9), amended with effect from 1 April 2022, allows filing up to that date if your return was filed within the time allowed under Section 139(1) or 139(4).
| Return | Due date for AY 2026-27 | Outer date |
|---|---|---|
| Original return | 31 July 2026 | 31 March 2027 |
| Belated return | 31 December 2026 | 31 March 2027 |
| Updated return | Within the updated-return window | With the updated return |
File the statement before the return, not after. If the department processes your return without the credit, it raises a demand, and the fix then becomes an appeal.
Show more
Show less
How do I file Form 67 online step by step?
Six steps cover it, and the calculation comes first.
- Work out the credit country by country and source by source.
- Collect the foreign tax statement and proof that you paid it.
- Log in to the portal and open the forms section.
- Select the form and the assessment year that your return uses.
- Enter the foreign income, the foreign tax and the Indian tax attributable, then attach the documents.
Submit and verify as the portal prompts, then file your return and mirror the same figures in its schedules.
Read aloud: calculate, collect, open, select, enter, submit. Do not select Form 44 for AY 2026-27 or earlier.
Show more
Show less
Home loan for professionals
How is the foreign tax credit calculated?
The credit equals the lower of the foreign tax you paid and the Indian tax on that same income. Any foreign tax above the Indian tax is lost.
Formula used: Credit = lower of (foreign tax paid, Indian tax attributable to the foreign income).
| Case | Foreign tax (Rs.) | Indian tax (Rs.) | Credit (Rs.) | Lost (Rs.) |
|---|---|---|---|---|
| Foreign tax below Indian tax | 1,00,000 | 1,20,000 | 1,00,000 | 0 |
| Foreign tax above Indian tax | 1,50,000 | 1,20,000 | 1,20,000 | 30,000 |
Assumptions: Rs. 4,00,000 of dividends, with an Indian tax of Rs. 1,20,000 including cess. In the first case, the foreign country withheld 25%.
Show more
Show less
A worked example: Rs. 4 lakh of foreign dividends
Consider Karthik, a 37-year-old engineer in Hyderabad with a household income of Rs. 3.5 lakh a month and a CIBIL Score of 781, who received Rs. 4,00,000 of dividends from foreign shares. The country of source withheld 25%.
| Item | Amount |
|---|---|
| Foreign dividend | Rs. 4,00,000 |
| Foreign tax withheld at 25% | Rs. 1,00,000 |
| Indian tax on the dividend (assumed) | Rs. 1,20,000 |
| Credit claimed | Rs. 1,00,000 |
| Indian tax still payable | Rs. 20,000 |
Karthik filed the statement in August, then filed ITR-2. See which form fits in the guide to which return form a salaried person files.
Show more
Show less
What happens if I miss Form 67?
You lose the credit for that year. The department can allow a late filing on a request with a valid reason, but you should not count on it.
If your return is processed without the credit, expect a demand notice. You then have to defend the position, which takes more effort than filing the form first. If a foreign tax authority later refunds tax for which you claimed credit, you must reduce the credit.
Show more
Show less
Does foreign income affect my home loan with Bajaj Finance?
Bajaj Finance reviews income documents, so a return that reports foreign income and the credit claimed keeps your records consistent.
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 Crore* |
| Tenure | Up to 32 years |
Approval timelines can extend where income records show foreign income that needs clarification, and minimum income thresholds can differ by city. Check your home loan eligibility.
Frequently Asked Questions
Claiming the credit
Timing and corrections
Can I claim foreign tax credit without Form 67?
No. Rule 128 requires the statement, so a claim in the return alone does not work. File the form, attach the proof of foreign tax, and make the figures match your return. If the figures differ, the processing system can disallow the credit and raise a demand, and you then have to respond to the notice.
Which form do I use if I file in 2026 for income earned in 2025?
Use Form 67. The year of the income decides the form. Income earned in FY 2025-26 belongs to AY 2026-27, so Form 67 applies even if you file after 1 April 2026. Form 44 applies only to income earned from 1 April 2026. Select the same assessment year on the form that your return uses.
Can I file Form 67 after I file my return?
The rule allows it up to the end of the assessment year, if the return was filed in time. In practice, file it before the return. Once the department processes a return without the credit, a demand follows. You then have to fix the position through an appeal, which takes more effort than filing the form first.
Does the credit cover every foreign tax?
No. It covers tax paid on income that is also taxable in India, and the credit is capped at the Indian tax on that income. Tax under dispute abroad is not creditable until the dispute ends. Keep the foreign tax certificate and proof of payment, because both are needed to support the claim.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.