








Clear your overdue EMI
Clear your overdue EMI today – stop penalties & fix your credit
*Overdue charges include penalty interest and bounce fees as applicable. T&C apply.
In Summary
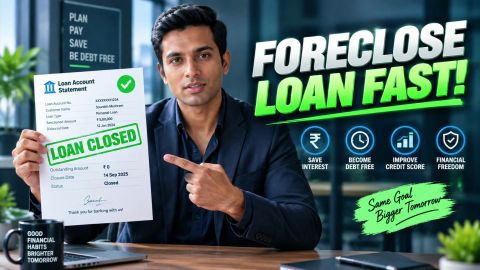
Follow the correct step-by-step process to foreclose or cancel loans
Early car loan closure involves repaying the eligible outstanding amount before the scheduled tenure ends. Understanding applicable charges, the foreclosure amount, closure process, required documents and CIBIL reporting helps borrowers complete the process and track their loan status.
- Foreclosure charges, outstanding principal, accrued amounts and applicable dues may form part of the final closure amount.
- The current foreclosure statement should be checked to determine the exact amount payable before making the final payment.
- Car loan foreclosure can be initiated through available digital servicing channels, followed by confirmation of account closure and applicable NOC.
- Loan closure and removal of vehicle hypothecation are separate processes, requiring the applicable documents and RTO procedure.
- After closure, borrowers should review their CIBIL report and raise a correction request if the reported loan status is inaccurate.
What is the early closure of a car loan?
Early closure, also called foreclosure or full prepayment, means clearing the eligible outstanding amount before the scheduled end of the car loan. The loan account can then be closed after the applicable dues and closure requirements are completed. The amount required for closure can include the outstanding loan balance and applicable charges or dues under the loan terms. The exact foreclosure amount should therefore be obtained for your loan account rather than estimated from the original loan amount. Early closure is different from part payment. Part payment reduces a portion of the outstanding principal while the loan continues, whereas full prepayment is intended to clear the eligible outstanding loan and close the account. After full repayment, obtain the applicable closure documents and NOC. These documents can also be required when completing the process to remove hypothecation from the vehicle's Registration Certificate (RC).
What charges apply to early car loan closure?
Early car loan closure, also called foreclosure or full prepayment, means repaying the eligible outstanding loan amount before the scheduled end of the tenure. Applicable charges depend on the terms of your specific loan and should be checked before initiating closure.
| Charge or amount | What it means |
| Foreclosure or prepayment charges | A charge may apply for closing the loan before the scheduled tenure, depending on the applicable loan terms. |
| Outstanding principal | The remaining principal amount must be paid as part of the eligible closure amount. |
| Accrued interest or other applicable dues | Any amount due up to the date of closure may need to be included in the final payment. |
| Overdue amounts | Any unpaid instalments or applicable overdue charges may need to be cleared before the loan can be closed. |
| Other applicable charges | Any additional amount specifically mentioned in your loan agreement or applicable schedule should be checked before payment. |
The exact closure amount can vary based on your loan account, repayment history and applicable terms. Review the foreclosure statement or account details before making the payment to understand the total amount required for early closure and retain the closure confirmation for your records.
How to calculate the car loan foreclosure amount?
The foreclosure amount is based on the outstanding amount payable on the date of full prepayment, together with applicable charges and other dues shown for the loan account. The exact amount can change as the account is updated, so use the current foreclosure statement or amount provided for your loan.
Before making the payment, check:
- Outstanding principal: Review the principal remaining on the loan.
- Accrued amount: Check any amount that has become payable up to the proposed closure date.
- Applicable charges: Review foreclosure charges and other applicable charges shown for your loan.
- Overdue amounts: Confirm whether any unpaid EMI or other overdue amount remains.
- Final payment amount: Use the current amount communicated for foreclosure rather than calculating it from an older statement.
A final payment should be made against the applicable foreclosure amount. Paying an approximate amount can leave a balance if additional dues or charges remain on the account.
How to close a car loan early online?
You can initiate the early closure process through the available servicing channels after checking the applicable terms and foreclosure amount for your loan. Bajaj Finance provides digital loan servicing through My Account and the Bajaj Finance App, including access to loan information and service requests.
The process is:
- Sign in to My Account or the Bajaj Finance App using your registered details.
- Select the relevant car loan account.
- Review the outstanding balance and available foreclosure or full-prepayment option.
- Check the applicable foreclosure amount and charges shown for the account.
- Make the required payment through the available authorised payment option.
- Check that the loan account reflects the completed repayment and closure.
- Obtain the applicable NOC and other closure documents.
If the required option or information is not available online, use an official customer service channel or branch to confirm the applicable process for your loan.
What should you do after closing a car loan?
After early closure, confirm that the loan account has been closed and retain the NOC and other applicable closure documents. A car loan NOC confirms that the loan has been fully repaid and is used for vehicle-related processes such as removal of hypothecation. You should also review the vehicle records. Car loan closure and removal of hypothecation from the RC are separate steps, so the lender's NOC and other required documents may need to be submitted through the applicable RTO process.
Keep the following records:
- Final payment confirmation
- Loan closure confirmation
- NOC or applicable no-dues document
- Foreclosure statement
- Documents required for hypothecation removal
- Updated vehicle records after the applicable RTO process
These records can help resolve discrepancies if the loan or vehicle records do not reflect the completed closure.
How does early car loan closure affect CIBIL?
A fully repaid car loan is reported as closed, while an account closed after accepting less than the full amount due can be reported as settled. CIBIL states that a settled status can have an adverse effect on access to credit, while a closed account remains part of your credit history. Early closure itself should not be treated as a guaranteed way to increase your CIBIL Score. CIBIL reports that closed accounts continue to appear as part of your credit history, and the overall score depends on information in your credit report. After making the final payment, check your credit report when the lender's updated information has been reported. From 1 January 2025, credit information is required to be updated on a fortnightly basis, or at a shorter interval where mutually agreed, subject to the applicable reporting process. If the loan continues to appear incorrectly after the relevant reporting period, first contact the lender for correction. You can also raise a dispute with CIBIL where appropriate.
Read more
Not your nearest branch?

Frequently Asked Questions
Early Closure Basics
Overdue & Closure
How long does the car loan closure process take after payment?
The closure timeline depends on the lender's processing and the completion of applicable requirements. After making the final payment, verify that the loan account reflects closure and retain the confirmation and applicable closure documents.
What documents are provided after car loan foreclosure?
After the loan is fully repaid, you should obtain the applicable closure documents, including the NOC or no-dues document and foreclosure statement. Retain these records for future vehicle-related or financial requirements.
What happens to vehicle hypothecation after car loan closure?
Closing the loan does not automatically remove hypothecation from the vehicle's Registration Certificate. The applicable NOC and other required documents may need to be submitted through the relevant RTO process.
Where can you find the final car loan foreclosure amount?
The current foreclosure amount can be checked through the available loan servicing channels or the foreclosure statement for your account. Use the amount applicable on the proposed closure date rather than relying on an older statement.
What if the car loan still shows an outstanding amount after payment?
Review the payment confirmation and current loan account details to identify any remaining amount. If the account does not reflect the expected closure, contact the lender through an authorised channel to verify the status and applicable dues.
How should you verify car loan closure after foreclosure?
Check that the loan account shows the completed repayment and closure status. You should also retain the final payment confirmation, foreclosure statement, NOC and other applicable closure documents for your records.
What should you do if the NOC is not received after car loan closure?
Check the loan account and applicable service channels for the NOC or closure document. If it is not available after the closure process is completed, contact the lender through an authorised channel for assistance.
When should you check your CIBIL report after car loan closure?
Check your CIBIL report after the lender's updated information has been reported. If the loan status remains incorrect after the relevant reporting period, contact the lender first and raise a dispute with CIBIL where appropriate.
More Articles
Disclaimer
While care is taken to update the information, products, and services included in or available on our website and related platforms/websites, there may be inadvertent inaccuracies or typographical errors or delays in updating the information. The material contained in this site, and on associated web pages, is for reference and general information purpose and the details mentioned in the respective product/service document shall prevail in case of any inconsistency. Subscribers and users should seek professional advice before acting on the basis of the information contained herein. Please take an informed decision with respect to any product or service after going through the relevant product/service document and applicable terms and conditions. In case any inconsistencies observed, please click on reach us.
*Terms and conditions apply.