







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
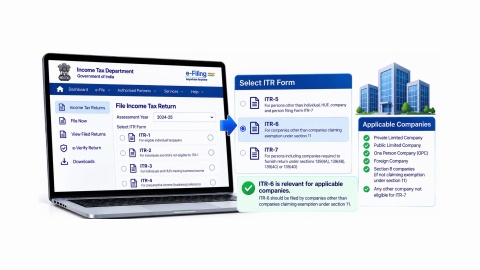
ITR 6 Form - How to File ITR 6 Online AY 2025-26
Last updated: Sept 2026
ITR-6 form is not one of the individual return forms most taxpayers encounter. It's built specifically for corporate structure, with reporting requirements individual and even partnership filers never face.
- Applies to: all companies except those claiming Section 11 exemption, which file ITR-7 instead
- Filing method: mandatory e-filing with Digital Signature Certificate, no paper option available
- Audit requirement: most companies filing ITR-6 also require a tax audit under Section 44AB, filed separately as Form 3CA/3CB and 3CD
- Due date: later than individual due dates as a rule, since companies commonly require audit completion first
Schedule complexity: ITR-6 includes significantly more schedules than individual forms, covering depreciation, MAT, and other company-specific provisions
Confirm your company doesn't qualify for Section 11 exemption before assuming ITR-6 form is the correct filing, since that specific exemption redirects filing to ITR-7 instead.
Does every company file ITR-6, or are there exceptions?
Nearly every company files ITR-6, but one specific exception exists. Companies claiming exemption under Section 11 — organised for charitable or religious purposes holding property for that purpose, as a rule — file ITR-7 instead of ITR-6.
Confirming which category your company falls into is the first genuine step before assuming ITR-6 form applies to your situation. The realistic categories a company might fall into are:
- A standard company, whether private limited, public limited, or one-person company, filing ITR-6 regardless of turnover
- A company claiming Section 11 exemption specifically for charitable or religious property income, filing ITR-7 instead
A foreign company with income in India, also required to file ITR-6 for that Indian-sourced income, as a rule
Assuming ITR-7 applies simply because a company has a charitable-sounding name, without confirming actual Section 11 exemption eligibility, is a genuine and consequential filing mistake.
Show more
Show less
What does ITR-6 actually require beyond basic company details?
| Requirement | Detail |
|---|---|
| Digital Signature Certificate | Mandatory for filing, no alternative verification method |
| Tax audit report | Required for most companies under Section 44AB, filed as Form 3CA/3CB and 3CD |
| Balance sheet and profit-loss schedules | Detailed financial statement schedules built into the form itself |
| MAT computation | Minimum Alternate Tax schedule, applicable where relevant |
| Depreciation schedule | Detailed asset-wise depreciation calculation under the Income Tax Act |
The mandatory DSC requirement is a genuine practical hurdle for a company filing ITR-6 form for the first time, since obtaining a valid DSC takes time and should be arranged well before the filing deadline approaches.
Show more
Show less
How do I prepare for an ITR-6 filing?
Five steps prepare a company's filing before the actual submission stage.
- Confirm the company doesn't qualify for Section 11 exemption, ruling out ITR-7 as the applicable form.
- Complete the statutory tax audit under Section 44AB, if applicable, well before the filing deadline.
- Obtain or renew the company's Digital Signature Certificate, since filing cannot proceed without a valid one.
- Gather the audited financial statements, depreciation schedules, and any MAT computation required.
File through the income tax e-filing portal, uploading the audit report reference and completing all applicable schedules.
Leaving DSC renewal until the filing deadline is imminent is a common, avoidable delay, since the certificate issuance process itself takes time that a last-minute approach doesn't accommodate.
Show more
Show less
A worked example: preparing a private limited company's filing
Consider Ashish, a 44-year-old director of a private limited company in Bengaluru, personally holding a household income of Rs. 2.2 lakh a month and a CIBIL Score of 761, preparing his company's Tax Year 2026-27 filing.
| Step | Status |
|---|---|
| Section 11 exemption check | Confirmed not applicable, standard company |
| Tax audit under Section 44AB | Completed by the company's chartered accountant |
| DSC renewal | Renewed 3 weeks before the filing deadline |
| ITR-6 filing | Submitted with all schedules and audit report reference |
Because Ashish's company renewed its DSC well ahead of the deadline, the actual filing proceeded without the last-minute certificate delays that affect companies who leave this step too late.
Show more
Show less
Home loan for professionals
Financing property alongside company tax compliance with Bajaj Finance
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 Crore* |
| Tenure | Up to 32 years |
A company director's personal home loan eligibility is assessed on personal income and credit profile, separate from the company's own ITR-6 filing. Approval timelines can extend where personal income documentation needs cross-verification, and minimum income thresholds can differ by city. Check your home loan eligibility with your personal financial documentation in order.
Show more
Show less
Frequently Asked Questions
Understanding the form
Practical preparation
Can a small private limited company with minimal turnover skip ITR-6 and file a simpler form instead?
No, ITR-6 applies to companies regardless of turnover or size, unlike individual forms where a simpler option exists for straightforward income. Even a dormant or minimal-activity company incorporated as a private limited entity must file ITR-6, provided it doesn't qualify for the Section 11 exemption redirecting it to ITR-7 instead.
What happens if a company misses its ITR-6 filing deadline?
The company faces late-filing interest and fees similar in principle to individual late filing, calculated on any unpaid tax, alongside a fixed late fee under the applicable provision. Persistent non-filing can also affect the company's compliance standing and future dealings with banks, regulators, and prospective business partners.
Is a Digital Signature Certificate expensive or difficult to obtain for a company?
Obtaining a Class 3 DSC for a company director involves a modest fee and a verification process through a licensed certifying authority, completed within a few working days as a rule. The main practical risk is leaving this until close to the filing deadline, rather than the process itself being genuinely difficult.
Does a company need a fresh DSC every year, or does one certificate last multiple filings?
A DSC is valid for 1 to 3 years as a rule, depending on the certificate type purchased, not a single filing only. Track your specific certificate's expiry date, since filing with an expired DSC fails at submission and requires urgent renewal if discovered too close to the actual deadline.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.