What a 777 Credit Score Means for Your Loan

What a 777 Credit Score Means for Your Loan

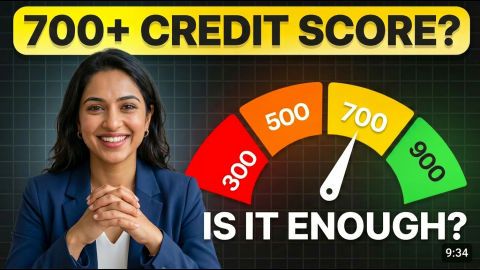
A 777 credit score sits well above the Bajaj Finance criterion of 650 on the CIBIL scale of 300 to 900. It supports your application, but income, existing loans and verification still decide the outcome.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


In summary

A score of 777 shows a strong repayment record and puts you well above the criterion for a Bajaj Finance Personal Loan. It can support a better rate offered, but it does not guarantee approval.


  • CIBIL scores run from 300 to 900.
  • Such a score is about 80% of the way up that scale.
  • Lenders still assess income and existing equated monthly instalments (EMIs).
  • Aniket, with a score of 777, borrows Rs. 5 lakh at 12% over 48 months.

With a strong score, see your offer: Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.

What does a 777 credit score mean?

A 777 credit score means your record shows mostly on-time payments and controlled credit use. It sits about 80% of the way up the 300 to 900 CIBIL scale and well above the Bajaj Finance criterion.

Show More Show Less

What can a 777 score do for you?

A 777 score can help your application, but it has limits. The table separates the two.


What a 777 score can doWhat it cannot do
Meet the Bajaj Finance criterion of 650 or higherGuarantee approval
Support a better rate offeredOverride income or existing EMIs
Show a strong repayment recordStay at 777 without on-time payments

Last updated: 22nd October, 2026


Your offer reflects your whole profile. A strong score works alongside stable income and modest existing EMIs.

Show More Show Less

How do you keep a 777 score?

You keep a 777 score with 4 habits, led by on-time payment. The table sets them out.


HabitWhy it keeps the score
Pay every EMI and card bill on timeRepayment record drives the score
Keep card balances well below the limitShows you are not stretched
Space out loan applicationsEach one adds an enquiry
Check your report each yearCatches errors early

Last updated: 22nd October, 2026


Since January 2025, lenders report every 15 days, so a single late payment shows sooner. Set auto-debits for every EMI.


Worked example: Aniket in Ghaziabad

Aniket is 37 and works as a salaried telecom project manager in Ghaziabad. He earns Rs. 1,50,000 a month and has a CIBIL score of 777. He borrows Rs. 5 lakh to renovate his home, at an illustrative 12% per annum, and compares 2 tenures.


EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. P is the loan amount in rupees, R is the annual rate divided by 12 and by 100, and N is the tenure in months. The formula spreads the principal and interest into equal monthly payments, so early EMIs carry more interest and later ones more principal. All figures are rounded to the nearest rupee.


TenureMonthly EMI (Rs.)Total interest (Rs.)EMI as share of salary (%)
48 months (4 years)13,1671,32,0128.8
60 months (5 years)11,1221,67,3337.4

Last updated: 22nd October, 2026


The 60-month option lowers the EMI by Rs. 2,045 but adds Rs. 35,321 in interest. The processing fee on Rs. 5 lakh is up to Rs. 20,650. Aniket picks 48 months (4 years), and his on-time EMIs help keep his score at 777 or higher.


What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down. Score of 777 or close to it?


With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.

Show More Show Less

What are the eligibility criteria and documents required?

A score of 777 meets the CIBIL criterion. To be eligible for a Bajaj Finance Personal Loan, you need to meet the criteria listed below:


CriterionRequirement
NationalityIndian
Age21 years to 80 years.

Employed withPublic, private, or multinational companies (MNCs).
CIBIL Score650 or higher.
Customer profileSelf-employed or Salaried

*You should be 80 years or younger, at the end of the loan tenure.

Last updated: 22nd October, 2026


Meeting these criteria does not guarantee approval, which depends on eligibility, verification and credit assessment. No collateral or guarantor is required.


You may need the following documents, subject to your profile and application:


Document categoryAccepted options
KYC proofAadhaar/ passport/ voter’s ID/ driving license/ Letter of National Population Register/ NREGA job card
Identity proofPAN card, Real-time image / photograph
Employment proofEmployee ID card, Letter of Allotment of Accommodation Issued by Employer
Income proofSalary slips — last 3 months, Bank account statements — last 3 months
OthersPension order, Utility bill, Phone bill, Piped gas bill, Property / Municipal tax receipt

Not every applicant needs every document. Confirm the final list of required personal loan documents during your application.

Show More Show Less

What interest rate and charges apply?

Bajaj Finance interest rates and charges on a Personal Loan, where a score of 777 supports your profile, subject to applicable terms and customer eligibility, are listed below:


ChargeAmount
Interest rate10% to 30.5% per annum, subject to applicable terms and customer eligibility
Processing feeUp to 4.13% of the loan amount, inclusive of applicable taxes
Bounce chargesRs. 700 to Rs. 1,200 per bounce
Penal chargeUp to 36% per annum on the overdue instalment
Part-prepayment (Term Loan)Up to 4.72% of the principal prepaid, inclusive of applicable taxes
Foreclosure (Term Loan)Up to 4.72% of the outstanding principal, inclusive of applicable taxes
Part-prepayment (Flexi Dropline and Flexi Hybrid Loans)No charge
Flexi facility chargeRs. 1,999 to Rs. 18,999, inclusive of applicable taxes
Annual maintenance (Flexi Dropline Loan)Up to 0.295% of the Dropline limit
Annual maintenance (Flexi Hybrid Loan)Up to 0.472% in the initial tenure; up to 0.295% in the subsequent tenure

Last updated: 22nd October, 2026

*Terms and conditions apply.


Charges are disclosed in the applicable product information and loan documents, so read your Key Fact Statement before you accept. Add the processing fee to the interest when you compare offers, and see the personal loan interest rates and charges page for details.

Show More Show Less

When should you still not borrow?

Even with a 777 score, do not borrow if the EMI would strain your budget or savings cover the cost. The table compares the options.


SituationBetter optionTrade-off
Savings cover the costUse savingsSmaller emergency fund
Existing EMIs already highClose one firstThe need waits
Clear need and EMI fitsPersonal loanInterest and a processing fee

Last updated: 22nd October, 2026


Borrow only what you need. A large new EMI can strain your budget and put a 777 score at risk if a payment slips.

Show More Show Less

How do you apply?

You apply for a Bajaj Finance Personal Loan online in five steps:

  1. Check loan eligibility: Enter the required loan amount and repayment period, then click "CHECK LOAN OFFER".
  2. Enter personal details: Enter personal, financial and employment details to receive a personalised offer.
  3. Loan offer: Review the offer details and adjust the amount or tenure to suit the applicant's needs.
  4. KYC verification: Complete KYC and verify bank details.
  5. Talk to loan specialist: The application is submitted and an executive contacts the applicant about the next steps.

The process may differ for new and existing customers, and some customers may need to provide additional documents. At the offer step, choose an EMI you can always pay, so your score stays strong.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Understanding the score

Keeping it

Is 777 a good credit score?

On the CIBIL scale of 300 to 900, 777 sits about 80% of the way up and well above the Bajaj Finance criterion of 650. It shows a strong repayment record. Lenders still assess income, existing EMIs and documents, so a strong score supports your application but does not guarantee approval on its own.

It can support a better rate offered, since it signals lower risk. The rate also depends on your income, employer and existing EMIs. Bajaj Finance charges 10% to 30.5% per annum, subject to eligibility. Check your own offer to see the rate for your profile with a 777 score, and compare the annual percentage rate.

Pay every EMI and card bill on time, keep card balances well below the limit, space out loan applications and check your report each year. Lenders report every 15 days since January 2025, so a late payment shows sooner. Auto-debits help keep a 777 score steady through every month of the loan.

Yes. A late EMI, high card balances or 2 or more new applications can pull any score down, including 777. A reporting error can too. Check your report if your score changes unexpectedly, and raise a dispute with the bureau if you find an entry that is wrong, with proof attached.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000