








Types of Fixed Deposit: Features, Options & Comparison
-
In summary
A fixed deposit (FD) is a savings instrument in which an individual deposits a lump sum with a bank, non-banking financial company (NBFC) or post office for a specified period and earns interest at an agreed rate. Different types of FDs cater to different financial needs, such as earning regular income, accumulating interest until maturity or qualifying for eligible tax deductions.
The main types of fixed deposits include:
- Cumulative FDs: Interest accumulates and is paid along with the principal at maturity.
- Non-cumulative FDs: Interest is paid at regular intervals, such as monthly or quarterly.
- Tax-saving FDs: Eligible five-year bank deposits may qualify for deductions under Section 80C, subject to applicable tax rules.
- Regular and senior citizen FDs: Deposit options with terms and interest rates that may vary by depositor category.
- Company FDs: Deposits offered by eligible companies and NBFCs, with returns and credit risk varying by issuer.
- Post office FDs: Time deposits offered through India Post under applicable government-backed schemes.
- Flexi FDs: Deposits linked to savings accounts, where available, to combine fixed-deposit interest with access to surplus funds.
The appropriate FD depends on the depositor's financial goals, preferred interest payout frequency, investment period, liquidity requirements and the creditworthiness of the institution.
Compare the latest rates and estimate your maturity amount using the Bajaj Finance FD calculator.
What are the different types of fixed deposits in India?
Avoid these mistakes while booking FD
-
Fixed deposits can be classified by how interest is paid, who offers the deposit, the depositor's eligibility and the purpose of the investment. The following are eight common types of FDs available in India.
1. What is a cumulative fixed deposit?
A cumulative fixed deposit is an FD in which the interest earned is accumulated and paid along with the principal at maturity. Interest is reinvested according to the deposit's compounding terms, allowing the investment to grow over time.
This type of FD may suit individuals who do not need regular interest income and want to receive a lump sum at the end of the investment period. It can be considered for planned expenses such as education, a future purchase or retirement savings.
2. What is a non-cumulative fixed deposit?
A non-cumulative fixed deposit pays interest at regular intervals instead of accumulating it until maturity. Depending on the scheme, the payout frequency may be monthly, quarterly, half-yearly or annually.
This option may suit retirees and other depositors who need periodic income to meet recurring expenses. The principal is generally repaid at maturity, subject to the deposit's terms. Since interest is paid out rather than reinvested, the maturity proceeds generally do not include the same accumulated interest as a comparable cumulative FD.
3. What is a tax-saving fixed deposit?
A tax-saving fixed deposit is a specific type of bank FD with a five-year lock-in period. Eligible investments may qualify for a deduction of up to Rs. 1.5 lakh under Section 80C of the Income-tax Act, 1961, subject to the applicable tax regime and eligibility conditions.
Key features include:
- A mandatory five-year lock-in period.
- A lump-sum investment.
- No premature withdrawal during the lock-in period, except where specifically permitted under applicable rules.
- Interest that is generally taxable according to the depositor's applicable tax provisions.
Tax-saving FDs may be relevant for eligible taxpayers using the old tax regime. The deduction is not generally available under the new tax regime.
4. What is a bank fixed deposit?
A bank fixed deposit is a deposit opened with a bank for a specified tenure at an agreed interest rate. The depositor invests a lump sum and receives interest according to the selected payout option or at maturity.
Bank FDs are available for different tenures, depending on the institution's offerings. Before opening an account, depositors can compare interest rates, minimum deposit requirements, maturity terms and premature withdrawal conditions.
Eligible bank deposits are covered by deposit insurance through the Deposit Insurance and Credit Guarantee Corporation (DICGC), subject to its rules and limits. The standard insurance cover is up to Rs. 5 lakh per depositor per bank, including principal and interest, in the same right and capacity.
5. What is a company or corporate fixed deposit?
A company fixed deposit, also known as a corporate FD, is a deposit accepted by an eligible company or non-banking financial company (NBFC). These deposits may offer different interest rates and tenure options compared with bank FDs.
Before investing, depositors should review the issuer's financial position, credit rating, interest payout terms and repayment record. Credit ratings from agencies such as CRISIL and ICRA can help assess creditworthiness, but they do not guarantee repayment.
Unlike eligible bank deposits, company and NBFC fixed deposits do not receive DICGC deposit insurance. The issuer's ability to repay principal and interest is therefore an important consideration.
6. What is a post office fixed deposit?
A post office fixed deposit, officially known as a Post Office Time Deposit, is a small-savings scheme offered through India Post. It allows eligible individuals to deposit a lump sum for a specified period and earn interest according to the applicable scheme rate.
Post Office Time Deposits are available for one, two, three and five years. The interest rate depends on the tenure and the rates notified by the government for the relevant period.
These deposits may suit individuals who prefer a government-backed savings instrument. Tax treatment varies by tenure and applicable rules; the five-year deposit may qualify for deductions under Section 80C for eligible taxpayers using the old tax regime.
7. What is a flexi fixed deposit?
A flexi fixed deposit links a fixed deposit with a savings account, where the bank offers this facility. It may automatically transfer surplus funds from a savings account into an FD when the balance crosses a specified threshold. If the savings balance falls below a set level, funds may be transferred back or the linked deposit may be broken, depending on the terms.
This arrangement may help account holders earn FD interest on surplus funds while retaining access to money for everyday transactions.
The minimum balance, transfer thresholds, interest calculation and premature withdrawal rules vary by bank. A flexi FD should not be confused with a standard FD that has a fixed tenure and no automatic link to a savings account.
8. What is a regular-income fixed deposit?
A regular-income fixed deposit is designed for depositors who prefer periodic interest payments. It generally uses a non-cumulative payout structure, allowing interest to be received at intervals such as monthly or quarterly.
This option may be useful for retirees or individuals who want to supplement their existing income. The principal is typically repaid at maturity, while interest payments are made according to the selected schedule.
The actual payout depends on the deposit amount, applicable interest rate, tenure and payout terms. Depositors should also consider tax on interest income when estimating the amount available for expenses.
What are the types of fixed deposits available to NRIs?
-
Non-resident Indians (NRIs) may have access to different deposit categories depending on their residency status, source of funds and eligibility. Two common categories are Non-Resident External (NRE) and Non-Resident Ordinary (NRO) fixed deposits.
1. What is an NRE fixed deposit?
An NRE fixed deposit allows eligible NRIs to deposit funds remitted from abroad or transferred from another eligible NRE account. The deposit is maintained in Indian rupees, so the value of the maturity proceeds in a foreign currency may change with exchange rates.
Interest on eligible NRE deposits is generally exempt from Indian income tax while the relevant tax conditions are met. Both principal and interest are generally repatriable, subject to applicable regulations.
2. What is an NRO fixed deposit?
An NRO fixed deposit allows eligible NRIs to hold and earn interest on income received in India, such as rent, pension or dividends, as well as other permitted funds.
Interest earned on an NRO FD is generally taxable in India, and tax may be deducted at source under applicable provisions. Repatriation of funds is subject to the relevant regulatory conditions and documentation requirements.
NRE and NRO deposits differ in their permitted sources of funds, tax treatment and repatriation rules. NRIs should verify the latest requirements with their bank or financial institution before opening an account.
What types of fixed deposits does Bajaj Finance offer?
Bajaj Finance offers fixed deposits for eligible regular customers and senior citizens, with different interest rates and payout options. Its published product information lists deposit tenures ranging from 12 to 60 months.
1. What is a regular fixed deposit from Bajaj Finance?
A regular fixed deposit is available to eligible depositors who do not qualify for the senior-citizen category. It allows them to invest a lump sum for a selected tenure and earn interest at the applicable rate.
Key features include:
- Deposit amount: Rs. 15,000 to Rs. 3 crore, as listed on the referenced product page.
- Tenure: 12 to 60 months.
- Interest payouts: Monthly, quarterly, half-yearly, yearly or at maturity, subject to the available options.
- Application: An online application facility is available for eligible customers.
The applicable interest rate depends on the tenure, deposit category and prevailing rate schedule. Depositors should check the current rates and terms before booking.
2. What is a senior citizen fixed deposit from Bajaj Finance?
A senior citizen fixed deposit is available to eligible depositors aged 60 years and above. Such deposits may offer an additional interest rate compared with deposits for regular customers.
Key features include:
- Additional interest of up to 0.40% per annum, subject to the applicable terms.
- Tenures ranging from 12 to 60 months.
- Periodic interest payout options for eligible deposits.
- An online application facility.
A senior citizen FD may help supplement retirement income or provide a planned maturity amount. The actual return depends on the amount deposited, tenure, payout selection and applicable interest rate.
3. Are fixed deposits available to NRIs through Bajaj Finance?
The referenced product page states that eligible NRIs, Persons of Indian Origin (PIOs) and Overseas Citizens of India (OCIs) holding NRO accounts can apply through an offline process, subject to the provider's eligibility requirements.
The page lists tenures of 12 to 36 months for this category and specifies that payments are accepted through cheque or RTGS/NEFT from an NRO bank account. Eligibility, documentation, applicable rates and other conditions should be confirmed directly with the provider before applying.
What are the benefits of investing in a fixed deposit?
Fixed deposits offer several features that may help individuals plan their savings. The benefits depend on the type of FD and the institution accepting the deposit.
1. How do fixed deposits provide predictable returns?
The interest rate is generally agreed upon when the FD is opened and remains fixed for its tenure. This allows depositors to estimate the interest or maturity amount in advance, subject to the scheme's terms and payout structure.
2. How can fixed deposits help manage risk?
FDs generally offer more predictable returns than market-linked investments because their interest rates are not directly linked to daily market movements. However, the level of credit risk depends on the institution. Deposit insurance applies only to eligible bank deposits within the prescribed limits, not to all fixed deposits.
3. How do fixed deposits offer flexibility?
Providers offer different tenures and interest payout options. Depositors can select a suitable duration and decide whether they need periodic interest income or a lump sum at maturity.
4. Can a fixed deposit be withdrawn before maturity?
Some FDs permit premature withdrawal, but the conditions vary. An early withdrawal may attract a penalty or result in interest being recalculated at a lower rate. Tax-saving bank FDs have a mandatory five-year lock-in, subject to applicable rules and exceptions.
5. Do fixed deposits offer higher interest than savings accounts?
FDs may offer higher interest rates than savings accounts, depending on the provider, tenure and prevailing rates. However, the comparison should also account for access to funds, premature withdrawal conditions and tax on interest.
Check out different FD Rates
Who offers fixed deposits in India?
Fixed deposits are available from several types of institutions:
- Banks: Offer deposits with different tenures, interest rates and payout schedules. Eligible deposits receive DICGC insurance within the prescribed limits.
- NBFCs: May offer competitive interest rates and varied tenures. Depositors should assess the issuer's creditworthiness because NBFC deposits are not covered by DICGC insurance.
- India Post: Offers Post Office Time Deposits under government-notified small-savings schemes.
- Eligible companies: Some companies accept deposits subject to applicable regulations and eligibility requirements. Their financial position and repayment capacity should be evaluated before investing.
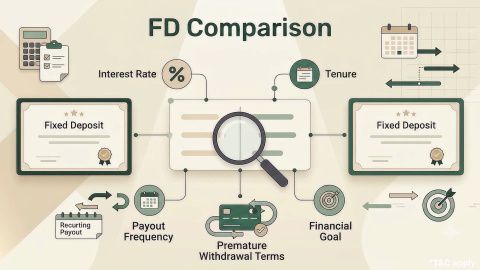
Comparing the institution, interest rate, tenure, payout terms and withdrawal conditions can help depositors understand the differences between available options.
Who can invest in a fixed deposit?
Eligibility depends on the institution and the type of deposit. Individuals who meet the provider's requirements can generally open an FD. Certain institutions also accept deposits from eligible Hindu Undivided Families (HUFs), partnerships, companies, trusts, associations and other permitted entities.
Minors may be allowed to hold deposits through a parent or legal guardian, subject to the provider's rules. NRIs and other non-resident categories must meet additional requirements for the relevant deposit account.
Before applying, prospective depositors should check the minimum deposit amount, age criteria, identity verification requirements and any restrictions specific to the scheme.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
How can you choose the right type of fixed deposit?
Choosing an FD involves more than comparing interest rates. The following factors can help narrow down the available options.
- Define the purpose: Decide whether the money is intended for regular expenses, an emergency reserve or a future financial goal.
- Select the payout structure: A cumulative FD may suit those seeking a lump sum at maturity, while a non-cumulative FD may suit those who need periodic income.
- Compare interest rates: Review rates for the intended deposit amount, tenure and depositor category.
- Check the institution's creditworthiness: Consider the provider's financial position, credit ratings and applicable deposit protection.
- Review liquidity requirements: Check whether premature withdrawal is permitted and whether penalties or restrictions apply.
- Consider tax treatment: Interest is generally taxable, while deductions may apply to eligible tax-saving deposits under specified conditions.
- Match the tenure to the financial goal: Avoid committing money for longer than necessary if it may be required earlier.
A comparison of these factors can help determine which FD features are appropriate for an individual's circumstances.
What are the tax implications of fixed deposits?
Interest earned on fixed deposits is generally taxable under the applicable income-tax rules. It is usually included in the depositor's taxable income and taxed according to the relevant provisions.
The following points are important:
- Tax on interest: Interest is generally taxable even if it is reinvested and paid only at maturity.
- Tax deducted at source (TDS): A bank or other eligible payer may deduct TDS when the applicable conditions and thresholds are met. TDS is a tax deduction at source and does not necessarily represent the depositor's final tax liability.
- Tax-saving FD deductions: Eligible five-year bank deposits may qualify for a deduction under Section 80C, subject to the applicable tax regime and conditions.
- Senior citizen provisions: Eligible senior citizens may qualify for specific deductions on deposit interest under applicable tax rules.
- Declarations and documentation: The forms and declarations used to claim TDS relief depend on the rules in force for the relevant financial year and the depositor's eligibility.
Tax rules can change. Depositors should confirm the current thresholds, applicable forms and eligibility requirements before filing their income-tax returns.
Conclusion
Fixed deposits offer a way to save a lump sum for a specified period while earning interest at an agreed rate. The different types of FDs cater to different needs: cumulative deposits are designed for those seeking a maturity payout, non-cumulative deposits provide periodic interest, and tax-saving FDs may offer deductions to eligible taxpayers. Bank, company, post office and flexi deposits also differ in their terms, liquidity and credit risk.
When comparing options, it is important to consider the interest rate alongside tenure, payout frequency, tax treatment, premature withdrawal conditions and the institution's creditworthiness. Bajaj Finance Fixed Deposit offers regular and senior citizen deposit options with multiple tenure and payout choices for eligible customers. Reviewing the current product terms can help determine whether these options align with a depositor's savings requirements.
Locate to your nearest FD branch

Related Articles
Frequently Asked Questions
Overview
Is there any special interest rate for senior citizens on Fixed Deposits?
Yes. Bajaj Finance Senior Citizen FD provides an additional interest benefit of up to 0.40% p.a., with rates reaching 8.15% p.a.
How can I open an FD account offline?
Visit the issuer’s branch with PAN, an accepted KYC document, and the completed application form. Pay using an approved cheque or bank-transfer method.
Is an FD tax-free?
No. FD interest is generally taxable, although eligible tax-saving bank deposits may offer principal deductions under applicable old-regime provisions.
Which type of deposit is suitable?
The suitable choice depends on your goal. Cumulative deposits support accumulation, while non-cumulative deposits provide regular interest income.
Can I link my savings account with an FD?
Some banks offer savings-linked flexi or sweep-in Fixed Deposits. Bajaj Finance Fixed Deposit is a separate company deposit and is not savings-account-linked.
How many types of FD are there?
There is no fixed statutory number. Common categories include cumulative, non-cumulative, tax-saving, bank, company, post office, flexi, NRE, and NRO deposits.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.